

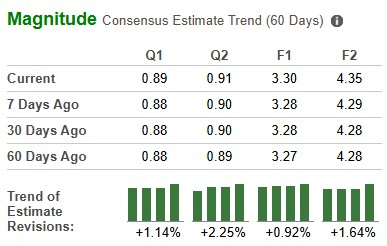
Corning Incorporated GLW is scheduled to report third-quarter 2026 earnings on Oct. 27, 2026. The Zacks Consensus Estimate for sales and earnings is pegged at $5 billion and 88 cents per share, respectively. Earnings estimates for GLW have increased 0.61% to $3.29 for 2026 and increased 0.47% to $4.3 for 2027 over the past 60 days.
GLW Estimate Trend
Image Source: Zacks Investment Research
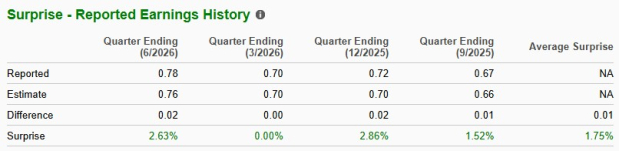
Earnings Surprise History
The advanced glass substrates producer has a solid trailing four-quarter earnings surprise history. It delivered a four-quarter earnings surprise of 1.75%, on average.
Image Source: Zacks Investment Research
Earnings Whispers
Our proven model predicts a likely earnings beat for Corning for the third quarter. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), #2 (Buy) or #3 (Hold) increases the chances of an earnings beat. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter. That is exactly the case here.
Corning currently has an ESP of +0.68% and a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factor Shaping Upcoming Results
Corning’s Optical Communications business is expected to remain a key driver of its third-quarter 2026 performance. Growing investment in AI infrastructure and hyperscale data centers is boosting demand for optical fiber, cables and high-density connectivity solutions.
Multiyear agreements with Amazon and NVIDIA, along with Corning's previously announced partnership with Meta, provide further support for demand. The company's September agreement with Verizon to supply high-density optical fiber and connectivity solutions through 2032 also strengthens its long-term growth prospects.
Corning's Solar business is another important factor to watch as the company seeks to improve profitability following production-related disruptions. An extended maintenance shutdown and equipment upgrades at the wafer facility weighed on profitability during the second quarter. Management expects sales and profits to improve in the third quarter as production resumes and operational efficiency strengthens. However, performance across other businesses remains uneven. Demand trends in consumer electronics and automotive markets, along with higher memory prices affecting smartphones, could hinder growth in some of Corning's businesses.
Price Performance
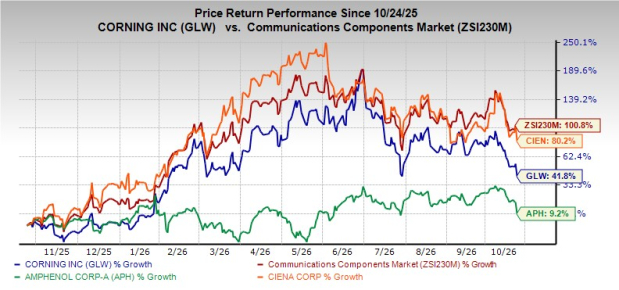
Over the past year, Corning has surged 41.8% compared with the industry’s growth of 100.8%. It has outperformed peers like Amphenol Corporation APH but lagged Ciena Corporation CIEN over this period. While Amphenol has gained 9.2%, Ciena has jumped 80.2%.
Image Source: Zacks Investment Research
Key Valuation Metric
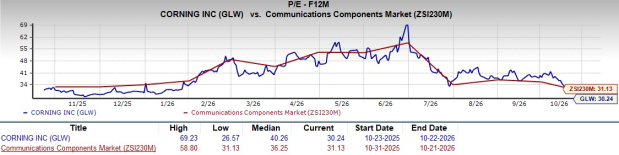
From a valuation standpoint, Corning appears discounted relative to the industry and is trading below its mean. Going by the price/earnings ratio, the company’s shares currently trade at 30.24 forward earnings, lower than 31.13 for the industry and higher than the stock’s mean of 26.57.
Image Source: Zacks Investment Research
Investment Consideration
Corning is strengthening its position in the expanding AI infrastructure market through its optical connectivity portfolio and relationships with major technology companies. As data centers require greater bandwidth and more sophisticated networking capabilities, demand for optical fiber, cable and connectivity products could provide a significant growth opportunity. The company's planned expansion of U.S. manufacturing capacity and its investment in next-generation optical technologies further support its long-term prospects.
Under the upgraded Springboard plan, management aims to reach annualized sales run rates of $20 billion by the end of 2026, $30 billion by the end of 2028 and $40 billion by the end of 2030. However, these targets depend on successful execution and sustained customer demand.
The Solar business offers another potential source of growth as Corning expands its U.S. manufacturing capabilities across polysilicon, wafers and modules. A recovery in production efficiency could support improved segment profitability.
End Note
AI-driven demand for optical connectivity, long-term customer agreements and improving operating margins are major positives for Corning ahead of third-quarter results. The anticipated recovery in Solar profitability could provide an additional boost. Sustained improvement in its profitability and cash generation over the past few quarters is a tailwind. Hence, with a Zacks Rank #2, Corning appears to be a good investment option at present.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Corning Incorporated (GLW): Free Stock Analysis Report
Ciena Corporation (CIEN): Free Stock Analysis Report
Amphenol Corporation (APH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).