

Visa Inc. V is set to report its fourth-quarter fiscal 2026 results on Oct. 27, 2026, after market close. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at $3.43 per shareon revenues of $12.08 billion.
The estimate for fiscal fourth-quarter earnings has remained stable over the past 60 days. The bottom-line projection indicates a year-over-year increase of 15.1%. The Zacks Consensus Estimate for quarterly revenues suggests year-over-year growth of 12.7%.
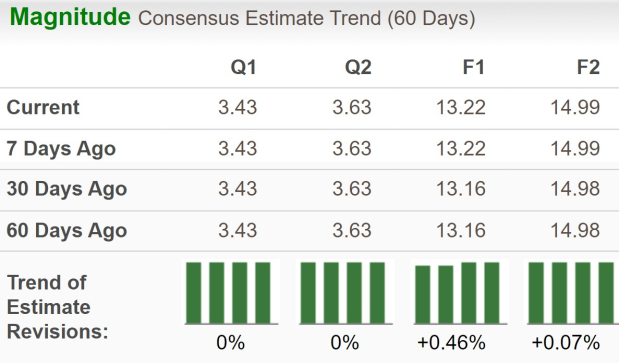
For fiscal 2026, the Zacks Consensus Estimate for Visa’s revenues is pegged at $45.84 billion, implying a rise of 14.6% year over year. The consensus mark for EPS is pegged at $13.22, suggesting a jump of about 15.3% year over year.
The payments juggernaut has a robust history of surpassing earnings estimates. It beat estimates in each of the last four quarters, with the average being 2.8%. This is depicted in the graph below:
Visa Price, Consensus and EPS Surprise
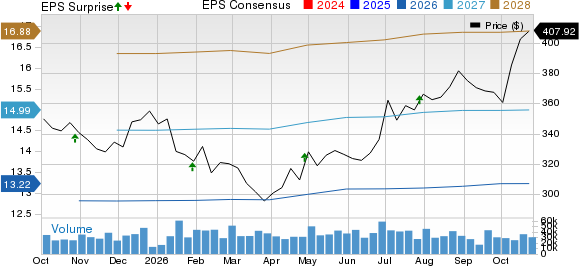
Visa Inc. price-consensus-eps-surprise-chart | Visa Inc. Quote
Q4 Earnings Whispers for Visa
Our proven model predicts a likely earnings beat for the company this time around as well. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That is precisely the case here.
Visa has an Earnings ESP of +0.66% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping Visa’s Q4 Results
Visa appears well positioned to deliver solid year-over-year growth in fiscal fourth-quarter results, supported by higher consumer spending, rising digital payment adoption and continued growth in cross-border transactions. The Zacks Consensus Estimate calls for a 7.5% increase in total Gross Dollar Volume from the year-ago quarter, while our model projects 7.7% growth.
As the company draws revenues as a set percentage of total transaction value every time a customer makes payments with a debit/credit card, higher spending means more revenue in the form of transaction processing fees. The Zacks Consensus Estimate for total processed transactions points to 9.6% year-over-year growth, slightly above our model's projection of 9.4%.
The consensus mark for total payment volumes indicates a 9.1% year-over-year increase. We expect the metric for U.S. operations alone to jump nearly 8% year over year. Similarly, our model predicts 15.6% year-over-year growth in Latin America and 11.2% in CEMEA.
The Zacks Consensus Estimate for data processing revenues indicates 15% growth in the fiscal fourth quarter from the year-ago level of $5.39 billion. Similarly, the consensus mark for service revenues suggests 12.6% year-over-year growth, whereas we expect the metric to grow 13.3% from $4.6 billion.
Furthermore, the consensus estimate for international transaction revenues indicates 8.9% growth from a year ago. Continuous growth in cross-border volumes is expected to have supported the metric. The factors stated above are expected to have positioned Visa for an earnings beat. However, rising expenses and client incentives (a contra-revenue item) are likely to have partially offset the positive impact of higher volumes.
We expect adjusted total operating expenses for the quarter under review to increase 11.6% year over year due to increased Personnel, Professional Fees, Marketing, and Network and Processing expenses. Meanwhile, the Zacks Consensus Estimate for client incentives is pegged at $4.98 billion for the to-be-reported quarter.
Visa Price Performance & Valuation
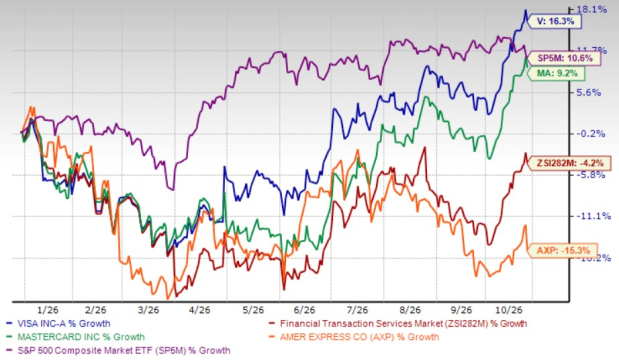
Visa's stock has gained 16.3% in the year-to-date period. It has outperformed the industry’s 4.2% fall andthe S&P 500’s increase of 10.6%. In comparison, its peers like Mastercard Incorporated MA and American Express Company AXP have increased 9.2% and declined 15.3%, respectively, during this time.
YTD Price Performance – V, MA, AXP, Industry & S&P 500
Now, let’s look at the value Visa offers investors at current levels.
The company’s valuation looks somewhat stretched compared with the industry average. Currently, Visa is trading at 26.97X forward 12-month earnings, above the industry’s average of 18.76X, and remains above its five-year median of 25.59X.
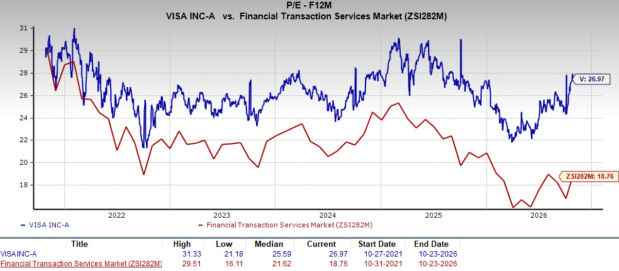
In comparison, Mastercard is trading at 27.84X forward 12-month earnings. American Express, on the other hand, is trading at 15.86X now.
How Should You Play Visa Ahead of Q4 Earnings?
Visa enters its fiscal fourth-quarter earnings report with plenty working in its favor. Steady consumer spending, higher transaction volumes and cross-border demand should support revenue and earnings growth. Its record of topping estimates adds to that case.
The longer-term story is also taking shape. Visa is expanding stablecoin-linked payments and settlement, building tools for AI-driven shopping and growing its Value-Added Services business. These efforts offer new ways to earn revenue beyond traditional card transactions, without straying far from the network that underpins its business.
Still, expectations are not low. After outperforming the industry and broader market this year, Visa trades above both its industry average and its own five-year median valuation. Higher operating expenses and client incentives could limit how much stronger payment activity flows through to earnings. Competition from alternative payment networks and regulatory scrutiny also remain concerns.
For existing shareholders, the company's strong core business and newer growth opportunities support staying invested through the report. New investors, however, may want to avoid chasing the stock ahead of earnings, particularly with its valuation leaving little room for disappointment.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Visa Inc. (V): Free Stock Analysis Report
Mastercard Incorporated (MA): Free Stock Analysis Report
American Express Company (AXP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).