

Newell Brands Inc. NWL is expected to register a year-over-year increase in the top line when it reports third-quarter 2026 results on Oct. 30, 2026, before the opening bell. The Zacks Consensus Estimate for quarterly revenues is pegged at $1.85 billion, indicating a rise of 2.5% from the figure reported in the year-ago quarter's actual.
The consensus estimate for the bottom line is pegged at 20 cents per share, which indicates an increase of 17.7% from the year-ago quarter's reported figure. The consensus mark has been revised upward by 1 cent in the past 30 days.
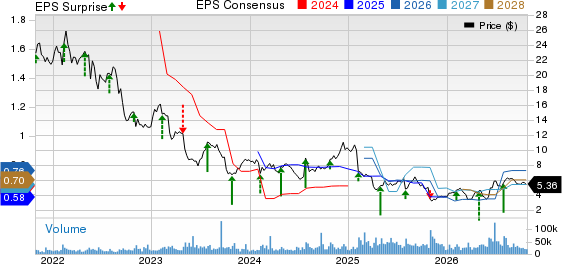
In the last reported quarter, the Atlanta, GA-based company’s earnings surpassed the Zacks Consensus Estimate by 121.1%. Its bottom line beat the consensus estimate by 40%, on average, in the trailing four quarters.
Newell Brands Inc. Price, Consensus and EPS Surprise
Newell Brands Inc. price-consensus-eps-surprise-chart | Newell Brands Inc. Quote
Factors Likely to Impact NWL’s Q3 Results
Newell’s top-line performance is likely to have benefited from stronger product innovation, distribution gains and improved retail execution. Better category planning, stronger retailer relationships and improved service levels have helped the company secure additional shelf space.
Management indicated that existing customer commitments supported further distribution gains during the second half. These gains, coupled with increased advertising and promotional support, are likely to have supported consumer demand and sales in the to-be-reported quarter.
Stronger back-to-school execution and consumer-focused innovation could have provided additional momentum. Earlier merchandising setups and strong order fulfillment positioned Sharpie, Elmer’s and Prismacolor to capture seasonal purchases, with management reporting encouraging early-season demand and market-share gains. Favorable consumer responses to Graco’s rotating car seats, Rubbermaid’s Brilliance Glass products and Coleman’s Snap & Go coolers also provided a foundation for continued growth. Newell’s innovation pipeline, supported by focused marketing and retail activation, is likely to have strengthened brand appeal and created further growth opportunities.
Newell’s FUEL productivity program, restructuring actions and disciplined overhead management are likely to have supported profitability. Manufacturing improvements, procurement savings and supply-chain optimization could have enhanced operating efficiency while helping fund investment in innovation and brand building. Selective pricing and revenue management initiatives, together with the company’s tariff-advantaged manufacturing footprint, could have helped preserve attractive consumer value and protect margins. Combined with stronger sales, these initiatives are expected to have supported earnings growth in the quarter under review.
During its last earnings call, management projected third-quarter net sales and core sales growth of 2-3% each. Our model expects 2.5% year-over-year sales growth and a core sales increase of 2.4%, led by anticipated core sales growth of 5.4% in Learning and Development, and 5% in Outdoor and Recreation. Management envisioned a normalized operating margin of 9.5-10.2% and normalized earnings per share (EPS) of 18-20 cents. Our model projects a normalized operating margin of 10.2% and a normalized EPS of 19 cents, consistent with expectations for year-over-year improvement in both sales and earnings.
What the Zacks Model Unveils For NWL
Our proven model conclusively predicts an earnings beat for Newell this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is exactly the case here.
Newell currently has an Earnings ESP of +2.26% and a Zacks Rank of 3. You can uncover the best stocks before they are reported with our Earnings ESP Filter.
Valuation Picture
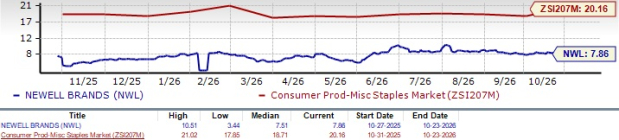
From a valuation perspective, Newell offers an attractive opportunity, trading at a discount relative to historical and industry benchmarks. With a forward 12-month price-to-earnings ratio of 7.86X, which is below the five-year high of 10.51X and the Consumer Products - Staples industry’s average of 20.16X, the stock offers compelling value for investors seeking exposure to the sector.
Image Source: Zacks Investment Research
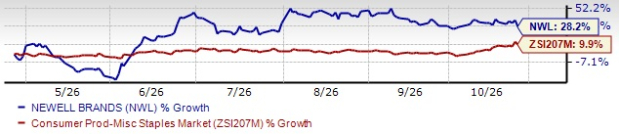
The recent market movements show that NWL shares have gained 28.2% over the past six months compared with the industry's 9.9% growth.
Image Source: Zacks Investment Research
Other Stocks With the Favorable Combination
Here are some other companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
BJ's Wholesale Club BJ currently has an Earnings ESP of +2.54% and a Zacks Rank of 2. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for BJ's Wholesale’s upcoming quarterly revenues is pegged at $5.94 billion. The figure indicates an 11.1% increase from the prior-year quarter's actual. The Zacks Consensus Estimate for BJ's Wholesale’s quarterly earnings per share is pegged at $1.22, suggesting a 5.2% rise from the year-ago period figure. BJ delivered a trailing four-quarter earnings surprise of 4.8%, on average.
Church & Dwight Co. CHD currently has an Earnings ESP of +0.06% and a Zacks Rank of 3. The company is likely to register bottom-line growth and a decline in its top line when it reports third-quarter 2026 numbers.
The Zacks Consensus Estimate for Church & Dwight’s quarterly revenues is pegged at $1.58 billion, indicating a decrease of 0.2% from the figure reported in the prior-year quarter. The consensus estimate for CHD’s quarterly earnings of 90 cents per share implies a rise of 11.1% from the year-ago quarter’s reported level. CHD has a trailing four-quarter earnings surprise of 3.9%, on average.
Colgate-Palmolive Company CL has an Earnings ESP of +0.01% and a Zacks Rank of 3 at present. The company is expected to register top-line growth when it reports third-quarter 2026 figures. The Zacks Consensus Estimate for Colgate’s quarterly bottom line has been unchanged over the past 30 days at earnings of 92 cents per share. The consensus mark for earnings indicates an improvement of 1.1% from the figure reported in the year-ago quarter.
The consensus estimate for quarterly revenues is pegged at $5.33 billion, which indicates a gain of 3.9% from the figure reported in the year-ago quarter. CL has delivered an earnings surprise of 3.2%, on average, in the trailing four quarters.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Newell Brands Inc. (NWL): Free Stock Analysis Report
Colgate-Palmolive Company (CL): Free Stock Analysis Report
BJ's Wholesale Club Holdings, Inc. (BJ): Free Stock Analysis Report
Church & Dwight Co., Inc. (CHD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).