

PACCAR Inc. PCAR benefits from recovering truck demand, strong pricing power and aftermarket growth. However, operational challenges, regulatory uncertainty and rising investment requirements could limit near-term performance.
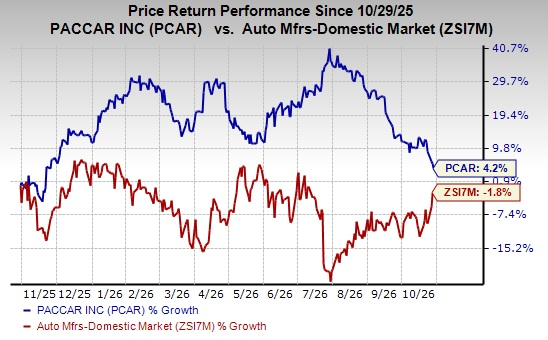
Shares of PCAR are up 4.2% over the past year against the industry’s 1.8% fall.
Let's examine the factors shaping PCAR's investment-worthiness.
PCAR's Improving Truck Demand Supports Profitability
PACCAR continues to benefit from recovering North American truck demand as fleet replacement needs support orders. Management expects U.S. and Canadian Class 8 industry sales of 240,000-260,000 units for 2026 and 240,000-280,000 units for 2027. Global truck deliveries increased to 40,100 units in the third quarter of 2026 from 31,900 a year earlier.
Third-quarter truck revenues rose 27.9% year over year to $5.60 billion, while pretax income increased to $454.5 million from $102.5 million. Favorable pricing and disciplined operations supported profitability. Higher deliveries could further improve factory utilization and earnings as the market recovers.
PACCAR's Aftermarket Growth and Financial Strength
PACCAR Parts generated record third-quarter 2026 revenues of $1.78 billion, up 3.2% year over year. Nine-month revenues increased to $5.24 billion from $5.14 billion, supported by its TRP brand, Fleet Services and expanding dealer relationships. Management expects full-year 2026 parts revenue growth of 3-5%.
PACCAR Financial Services also supports earnings stability, with third-quarter pretax income rising 9.4% to $138.1 million. As of Sept. 30, 2026, PACCAR held $9.24 billion in cash and marketable securities and $20.93 billion in stockholders' equity. Its investment-grade credit ratings and dividend growth history provide additional financial flexibility.
Despite these strengths, PACCAR faces challenges that could temper its growth prospects.
PCAR's Technology Investments Support Long-Term Growth
PACCAR's upcoming PACCAR Connect platform, expected in Kenworth and Peterbilt Class 8 trucks in early 2027, could generate recurring subscription revenues and strengthen aftermarket retention. Investments in cleaner diesel engines, hybrid and electric powertrains, and autonomous technologies further support long-term competitiveness. However, these initiatives require substantial investment, with research and development spending projected at $460-$500 million in 2027.
PCAR's Supply and Regulatory Challenges Pose Risks
Component shortages restricted third-quarter deliveries, limiting production despite improving demand. Management expects fourth-quarter trucks, parts and other gross margins of 14-15%, broadly consistent with the third quarter's 14.5%.
Uncertainty surrounding 2027 emissions regulations and nonconformance penalty levels could also delay truck purchases and complicate pricing decisions. Until regulatory requirements become clearer, demand and production planning may remain challenging.
PCAR's Parts Profitability and Cash Flow Face Pressure
Despite record parts revenues, third-quarter pretax income declined 1.4% year over year to $404.4 million. Unfavorable product mix, reduced truck utilization and postponed maintenance purchases continue to pressure profitability.
Operating cash flow declined to $2.52 billion in the first nine months of 2026 from $3.27 billion a year earlier, partly due to higher receivables and inventories. With capital expenditures projected at $650-$700 million annually in 2026 and 2027, elevated investment requirements could constrain near-term free cash flow.
PACCAR's improving truck demand, strong profitability and aftermarket growth provide a solid foundation, but supply constraints, regulatory uncertainty and rising investments cloud its near-term outlook. Until cash flow improves and operational challenges ease, investors should maintain a neutral stance on the stock.
PACCAR Inc. Price and Consensus
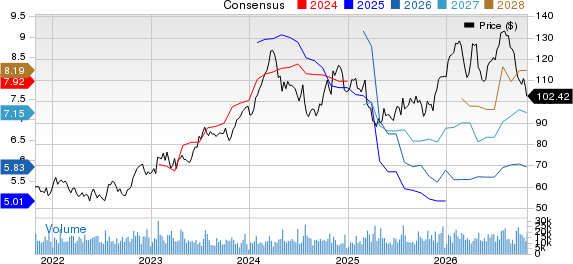
PACCAR Inc. price-consensus-chart | PACCAR Inc. Quote
PCAR's Zacks Rank & Key Picks
PCAR currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks in the Auto space are Honda Motor HMC, Lucid Group, Inc. LCID and Toyota TM. HMC, LCID and TM carry a Zacks Rank #2 (Buy). You can see the complete list of today's Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for HMC's current-year earnings is pegged at $2.32 per share, indicating a 210% year-over-year increase. The estimate for earnings has moved northward over the past 60 days.
The Zacks Consensus Estimate for LCID's current-year loss is pegged at $12.15 per share. Its earnings missed the Zacks Consensus Estimate in each of the trailing four quarters, with the average negative earnings surprise being 30.3%.
The Zacks Consensus Estimate for TM's current fiscal-year earnings is pegged at $21.18 per share, indicating a 8.01% year-over-year increase. The estimate for earnings has moved down over the past 30 days.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PACCAR Inc. (PCAR): Free Stock Analysis Report
Toyota Motor Corporation (TM): Free Stock Analysis Report
Honda Motor Co., Ltd. (HMC): Free Stock Analysis Report
Lucid Group, Inc. (LCID): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).