

The Hershey Company HSY maintained its 2027 sales growth outlook during its third-quarter 2026 earnings call, but management acknowledged growing risks to profitability from cautious consumers, freight inflation and higher non-cocoa input costs.
Executives emphasized innovation, targeted pricing and productivity improvements as key growth drivers. However, analyst questions highlighted uncertainty surrounding volume recovery, market share and the timing of margin expansion.
Hershey reported adjusted earnings of $2.64 per share, exceeding the Zacks Consensus Estimate of $2.12, while revenues of $3.28 billion surpassed the $3.25 billion estimate.
Hershey Company (The) Price, Consensus and EPS Surprise
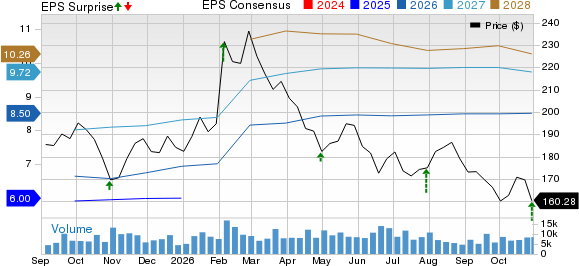
Hershey Company (The) price-consensus-eps-surprise-chart | Hershey Company (The) Quote
Hershey Maintains 2027 Sales Growth Outlook
President and CEO Kirk Tanner reaffirmed expectations for 2027 sales growth of 2% to 4%, supported by innovation, brand investments and low-single-digit carryover pricing.
However, Tanner acknowledged that continued consumer spending pressure could push growth toward the lower end of that range.
CFO Dave Hulays indicated that the company's initial double-digit earnings growth framework remains achievable under improved conditions. Persistent cost pressures and weaker consumer demand could leave earnings growth below the original framework.
HSY Faces Consumer Pressure and Volume Challenges
Hershey's third-quarter organic sales increased 0.8%, supported by approximately 11 percentage points of pricing, while volume declined roughly 10 points.
During the call, UBS questioned weakening confectionery demand. Management highlighted convenience stores as a significant pressure point, with category sales declining 5% in September and weakness continuing into October.
Hulays attributed changing shopping patterns to household financial pressures, including gasoline prices and interest rates. Consumers increasingly favored mass retail, club stores and e-commerce.
Management nevertheless reported improving unit trends across Hershey, Kit Kat, Cadbury and Kisses. Tanner expects further improvement as pricing moderates, although the recovery may be uneven.
Hershey Expands Innovation and Value Offerings
Tanner highlighted a planned 50% increase in the company's 2027 innovation pipeline, with new products expected to contribute three times more growth than in 2026.
During questioning from Evercore ISI, management emphasized targeted promotions and price-pack architecture rather than broad price reductions. These initiatives aim to improve affordability while protecting the company's pricing strategy.
Upcoming innovations include Hershey Rolls, new Ice Breakers gum offerings and additional Dot's and Reese's products.
Management also identified premium, sweets, functional and better-for-you categories as expansion opportunities.
Tanner expects stronger innovation, merchandising and advertising to improve competitiveness following market-share pressure.
HSY Targets Margin Recovery Amid Cost Inflation
Third-quarter adjusted gross margin expanded 1,090 basis points to 42.7%, supported by pricing, productivity savings, tariff refunds and lower net commodity costs.
Hulays expects meaningful margin improvement in 2027, supported partly by the timing of cocoa hedges. However, elevated freight, logistics and other input costs remain obstacles.
Responding to Goldman Sachs, Hulays outlined productivity opportunities involving factory digitization, automation, logistics optimization and data-driven decision-making.
Management continues targeting gross margins in the mid-40% range over the longer term, with that ambition extending into 2028 and beyond.
Hershey's Salty Snacks Business Faces Supply Constraints
North America Salty Snacks revenues increased 22.3% to $392.7 million, benefiting substantially from the LesserEvil acquisition. Organic sales increased 2.3%.
However, segment income declined 17.9% as manufacturing, logistics and marketing expenses increased.
Responding to Wells Fargo, Tanner acknowledged that demand continues to exceed available supply. Manufacturing capacity additions scheduled for the first half of 2027 should improve service levels.
Hulays added that better shipment utilization and logistics efficiency could help reduce costs, although higher freight rates remain a headwind.
HSY Balances Growth Investments With Execution Risks
Management's overarching priority remains restoring volume momentum while strengthening profitability through innovation, productivity and improved execution.
Tanner maintained confidence in the company's controllable growth initiatives, while Hulays emphasized flexibility in allocating investment toward opportunities offering stronger returns.
The 2027 outlook remains sensitive to consumer demand, commodity costs and the pace of operational improvements.
Hershey's Zacks Rank and Style Scores Signal Mixed Prospects
HSY currently carries a Zacks Rank #3 (Hold), reflecting a neutral near-term outlook. Its Growth Score of A indicates favorable growth characteristics, while Value and Momentum Scores of C reflect comparatively moderate attractiveness in those categories. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock's VGM Score of B indicates a favorable combination of value, growth and momentum characteristics. However, the Zacks framework generally favors stocks carrying a Zacks Rank #1 or #2 (Buy) alongside strong Style Scores.
The Zacks Rank remains subject to change as analysts revise earnings estimates following the quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hershey Company (The) (HSY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).