

Solaris Energy Infrastructure SEI is set to release third-quarter 2026 results on Nov. 4. The Zacks Consensus Estimate for the to-be-reported quarter is a profit of 17 cents per share on revenues of $252.9 million.
Let’s delve into the factors that might have influenced the company’s performance in the September quarter. But it’s worth taking a look at SEI’s previous-quarter performance first.
Highlights of Q2 Earnings & Surprise History
In the last reported quarter, this Houston, TX-based oilfield solutions provider beat the consensus mark, driven by the results of the Power Solutions segment. Solaris Energy Infrastructure reported adjusted net income per share of 39 cents in the second quarter, surpassing the Zacks Consensus Estimate of 31 cents. Revenues of $219.4 million also topped the consensus estimate by 10.8%.
SEI beat the Zacks Consensus Estimate in each of the last four quarters. This is depicted in the graph below:
Solaris Energy Infrastructure, Inc. Price and EPS Surprise
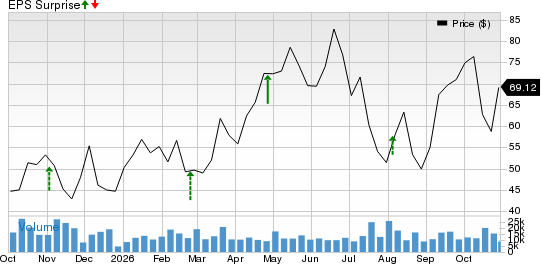
Solaris Energy Infrastructure, Inc. price-eps-surprise | Solaris Energy Infrastructure, Inc. Quote
Trend in Estimate Revision
The Zacks Consensus Estimate for the third-quarter bottom line has remained unchanged in the past seven days. The estimated figure indicates a 46.9% decline year over year. The Zacks Consensus Estimate for revenues, however, suggests a 51.6% increase from the year-ago period.
Factors to Consider
Solaris Energy Infrastructure's Power Solutions segment is likely to have benefited from rising demand for dedicated power infrastructure, particularly from data center operators. The segment generated $96 million in adjusted EBITDA during the second quarter, reflecting 34% sequential growth. Additionally, expanded service offerings, including electrical distribution and other supporting services, could strengthen third-quarter profitability. The Zacks Consensus Estimate for third-quarter 2026 Power Solutions adjusted EBITDA is pegged at $104 million. Continued demand for reliable power and broader customer service requirements could support the segment's earnings performance.
SEI's acquisition of Global Energy Services Alliance in July 2026 is likely to have supported third-quarter earnings by adding installation, maintenance, equipment repair and other power-related services. The addition, alongside stronger performance from existing power services, prompted management to raise third-quarter adjusted EBITDA guidance to $110-$130 million from $90-$105 million. The higher outlook suggests that stronger service demand and contributions from acquired businesses could lift quarterly earnings.
Solaris Energy Infrastructure's Logistics Solutions segment could have benefited from sustained demand for equipment used in oilfield operations and a favorable mix of projects. During the second quarter, adjusted EBITDA increased 7% sequentially to $25 million despite a 10% revenue decline, indicating improved profitability. Management also highlighted strong demand for its top-fill equipment, with available capacity effectively sold out. These conditions could have supported equipment utilization and service activity during the third quarter. The Zacks Consensus Estimate for the segment's third-quarter revenues is pegged at $68 million compared with $61 million reported in the preceding quarter.
Why a Likely Positive Surprise?
Our proven model predicts a likely earnings beat for Solaris Energy Infrastructure this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. That is the case here.
You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
SEI has an Earnings ESP of +8.00% and a Zacks Rank #1.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Other Stocks to Consider
Solaris Energy Infrastructure is not the only company looking up this earnings cycle. Here are some other energy firms that you may want to consider on the basis of our model:
Permian Resources PR has an Earnings ESP of +6.24% and a Zacks Rank #1. The firm is scheduled to release earnings on Nov. 4.
Permian Resources beat the Zacks Consensus Estimate for earnings in each of the last four quarters, with the average being 20.3%. Valued at more than $21 billion, PR has surged 103.5% in a year.
Targa Resources TRGP has an Earnings ESP of +2.05% and a Zacks Rank #2. The firm is scheduled to release earnings on Nov. 5.
The Zacks Consensus Estimate for 2026 earnings of Targa Resources indicates 34.5% growth. Valued at around $65.6 billion, TRGP is up 102.7% in a year.
Gulfport Energy GPOR has an Earnings ESP of +1.49% and a Zacks Rank #3.Gulfport Energy is scheduled to release earnings on Nov. 4.
For 2026, GPOR has a projected earnings growth rate of 10.4%. Valued at nearly $3 billion, Gulfport Energy has lost 9.5% in a year.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Solaris Energy Infrastructure, Inc. (SEI): Free Stock Analysis Report
Gulfport Energy Corporation (GPOR): Free Stock Analysis Report
Targa Resources, Inc. (TRGP): Free Stock Analysis Report
Permian Resources Corporation (PR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).