

Cencora, Inc. COR is slated to report fourth-quarter fiscal 2026 results on Nov. 4, before market open.
In the last reported quarter, the company delivered an earnings surprise of 2.52%. COR’s earnings beat estimates in three of the trailing four quarters and missed once, delivering an average surprise of 0.76%.
Cencora’s Q4 Estimates
The Zacks Consensus Estimate for revenues is pegged at $88.16 billion, up 5.3% from the prior-year quarter’s level. The consensus mark for earnings is pinned at $4.55 per share, indicating an improvement of 18.5% from the prior-year quarter’s figure.
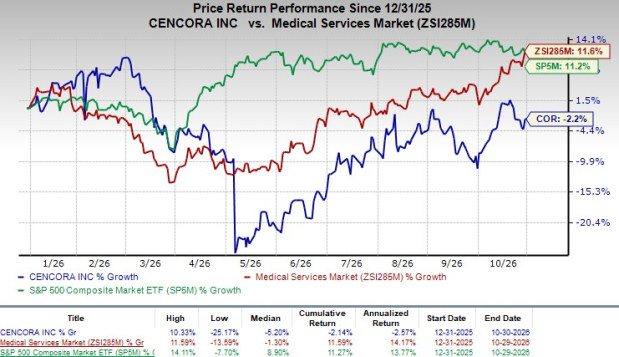
So far this year, COR’s shares have lost 2.2% against the industry’s growth of 11.6%. The S&P Index has gained 11.2% in the same period.
Image Source: Zacks Investment Research
Factors to Consider Before COR’s Q4 Results
Cencora is expected to report another quarter of solid earnings growth in its fiscal fourth-quarter 2026 results, supported by continued strength in specialty pharmaceutical distribution, improving contributions from its management services organizations (MSOs) and growth in international operations. Following a strong fiscal third-quarter performance, management expressed confidence in the company's underlying business momentum and raised its fiscal 2026 adjusted earnings per share guidance to $17.75-$17.95. The fourth quarter is expected to have benefited from the full-year contribution of OneOncology, the lapping of the previous oncology customer loss and easier expense comparisons.
Within the U.S. Healthcare Solutions segment, specialty pharmaceutical distribution is likely to have remained a key growth driver. Continued strength in health systems and physician practices, alongside resilient demand for oncology and retina therapies, is likely to have supported segment performance. OneOncology and Regional Cancer Care Associates (RCA) are expected to have continued contributing to operating income growth, with both businesses performing ahead of management's expectations in the fiscal third quarter. Improving physician utilization trends and continued physician additions across the MSO platforms are likely to have provided further support. Moreover, management expects the U.S. segment to deliver its strongest organic operating income growth of fiscal 2026, excluding OneOncology, in the fiscal fourth quarter.
However, U.S. revenue growth is likely to have remained affected by manufacturer list-price reductions, branded-to-biosimilar conversions and lower sales to a large mail-order customer. In the fiscal third quarter, manufacturer price reductions represented a $2.4 billion headwind to revenue growth, partly offset by a $2.3 billion year-over-year increase in GLP-1 sales. While continued growth in specialty drug volumes and GLP-1 demand should have supported revenues, these pricing and customer-mix dynamics are expected to have remained important factors. The growing adoption of Part B biosimilars, meanwhile, presents a longer-term opportunity, given Cencora's distribution, group purchasing organization and physician-support capabilities.
The International Healthcare Solutions segment is expected to have maintained healthy operating momentum, supported by continued strength in European pharmaceutical distribution, World Courier and European third-party logistics (3PL) operations. In the fiscal third quarter, the segment delivered 21% reported operating income growth, with World Courier and European 3PL both generating double-digit operating income growth. Strong contract renewals, new business wins and improving demand in specialty logistics are likely to have supported fiscal fourth-quarter performance. However, the benefit from the timing of manufacturer price increases in a developing-market country, which supported European distribution in previous quarters, is not expected to have repeated in the fiscal fourth quarter, potentially moderating the segment's growth.
Operating profitability is likely to have remained supported by a favorable specialty business mix, continued MSO contributions and productivity improvements. Cencora's digital transformation initiatives, including the use of artificial intelligence in demand forecasting, are also expected to have supported operational efficiency, improved product availability and streamlined business processes in the fiscal fourth quarter. However, higher interest expense associated with the debt raised to finance the OneOncology acquisition is likely to have weighed on earnings. The company has made progress in reducing acquisition-related debt, having fully repaid the $800 million RCA financing-related term loan balance by July 2026.
Cencora, Inc. Price and EPS Surprise
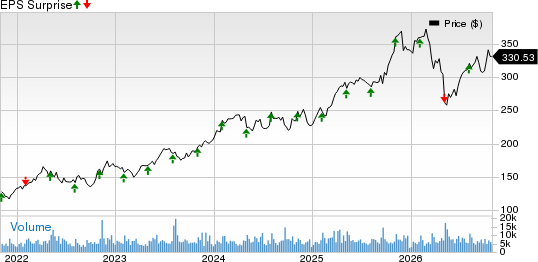
Cencora, Inc. price-eps-surprise | Cencora, Inc. Quote
Earnings Beat Unlikely
Our proven model does not predict an earnings beat for COR this earnings season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat, which is not the case here.
Earnings ESP:Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, is +0.66%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Zacks Rank:The company carries a Zacks Rank #4 (Sell) at present.
Stocks Worth a Look
Here are some medical stocks worth considering, as these have the right combination of elements to post an earnings beat this time:
Phibro Animal Health PAHC has an Earnings ESP of +2.10% and a Zacks Rank #1. The company is expected to release first-quarter fiscal 2027 results soon.
PAHC’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 18.4%. The Zacks Consensus Estimate for the company’s first-quarter EPS indicates an increase of 8.2% from the year-ago quarter’s figure.
IDEXX Laboratories IDXX has an Earnings ESP of +0.59% and a Zacks Rank #2. The company is slated to release third-quarter 2026 results on Nov. 2.
IDXX’s earnings beat estimates in each of the trailing four quarters, the average surprise being 5.7%. The Zacks Consensus Estimate for the company’s third-quarter EPS implies an increase of 9.1% from the year-ago quarter’s figure.
Becton, Dickinson and Company BDX or BD has an Earnings ESP of +3.28% and a Zacks Rank #2. The company is due to release fourth-quarter fiscal 2026 results on Nov. 5.
BD’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 2.94%. The Zacks Consensus Estimate for the company’s fourth-quarter EPS calls for a rise of 2.5% from the year-ago quarter’s figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cencora, Inc. (COR): Free Stock Analysis Report
Becton, Dickinson and Company (BDX): Free Stock Analysis Report
IDEXX Laboratories, Inc. (IDXX): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).