

September and October are historically known as the worst-performing months for U.S. equities. This year, these two months ended on a mixed note. However, major differences were there between these two months.
The powerful artificial intelligence (AI) trade maintained its momentum in September but faced severe volatility in October. The tech-heavy Nasdaq tumbled 5.3%, marking its sharpest monthly decline since March 2025. The S&P 500 declined 0.9%, while the Dow added 1.7%.
However, the oil and energy stocks rallied in October, buoyed by soaring crude oil prices due to prolonged geopolitical conflicts in the Middle East. Here, we recommend three energy bigwigs with a favorable Zacks Rank that are expected to maintain their momentum in November, too.
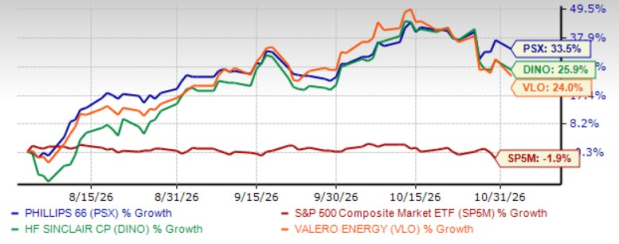
These are: Phillips 66 PSX, Valero Energy Corp. VLO and HF Sinclair Corp. DINO. Each of the stocks currently sports a Zacks Rank #1 (Strong Buy) and has a Zacks Momentum Score of A. You can see the complete list of today’s Zacks #1 Rank stocks here.
The chart below shows the price performance of our three picks in the past three months.
Image Source: Zacks Investment Research
Phillips 66
Phillips 66 reported third-quarter 2026 adjusted earnings of $14.08 per share, up 458.7% from $2.52 per share a year ago. The bottom line beat the Zacks Consensus Estimate of $11.97 by 17.63%. Total revenues and other income increased 47.2% to $51.51 billion from $34.98 billion a year earlier. The top line surpassed the consensus estimate of $33.72 billion by approximately 52.73%.
PSX’s integrated refining, midstream, chemicals, marketing and renewable fuels platform provides cash-flow diversity and commercial flexibility. High refinery utilization, wider margins and disciplined costs support earnings recovery. Midstream expansion and chemical projects broaden PSX’s future earnings capacity.
Portfolio reshaping strengthens PSX’s network, while rapid debt reduction and cash generation support dividends and repurchases. Refining profits underline the value of operational execution, though they remain exposed to volatile fuel spreads. PSX’s integrated asset base, infrastructure pipeline and flexible balance sheet support shareholder returns across changing markets.
Phillips 66 has an expected revenue and earnings growth rate of 22.3% and more than 100%, respectively, for the current year. The Zacks Consensus Estimate for the current year’s earnings has improved 5.5% over the last seven days.
Valero Energy Corp.
Valero Energy reported third-quarter 2026 adjusted earnings of $23.90 per share, up 553% from $3.66 a year ago. This beat the Zacks Consensus Estimate of $21.28 per share. Revenues climbed 43.3% year over year to $46.10 billion from $32.17 billion, also surpassing the Zacks Consensus Estimate by 23.29%.
VLO’s strong performance reflects its refining scale, feedstock flexibility, export access and shareholder returns. Limited spare refining capacity and low fuel inventories support product margins across VLO’s refineries.
Complex Gulf Coast assets can process discounted heavy crude and reach export markets. VLO’s St. Charles optimization project should raise output of higher-value products and improve the asset mix. Renewable diesel and ethanol provide earnings diversity, supported by fuel credit economics and production incentives.
Valero Energy has an expected revenue and earnings growth rate of 29.1% and more than 100%, respectively, for the current year. The Zacks Consensus Estimate for the current year’s earnings has improved 1.1% over the last seven days.
HF Sinclair Corp.
HF Sinclair came up with quarterly adjusted earnings of $11.75 per share, beating the Zacks Consensus Estimate of $8.17 per share. This compares to earnings of $2.44 per share a year ago. Total revenues of $10.86 billion for the reported quarter surpassed the Zacks Consensus Estimate by 45.68%. This compares to year-ago revenues of $7.25 billion.
DINO has been benefiting from favorable refining fundamentals, a flexible regional asset base and projects that can improve margin capture through the cycle. Tight product supply and low inventories are supporting gasoline and distillate economics, while the El Dorado vacuum furnace and Go-West initiatives should expand DINO’s feedstock and logistics flexibility.
Renewables provide another earnings stream for DINO as higher credit values, tax benefits and volumes support profitability. The planned Lubricants & Specialties separation could sharpen DINO’s strategic focus and lower capital intensity, while retirement of the Mississauga refining assets may reduce exposure to volatile base oil cracks.
HF Sinclair has an expected revenue and earnings growth rate of 31.7% and more than 100%, respectively, for the current year. The Zacks Consensus Estimate for the current year’s earnings has improved 9.7% over the last seven days.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Valero Energy Corporation (VLO): Free Stock Analysis Report
Phillips 66 (PSX): Free Stock Analysis Report
HF Sinclair Corporation (DINO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).