

Primo Brands Corporation PRMB is slated to report third-quarter 2026 results on Nov. 5, before market open. The company is likely to report increases in its top and bottom lines when it posts the quarterly results.
For revenues, the consensus mark is pegged at $1.8 billion, implying a rise of 2.6% in the year-ago quarter. The Zacks Consensus Estimate for the company’s earnings is pegged at 42 cents per share, which reflects a decline of 2.4% from the year-ago quarter’s figure. The consensus mark has dipped a penny in the past seven days.
In the last reported quarter, the company delivered a negative earnings surprise of 8.8%. Its earnings beat the Zacks Consensus Estimate by 7.7%, on average, in the trailing four quarters.
Key Factors to Influence PRMB’s Q3 Results
Primo Brands is likely to have benefited from sustained momentum across its retail bottled water business in the third quarter. Continued consumer demand for its regional spring water, purified water and premium brands may have supported sales growth. The company's efforts to expand retail distribution, strengthen in-store visibility and improve shelf placement could have further boosted performance. Its presence across grocery, mass merchandise, club and away-from-home channels may have provided additional support. Moreover, the growing popularity of premium water brands, including Saratoga and Mountain Valley, alongside increased distribution and brand-building efforts, is likely to have strengthened its competitive position and supported a favorable product mix.
Primo Brands’ direct delivery business is also likely to have supported third-quarter performance, benefiting from ongoing efforts to improve service quality and customer satisfaction. Initiatives focused on improving delivery reliability, simplifying billing processes, expanding payment options and resolving customer concerns more efficiently may have helped strengthen customer retention. Improving service levels and declining customer cancellations could have supported customer relationships and encouraged new customer additions. Additionally, the company's focus on acquiring higher-quality customers, disciplined pricing and improving revenue retention is likely to have contributed to a more stable business environment. These initiatives may have helped sustain the positive momentum witnessed in the preceding quarter.
Primo Brands' emphasis on operational efficiency, productivity and disciplined revenue growth management is likely to have supported its third-quarter performance. The company's simplified leadership structure may have enabled faster decision-making and better coordination across its direct delivery and supply chain operations. Continued efforts to optimize delivery routes, improve manufacturing and distribution efficiency, and strengthen supply chain execution could have supported operating leverage. Meanwhile, targeted pricing actions across selected products and channels, alongside a greater focus on product mix and promotional effectiveness, may have helped protect margins. PRMB's ongoing investments in brand development and operational capabilities could have further reinforced its growth prospects.
However, Primo Brands' third-quarter performance may have faced pressure from elevated transportation and commodity costs. Management highlighted a tighter freight market and higher spot rates, which could have increased distribution expenses and weighed on margins. Although the company has been expanding its private fleet and implementing cost-control measures, these initiatives may not have fully offset inflationary pressures. Additionally, the direct delivery business continued to face volume challenges stemming from a smaller customer base, despite improving sales trends. Ongoing investments in customer service, technology and operational capabilities may also have limited near-term margin expansion. These factors, coupled with continued uncertainty surrounding input costs, could have partially offset the benefits of stronger retail demand and improving operational execution.
What the Zacks Model Unveils for PRMB
Our proven model does not predict an earnings beat for Primo Brands this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. However, that’s not the case here.
Primo Brands currently has an Earnings ESP of -3.59% and a Zacks Rank of 5 (Strong Sell). You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Valuation Picture
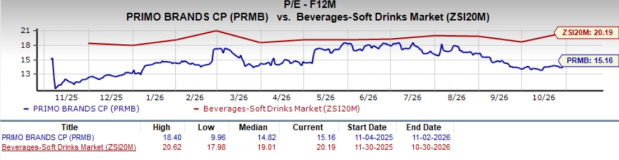
Primo Brands has a forward 12-month price-to-earnings ratio of 15.16X, lower than the Beverages - Soft drinks industry’s average of 20.19X. The stock is trading slightly above its median of 14.82X.
Image Source: Zacks Investment Research
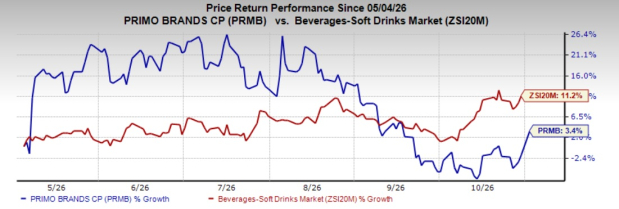
The recent market movements show that PRMB’s shares have gained 3.4% in the past six months compared with the industry's 11.2% growth.
Image Source: Zacks Investment Research
Stocks With the Favorable Combination
Here are some companies that, according to our model, have the right combination of elements to beat on earnings this reporting cycle.
Helen of Troy HELE currently has an Earnings ESP of +6.68% and a Zacks Rank of 3. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Helen of Troy’s upcoming quarterly revenues is pegged at $499.8 million. The figure indicates a 2.5% decrease from the prior-year quarter. The Zacks Consensus Estimate for Helen of Troy’s quarterly earnings per share is pegged at $2, suggesting a 16.7% rise from the year-ago period figure. HELE delivered a trailing four-quarter earnings surprise of 207.7%, on average.
General Mills, Inc. GIS has an Earnings ESP of +0.26% and currently carries a Zacks Rank of 3. The Zacks Consensus Estimate for second-quarter fiscal 2027 earnings per share is pegged at 96 cents, implying a 12.7% year-over-year decline.
The Zacks Consensus Estimate for quarterly revenues is pegged at $4.7 billion, which indicates a decrease of 2.8% from the figure reported in the prior-year quarter. GIS has a trailing four-quarter earnings surprise of 3.6%, on average.
Sysco Corporation SYY currently has an Earnings ESP of +2.58% and a Zacks Rank of 3. The Zacks Consensus Estimate for first-quarter fiscal 2027 earnings per share is pegged at $1.17, implying a 1.7% year-over-year increase.
The Zacks Consensus Estimate for quarterly revenues is pegged at $22.2 billion, which indicates an increase of 4.9% from the figure reported in the prior-year quarter. SYY has a trailing four-quarter earnings surprise of 1%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Primo Brands Corporation (PRMB): Free Stock Analysis Report
General Mills, Inc. (GIS): Free Stock Analysis Report
Sysco Corporation (SYY): Free Stock Analysis Report
Helen of Troy Limited (HELE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).