

Olin Corporation OLN logged earnings (as reported) of 13 cents per share for the third quarter of 2026, down 64.9% from 37 cents in the year-ago quarter.
Barring one-time items, third-quarter adjusted earnings were 14 cents per share, beating the Zacks Consensus Estimate of 10 cents by 40%.
Revenues rose 2% year over year to $1.75 billion but missed the consensus estimate of $1.795 billion by 2.7%. Higher Epoxy and Winchester sales supported growth, while Chlor Alkali Products and Vinyls remained under pressure. Adjusted EBITDA declined 13.9% year over year to $191.4 million.
Olin Corporation Price, Consensus and EPS Surprise
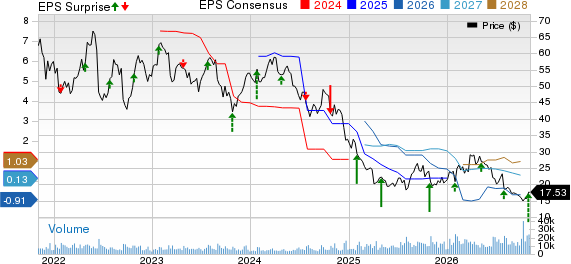
Olin Corporation price-consensus-eps-surprise-chart | Olin Corporation Quote
Olin's Operating Income Falls Amid Cost Pressures
Olin's operating income declined 28.5% year over year to $59.2 million from $82.8 million. Cost of goods sold increased to $1.58 billion from $1.53 billion, while selling and administrative expenses were $98.4 million compared with $98.1 million in the prior-year quarter.
Third-quarter results included $13.7 million in acquisition-related costs associated with the proposed Huntsman merger and $1.7 million in restructuring charges. Depreciation and amortization expenses were $114.4 million compared with $133.8 million a year ago.
OLN's Segmental Review
Chlor Alkali Products and Vinyls sales were $850.8 million in the third quarter, down 7.9% year over year from $924 million. The decline primarily reflected lower trading volumes associated with Blue Water Alliance and reduced vinyl chloride monomer (VCM) volumes, partly offset by higher pricing. The Blue Water Alliance joint venture concluded operations at the end of 2025.
Segment earnings fell to $71.3 million from $127.6 million a year ago. Operating issues at the Freeport, TX, VCM facility reduced earnings by $32.1 million through increased costs and lost sales. Higher caustic soda and ethylene dichloride pricing provided some relief. Results also included a $5 million pretax benefit, primarily related to clean hydrogen production tax credits, compared with $32 million in the prior-year quarter.
Epoxy segment sales increased 17.9% year over year to $412.2 million from $349.6 million, driven by higher volumes and improved pricing. The segment benefited from volume growth despite persistent demand weakness in Europe.
Segment earnings improved to $0.6 million from a year-ago loss of $32.2 million, reflecting higher volumes and lower operating costs. Product margins remained comparable with the prior-year period as improved selling prices offset elevated raw material costs, primarily benzene and propylene. Structural cost reductions also supported the business's profitability improvement.
Winchester segment sales rose 10.3% year over year to $484.7 million from $439.6 million. Growth was primarily driven by higher commercial ammunition sales, with the business maintaining consistent year-over-year commercial volume growth through the quarter.
Segment earnings jumped 75.1% to $33.8 million from $19.3 million a year ago. Higher commercial ammunition pricing and volumes supported profitability, partly offset by increased raw material costs, particularly commodity metals. The company implemented pricing actions to counter rising metals and other input costs.
OLN's Liquidity and Debt Position
Olin ended the third quarter with cash and cash equivalents of $214.8 million, up from $167.6 million at the end of 2025. Net debt stood at approximately $2.8 billion, with a net debt-to-adjusted EBITDA ratio of 5.2 times. Available liquidity totaled approximately $1.3 billion, including the undrawn portion of its revolving credit facility.
Net cash provided by operating activities was $69.7 million during the first nine months of 2026, compared with $153 million a year ago. Capital expenditures declined to $106.6 million from $163.5 million. Dividends paid totaled $68.3 million during the period, while no common stock repurchases and retirements were recorded.
Olin's Q4 Outlook Reflects Seasonal Headwinds
For the fourth quarter of 2026, Olin expects adjusted EBITDA between $80 million and $100 million. The outlook reflects normal seasonality, elevated year-end customer destocking in Chemicals, higher feedstock costs, continued pressure from subsidized Asian exports and significant planned maintenance turnarounds.
Management confirmed that normal operations had been restored at its VCM assets and reiterated its focus on disciplined market participation, structural cost reductions under the Beyond250 program and cash generation. The company continues to prioritize margins over volumes amid volatile export markets.
Olin also expects its proposed all-stock merger of equals with Huntsman Corporation to close in the first quarter of 2027, subject to customary closing conditions.
OLN’s Price Performance
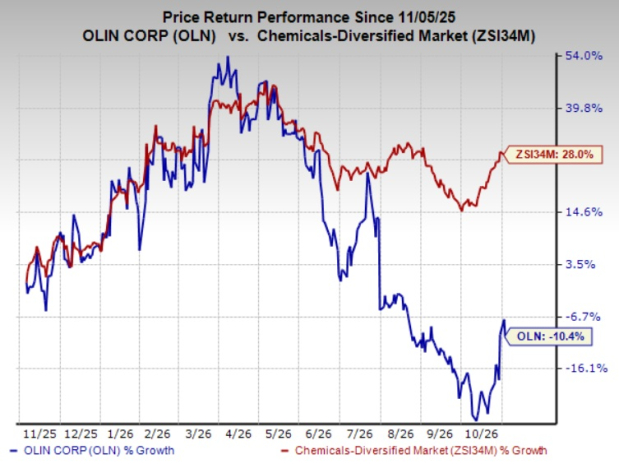
OLN’s shares have declined 10.4% over a year compared with the 28% growth recorded by the Zacks Chemicals Diversified industry.
Image Source: Zacks Investment Research
OLN’s Zacks Rank & Key Picks
OLN currently carries a Zacks Rank #3 (Hold).
Better-ranked stocks in the basic materials space include Green Plains Inc. GPRE, Perimeter Solutions, Inc. PRM and GrowGeneration Corp. GRWG.
Green Plains is scheduled to report third-quarter results on Nov. 5. The Zacks Consensus Estimate for GPRE’s third-quarter earnings is pegged at 76 cents. GPRE sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Perimeter Solutions is slated to report third-quarter results on Nov. 5. The Zacks Consensus Estimate for earnings is pegged at 95 cents per share. PRM carries a Zacks Rank #2 (Buy) at present.
GrowGeneration is slated to report third-quarter results on Nov. 10. The consensus estimate for GRWG’s earnings is pegged at a penny per share. GRWG currently carries a Zacks Rank #2.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Olin Corporation (OLN): Free Stock Analysis Report
Green Plains, Inc. (GPRE): Free Stock Analysis Report
GrowGeneration Corp. (GRWG): Free Stock Analysis Report
Perimeter Solutions, SA (PRM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).