

WEX Inc. WEX reported strong third-quarter 2026 results, with adjusted earnings of $6.13 per share, beating the Zacks Consensus Estimate of $5.67 by 8.1%. The bottom line increased 33.6% year over year, benefiting from higher fuel prices, improved organic growth and operating leverage.
WEX Inc. Price, Consensus and EPS Surprise
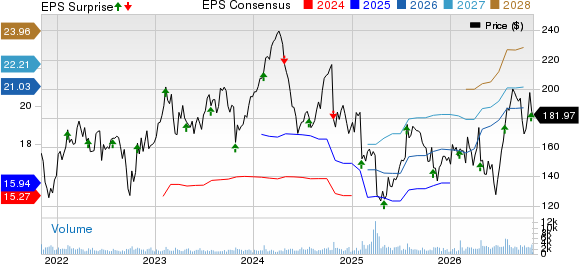
WEX Inc. price-consensus-eps-surprise-chart | WEX Inc. Quote
Revenues rose 12.8% year over year to $780.1 million, surpassing the consensus estimate of $757 million by 3.1%. Growth was supported by Mobility segment strength, with payment processing transactions increasing 1.7%. Total payment volume across all segments grew 18.5% to $78.5 billion.
However, investors were not impressed with the earnings beat and WEX’s fourth-quarter revenue guidance for 2026, as the stock declined 3.5% since the company released results on Oct. 28.
The company’s fourth-quarter revenue guidance is projected between $760 million and $780 million, with the midpoint of $770 million below the Zacks Consensus Estimate of $770.44 million for the same period.
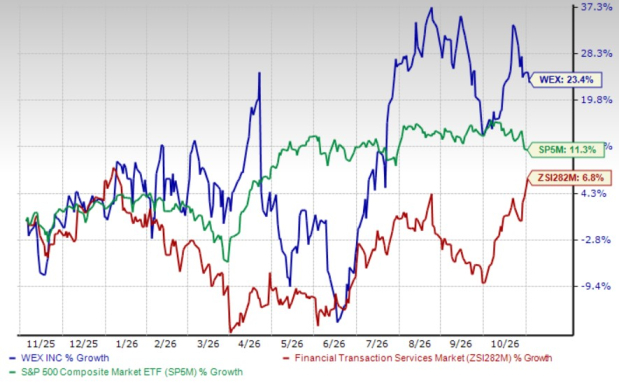
Over the past year, WEX's shares rose 23.4%, outperforming the industry's 6.8% and the Zacks S&P 500 composite’s 11.3% growth.
Image Source: Zacks Investment Research
WEX's Revenue Growth Benefits From Higher Fuel Prices
Higher fuel prices contributed $57.3 million to quarterly revenues, while favorable foreign exchange movements added $0.8 million. Excluding these impacts, organic revenue growth was 4.4%, reflecting improvements in pricing and business execution.
Payment processing revenues increased to $344.8 million from $301.7 million a year ago. Account servicing revenues reached $186.7 million, up from $185.3 million in the third quarter of 2025. Finance fee revenues rose to $115.9 million from $83.2 million a year ago, while other revenues increased to $132.7 million from $121.5 million.
WEX's Mobility Segment Delivers Robust Growth
Mobility segment revenues increased 20.6% year over year to $435.1 million. Organic growth was 4.4%, accelerating from 3.1% in the first half of 2026. Pricing initiatives, new business wins and improved local fleet performance supported the results.
Payment processing transactions increased to 142.3 million from 140 million a year ago. Payment processing gallons totaled 3.63 billion, declining 0.2% year over year but increasing 1% sequentially. The average domestic fuel price climbed to $4.85 per gallon from $3.38.
The segment's adjusted operating income margin expanded to 46.9% from 40.7% a year ago. Credit losses were 11.7 basis points of spend volume compared with 12.1 basis points in the prior-year quarter.
WEX's Benefits Business Sees Higher HSA Assets
Benefits segment revenues rose 4.8% year over year to $207.6 million. Average Software-as-a-Service accounts increased 2.8% to 22.1 million, reflecting growth despite difficult comparisons related to a large account addition last year and previously disclosed account closures.
Average health savings account (HSA) custodial cash assets climbed 11.2% to $5.3 billion. HSA accounts grew 7.7%, while custodial investment revenues increased at the same rate.
The segment's adjusted operating income margin contracted to 42.2% from 43.8% a year ago. Management continues investing in platform modernization and AI-powered claims processing to strengthen its competitive position.
WEX's Corporate Payments Gains From Direct AP
Corporate Payments segment revenues increased 3.5% year over year to $137.4 million. Purchase volume rose 6.3% year over year to $24.6 billion, while total processed volume increased 10.1% to $47.6 billion.
Direct accounts payable (AP) volume grew 24%, exceeding management's earlier expectations for mid-teens growth. Total travel volume increased 13.1%, supported by customer activity and new online travel agency relationships.
The segment's adjusted operating income margin improved to 49.9% from 48% a year ago. However, delayed implementations and travel disruptions associated with the Middle East conflict constrained revenue growth.
WEX's Profitability Improves, Cash Generation Solid
GAAP operating income increased to $238.8 million from $183.6 million a year ago. Operating margin expanded to 30.6% from 26.5%. Adjusted operating income grew 21.6% to $332.5 million, with the corresponding margin improving 310 basis points to 42.6%.
Adjusted net income increased to $211.9 million from $159.7 million. Total cost of services rose to $287.4 million from $274.3 million, while general and administrative expenses increased to $100.7 million from $92 million.
Adjusted free cash flow reached $234.3 million compared with $166.2 million a year ago. WEX repurchased approximately $200 million of shares during the quarter. Its leverage ratio declined sequentially to 2.7 times from 2.9 times.
WEX Raises 2026 Outlook on Strong Performance
For the fourth quarter of 2026, adjusted earnings are projected in the range of $5.67-$5.87 per share. The Zacks Consensus Estimate for earnings is pegged at $4.94 per share for the same period.
For full-year 2026, management raised its revenue guidance to $2.97-$2.99 billion from $2.86-$2.90 billion. The Zacks Consensus Estimate for revenues is pegged at $2.95 billion for the same period.
Adjusted earnings guidance increased to $21.28-$21.48 per share from $19.68-$20.08. The Zacks Consensus Estimate is pegged at $20.04 per share for the same period.
The upward revision reflects stronger-than-anticipated fuel prices and third-quarter outperformance. Management expects Mobility organic revenue growth of 3-5% for the year, while Corporate Payments revenue growth is projected at 4-6%, reflecting travel-related headwinds.
WEX currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Recent Earnings Snapshots
Waste Connections, Inc. WCN reported impressive third-quarter 2026 results. WCN’s adjusted earnings of $1.58 per share outpaced the consensus mark by 4% and rose 9.7% from the year-ago quarter. WCN’s total revenues of $2.64 billion surpassed the consensus mark by 1.2% and increased 7.3% year over year.
Rollins, Inc. ROL posted unimpressive third-quarter 2026 results. ROL’s adjusted earnings of 34 cents per share missed the Zacks Consensus Estimate by 2.9% and declined 2.9% year over year. Total revenues of $1.09 billion fell short of the consensus estimate by 3.2% but increased 6.2% from the year-ago quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
WEX Inc. (WEX): Free Stock Analysis Report
Waste Connections, Inc. (WCN): Free Stock Analysis Report
Rollins, Inc. (ROL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).