

Western Digital Corporation WDC continues to demonstrate strong gross margin expansion, supported by favorable pricing, growing demand for high-capacity hard disk drives (HDDs) and disciplined operational execution. The company remains confident about sustaining this momentum as it advances its technology roadmap and transitions customers toward higher-capacity products.
In the first quarter of fiscal 2027, Western Digital's non-GAAP gross margin expanded 1,420 basis points year over year to 58.1%, with incremental gross margins exceeding 80%. This improvement primarily reflected a favorable product mix, strong pricing across its portfolio and operational efficiencies. Notably, the year-over-year increase in average selling price (ASP) per terabyte accelerated to 28% from the high teens in the preceding quarter.
Management identified three key factors supporting sustained gross margin expansion. First, a favorable pricing environment continues to benefit the company, with contractual price increases under long-term agreements and stronger spot pricing amid tight supply conditions. Pricing improvements are also evident across its client and consumer businesses.
Second, the transition toward higher-capacity drives is strengthening profitability, as these products command higher ASPs per drive. Third, increasing areal density allows Western Digital to ship more exabytes without incurring the additional fixed costs associated with expanding unit production capacity.
Western Digital expects second-quarter fiscal 2027 gross margin between 60% and 61%, indicating further sequential improvement. Revenues are projected at $5.1 billion, plus or minus $100 million, implying 69% year-over-year growth at the midpoint.
The company also anticipates further ASP-per-terabyte increases over the next three to four quarters, although management acknowledged that pricing growth could eventually moderate. Meanwhile, higher DRAM and NAND input costs remain a near-term challenge, potentially limiting cost-per-terabyte reductions below the company's long-term target of approximately 10% annually.
Nevertheless, continued pricing strength, higher-capacity product adoption and improving areal density position Western Digital to sustain gross margin expansion. Management remains optimistic about longer-term profitability, supported by robust storage demand and ongoing technology transitions.
Taking a Look at WDC’s Competitors
Seagate Technology Holdings plc’s STX fiscal first quarter was led by sustained demand and pricing strength amid robust sales. Its HAMR-based Mozaic roadmap supports higher drive capacities, while long-term supply agreements provide visibility into demand and pricing. Disciplined production and favorable product mix are lifting margins and cash generation. Debt reduction also creates room for higher shareholder returns. Management anticipates fiscal second-quarter revenues of $4.8 billion (+/- $100 million), up 70% year over year at midpoint. Non-GAAP earnings are expected to be $9.2 per share (+/- 20 cents). It expects non-GAAP operating expenses to remain steady at around $300 million, while operating margin is projected to expand toward the mid-50% range based on the midpoint of revenue guidance.
NetApp NTAP is benefiting from rising enterprise spending on AI-ready storage, supported by strong all-flash, Public Cloud and Keystone demand. Its unified platform and strategic acquisitions are expanding AI and cloud migration opportunities. Raised fiscal 2027 guidance underscores growth momentum and operating leverage. For second-quarter fiscal 2027, NetApp projects revenues of $2.03-$2.18 billion, non-GAAP gross margin of 67-68%, operating margin of 30.9-31.9% and earnings of $2.54-$2.64 per share. For fiscal 2027, revenues are forecast at $7.98-$8.23 billion, with earnings of $9.73-$10.03 per share. The revenue midpoint implies 17% growth, while earnings midpoint indicates 22% growth.
WDC Price Performance, Valuation and Estimates
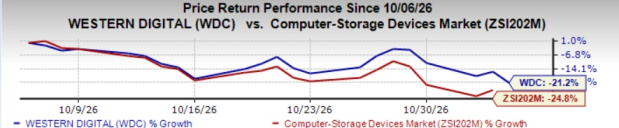
In the past month, shares have lost 21.2% compared with the Zacks Computer-Storage Devices industry’s decline of 24.8%.
Image Source: Zacks Investment Research
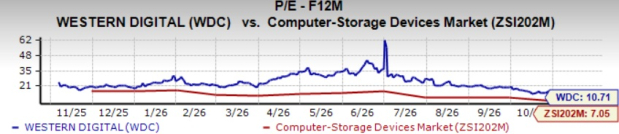
WDC’s shares are trading at a forward price/earnings multiple of 10.71X, higher than the industry’s 7.05X.
Image Source: Zacks Investment Research
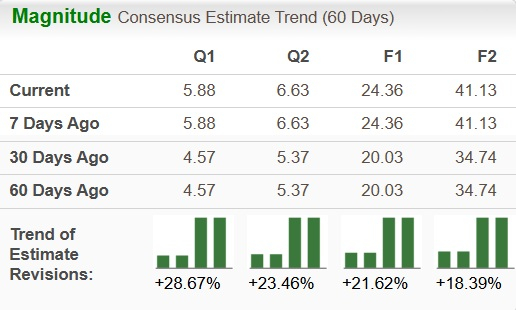
The Zacks Consensus Estimate for WDC’s earnings for fiscal 2026 has been revised up 21.6% to $24.36 over the past 60 days.
Image Source: Zacks Investment Research
Currently, Western Digital sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Western Digital Corporation (WDC): Free Stock Analysis Report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).