

Tapestry, Inc. TPR is benefiting from Coach’s ability to attract new shoppers while growing sales among existing customers. Product innovation, a compelling value proposition and disciplined promotions are supporting the brand’s performance. Management credits its consistent brand experience across channels with strengthening customer acquisition and average unit retail, while identifying further opportunities in established and underpenetrated markets.
Coach’s first-quarter fiscal 2027 revenues increased 16% year over year to $1.661 billion, rising 16% at constant currency. Handbag average unit retail grew at a low-double-digit rate, while units advanced low single digits. Coach reported higher average unit retail and strong unit growth within its $200-$500 handbag range, alongside a planned unit decline below $200 as it reduced promotional exposure.
Coach welcomed more than 2.1 million new consumers during the quarter, led by Gen Z, while existing customers drove strong sales growth. The New York, Tabby and Teri collections supported Gen Z acquisition. Footwear revenues increased more than 20%, driven by the Margot family and sneakers, adding to growth beyond the brand’s core leather goods business.
Geographic strength was broad-based. Coach’s constant-currency revenues rose 41% in Greater China, 27% in Europe and 7% in North America, while Japan returned to growth with a 5% increase. Management also reported that Expressive Luxury stores exceeded investment targets, generating higher traffic and longer visits, particularly among Gen Z consumers. The rollout is planned to reach approximately 80% of traffic by fiscal 2030.
Management expects Coach to deliver high-single-digit revenue growth and an operating margin of approximately 36% in fiscal 2027. Product innovation, consistent execution across channels and investment in stores support that outlook. Although sustaining customer demand remains essential, Coach’s combination of rising average selling prices, unit growth and geographic breadth strengthens the case for progress toward management’s $10 billion brand ambition.
TPR’s Price Performance, Valuation & Estimates
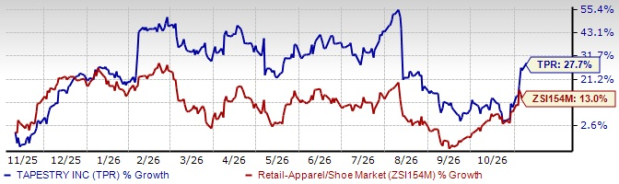
Shares of Tapestry have risen 27.7% over the past year compared with the industry’s 13% growth.
Image Source: Zacks Investment Research
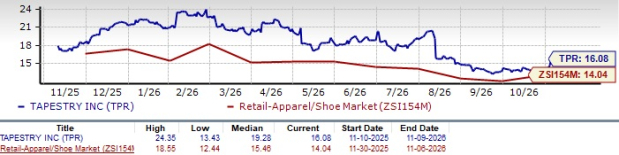
From a valuation standpoint, TPR trades at a forward price-to-earnings ratio of 16.08, up from the industry’s average of 14.04. It has a Value Score of A.
Image Source: Zacks Investment Research
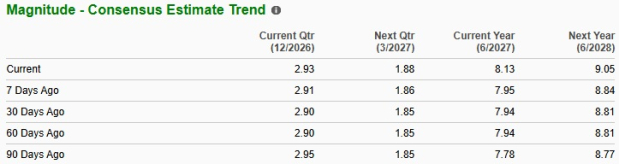
The Zacks Consensus Estimate for Tapestry’s fiscal 2027 earnings implies year-over-year growth of 15.3%, whereas the same for fiscal 2028 indicates an uptick of 11.3%. Earnings estimates for fiscal 2027 and 2028 have increased by 18 cents and 21 cents, respectively, over the past seven days.
Image Source: Zacks Investment Research
TPR’s Zacks Rank & Other Key Picks
Tapestry currently carries a Zacks Rank #2 (Buy).
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Abercrombie & Fitch Co. ANF operates as a specialty retailer of premium, high-quality casual apparel for men, women, and kids. The company carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Abercrombie & Fitch’s current fiscal-year earnings and sales suggests growth of 15.8% and 6.5%, respectively, from the year-ago actuals. ANF delivered a trailing four-quarter average earnings surprise of 13.6%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 12.6%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Tapestry, Inc. (TPR): Free Stock Analysis Report
Abercrombie & Fitch Company (ANF): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).