

Principal Financial Group, Inc. PFG appears reasonably positioned to sustain growth in its Retirement and Income Solutions (RIS) business, supported by healthy retirement savings contributions, expanding institutional relationships and demand for pension risk transfer solutions. However, moderating interest rates, market volatility, competitive pressures and margin challenges could affect its earnings growth.
In the third quarter of 2026, recurring deposits increased 8% year over year to $13 billion. Both the number of participants contributing to retirement plans and average deferrals per participant grew 4%, reflecting healthy customer engagement. PFG also benefited from strong demand in the small and mid-sized business retirement market, where transfer deposits increased 21% and recurring deposits rose 7%. Additionally, pension risk transfer sales reached $0.9 billion, while retirement roll-ins totaled $1.8 billion, highlighting opportunities to capture additional retirement assets.
However, RIS pre-tax operating earnings declined 4% year over year to $297.8 million, while net revenues increased just 1% to $757.3 million. The operating margin contracted to 39.3% from 41.3% a year ago, reflecting pressure from lower variable investment income and prior-year actuarial assumption changes. Excluding significant variances, pre-tax operating earnings increased 5% to $330.3 million, indicating better underlying momentum.
Going forward, PFG's broad retirement product portfolio, recordkeeping capabilities and established distribution network should support customer retention and new business generation. Nevertheless, interest rate fluctuations, pressure on investment spreads, and intense competition could constrain profitability. Overall, RIS appears capable of sustaining measured growth, but stronger revenue conversion, margin stability and disciplined expense management will be essential to drive consistent earnings expansion.
What About Its Peers?
MetLife, Inc. MET faces a similar challenge in sustaining retirement business growth while managing earnings volatility. In third-quarter 2026, its RIS segment reported adjusted earnings of $413 million, down 6% year over year, reflecting unfavorable actuarial assumption adjustments. However, excluding notable items, earnings increased 12% to $478 million, driven by stronger investment margins and volume growth. Adjusted revenues excluding pension risk transfers increased 33%, highlighting healthy underlying business momentum. Sustaining this growth will depend on investment spreads and continued retirement demand.
Voya Financial, Inc. VOYA is witnessing steady growth in its Retirement business, although margin pressure remains a concern. In third-quarter 2026, pre-tax adjusted operating earnings increased 2% year over year to $266 million, supported by sustained commercial momentum and operating efficiencies. Trailing 12-month net revenues grew 6%, while total client assets increased 12% to $878 billion. However, the operating margin declined to 37.8% from 39.8%, partly due to lower alternative investment income. Sustaining growth will depend on fee-based revenue expansion and margin stability.
PFG’s Price Performance
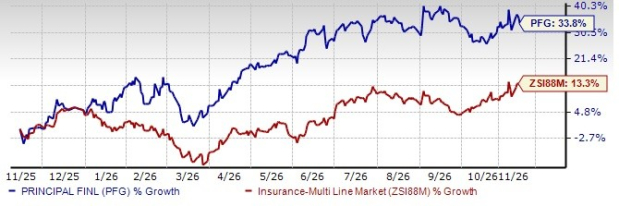
Shares of PFG have gained 33.8% in the past year, outperforming the industry.
Image Source: Zacks Investment Research
PFG’s Undervaluation
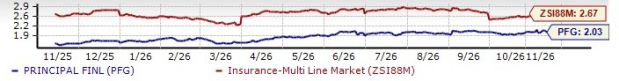
The stock is undervalued compared with its industry. Its forward price-to-book value of 2.03X is lower than the industry average of 2.67X. It carries a Value Score of B.
Image Source: Zacks Investment Research
Estimate Movement for PFG
The Zacks Consensus Estimate for PFG’s fourth-quarter 2026 EPS has moved down 2.8% in the past 60 days. The same for full-year 2026 and 2027 EPS has moved down 3.9% and 2.6%, respectively, in the past 30 days.
Image Source: Zacks Investment Research
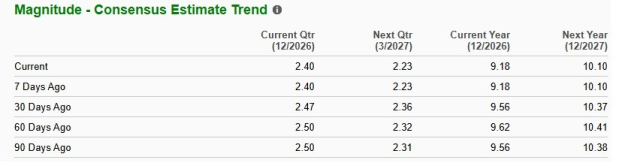
The consensus estimate for PFG’s 2026 and 2027 EPS and revenues indicates a year-over-year increase.
PFG stock currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Principal Financial Group, Inc. (PFG): Free Stock Analysis Report
MetLife, Inc. (MET): Free Stock Analysis Report
Voya Financial, Inc. (VOYA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).