

Coeur Mining CDE offers investors a larger operating base, stronger liquidity and substantial projected cash generation after two major acquisitions. Those gains have improved its growth profile, but the expanded portfolio has also increased the importance of mine execution and disciplined capital deployment.
The investment case is therefore mixed. Growth and balance-sheet flexibility are improving, while weaker earnings-estimate revisions, uneven operating performance and a valuation above Coeur’s historical median argue against treating the stock as an obvious bargain.
Coeur’s Acquisitions Have Transformed Its Growth Profile
The acquisitions of SilverCrest Metals and New Gold added Las Chispas, New Afton and Rainy River to Coeur’s portfolio. The Canadian mines alone generated $354.7 million of third-quarter revenues, showing how materially the transaction has changed the company’s revenue mix.
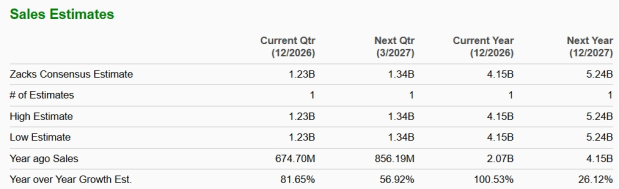
Projected sales growth for 2027 is 100.5%, reflecting the enlarged business. Las Chispas also contributed $72.6 million of third-quarter free cash flow, giving Coeur another source of internally generated funding as the Canadian assets ramp up.
Image Source: Zacks Investment Research
CDE’s Cash Position Creates Greater Flexibility
Coeur ended the third quarter with $1.17 billion of cash and cash equivalents against $701.7 million of total debt, including finance leases. Cash exceeded total debt by $471.1 million in September compared with $213.1 million at year-end 2025.
That liquidity gives the company room to fund mine investment while returning capital. Coeur expanded its share-repurchase authorization to $750 million and had completed $231 million of purchases under the enhanced program through the latest earnings release. Agnico Eagle Mines Limited AEM offers a peer reference point, reporting $3.42 billion of net cash as of Sept. 30 while continuing to fund growth projects and shareholder returns.
Coeur Still Needs to Prove the Bigger Portfolio Works
The larger asset base has not eliminated operating risk. Coeur reduced 2026 gold guidance for both New Afton and Rainy River after slower underground ramp-ups. Rochester also continues to face slower-than-expected silver recoveries from newly placed ore.
Reinvestment requirements remain substantial. Capital expenditures are projected at $520-$605 million for 2026, while trailing 12-month return on invested capital stands at 6.1%, below the 13.5% industry median. Pan American Silver Corp. PAAS recently showed similar operating sensitivity, generating $377 million of attributable third-quarter free cash flow while also lowering its 2026 gold-production outlook.
CDE’s Valuation Is Not an Obvious Bargain
Coeur trades at 2.63X forward 12-month sales, below the Zacks sub-industry multiple of 3.48X and the S&P 500’s 4.29X. That relative discount could appeal to investors looking for exposure to the company’s expanded production base.
Image Source: Zacks Investment Research
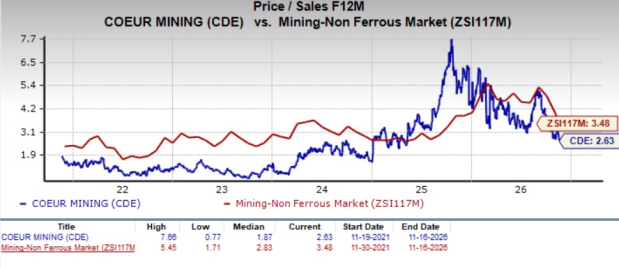
The stock is not clearly cheap against its own history, however. Its five-year median forward sales multiple is 1.87X, while the current multiple also sits slightly above the Zacks Basic Materials sector’s 2.53X. The Value Score of C is consistent with that mixed valuation picture.
Coeur’s Ratings Point to a Wait-and-See Setup
The central question is whether acquisition-driven growth can translate into durable earnings and cash returns without continued execution setbacks. Coeur has the liquidity and asset base to support that outcome, but Canadian ramp-ups, Rochester recoveries and higher mine costs still need to improve.
CDE currently carries a Zacks Rank #4 (Sell), along with a VGM Score of C, Value Score of C, Growth Score of B and Momentum Score of F.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Growth Score reflects relatively favorable growth characteristics, but Style Scores complement the Zacks Rank rather than override it. With the current-year earnings estimate down 15.6% over the past four weeks and momentum weak, the present signal supports waiting for a better setup rather than viewing the stock as a clear buy.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Coeur Mining, Inc. (CDE): Free Stock Analysis Report
Agnico Eagle Mines Limited (AEM): Free Stock Analysis Report
Pan American Silver Corp. (PAAS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).