

Agriscience business Corteva (CTVA) is gearing up to spin off its seed operating segment as an independently traded public company, Vylor, trading under the “VYLR” ticker. Shareholders have already approved the separation, and they are expected to receive one Vylor common share for each Corteva common share they hold. VYLR is set to begin trading on Oct. 1. The company is holding an Investor Day webcast on Sept. 15.
Corteva believes this spinoff will give both companies more flexibility. However, analysts have questioned whether it weakens the entities. Meanwhile, CEO Luke Kissam has highlighted a pipeline Corteva values at $11 billion through 2040 and its plan to introduce 12 products over the next decade. Contrarily, competition from generic products remains, and President Donald Trump's administration is exploring whether consolidation among agricultural suppliers has driven up input costs.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Corteva Stock
Corteva is a global agricultural science company headquartered in Indianapolis, Indiana, that develops and supplies seed, crop protection, and digital agronomy solutions. Operating through two core segments, Seed and Crop Protection, the company delivers advanced germplasm, trait technologies, herbicides, insecticides, fungicides, and nitrogen management products to farmers worldwide.
Its portfolio, which includes the Pioneer and Brevant seed brands, helps growers improve yields, manage pests and diseases, and enhance crop resilience across diverse climates. With a presence in several countries, Corteva combines research, manufacturing, and commercial operations to support productivity and sustainability in modern agriculture. The company has a market capitalization of $55.07 billion.
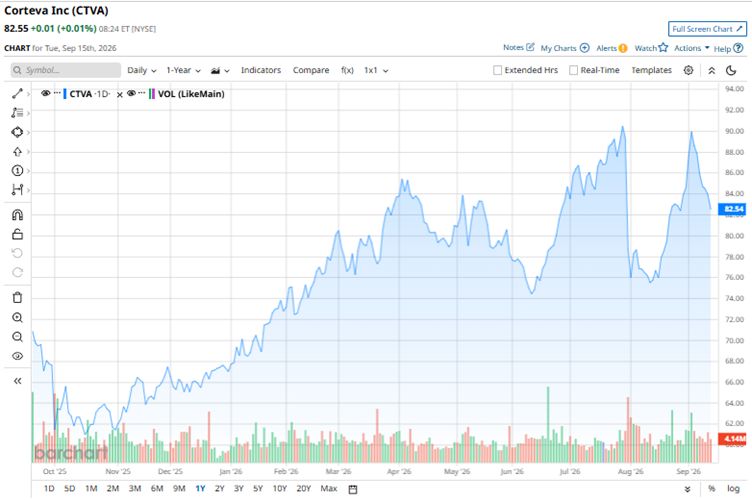
As investors reward stronger execution, resilient seed demand, and a clearer path to value creation, Corteva’s stock has gained 20% over the past 52 weeks and 25% year-to-date. It reached a 52-week high of $90.97 on July 29 but is down 9.3% from that level.
 www.barchart.com
On a forward-adjusted basis, Corteva’s stock is trading at a price-to-earnings (non-GAAP) ratio of 21.95x, higher than the industry average of 15.38x.
Corteva Reported Lifted Full-Year Outlook After Q2 Results
In the second quarter, Corteva’s net sales fell 1% year-over-year (YOY) to $6.38 billion. As both crop protection and seed volume declined 2% and 3%, respectively, total volume also fell 3%, although price mix increased 1% due to higher seed pricing. Non-GAAP operating EBITDA increased by 4% YOY to $2.26 billion, while non-GAAP operating EPS grew 5% to $2.30.
Stabilizing farm economics are supporting farmer investment in solutions that enhance yields and profitability. Given these market dynamics and its strong first-half execution, the company raised its full-year 2026 guidance, projecting operating EBITDA of $4.10 billion to $4.30 billion, up 9% at the midpoint, and operating earnings per share (EPS) of $3.60 to $3.80 per share, up 11% at the midpoint.
While Wall Street analysts expect a 78.3% drop in the bottom line to a $0.41 loss per share for the current quarter, EPS is projected to grow 11.4% to $3.72 for the current year, followed by another 6.5% growth to $3.96 next year.
What Do Analysts Think About Corteva’s Stock?
This month, analysts at KeyBanc initiated coverage of Corteva’s stock with a “Sector Weight” rating and a $92 price target. KeyBanc analysts view Corteva as a highest-quality name with a longstanding track record in the seed business and a cyclical recovery in crop chemicals. However, the firm’s analysts have also shown skepticism about the rationale behind the upcoming spinoff. The firm also indicated the spinoff could provide a more attractive entry point.
Last month, UBS analysts cut the price target on Corteva’s stock from $89 to $85, while maintaining a “Neutral” rating. Analyst Joshua Spector said the company is better positioned heading into its investor days and planned spinoff after the post-earnings pullback. UBS said Corteva’s 2029 outlook implies EBITDA of $4.80 billion to $5.50 billion, roughly $950 million higher than 2026 estimates.
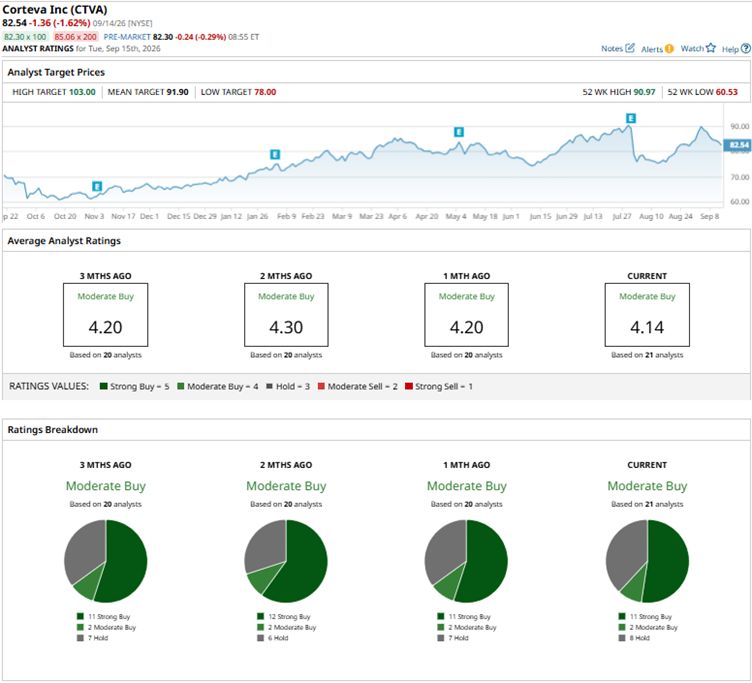
Corteva remains a popular name on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating overall. Of the 21 analysts rating the stock, 11 analysts have given it a “Strong Buy” rating, two analysts have given a “Moderate Buy,” and eight analysts are taking the middle-of-the-road approach with a “Hold” rating. The consensus price target of $91.90 represents an 11.3% upside from current levels. Moreover, the Street-high price target of $103 indicates 24.8% potential upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Corteva Stock Fans, Mark Your Calendars for September 15 CrowdStrike, Other Cybersecurity Stocks Surge as AI Debate Takes Center Stage Unusual Out-of-the-Money Put Option Volume in Amazon Shows Investors Bullish on AMZN Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock