

ON Semiconductor (ON), commonly known as Onsemi, will report its third-quarter fiscal 2026 results on Nov. 2 after the market closes. Ahead of the report, the company has also landed a lucrative revised acquisition deal.
In June, Onsemi struck a deal to acquire fabless chip firm Synaptics (SYNA) for $7 billion in an all-stock transaction, which caused ON stock to drop sharply as investors feared dilution. However, in October, the company amended the deal to a $123-per-share cash deal for an aggregate value of approximately $5.7 billion. In addition to a lower price tag, the all-cash deal means no dilution for ON stock shareholders. Meanwhile, the company is also reportedly eyeing a purchase of startup chip firm Ferric for approximately $1 billion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Therefore, all eyes will be on Onsemi’s cash position with the upcoming quarterly report.
About ON Semiconductor Stock
ON Semiconductor is a global semiconductor company headquartered in Scottsdale, Arizona. The company makes chips that manage power and sense things such as images, helping cars, factories, data centers, and everyday electronics use energy more safely and efficiently. The company designs, manufactures, and sells products worldwide, with a strong focus on automotive and industrial markets. Onsemi has a market capitalization of $27.9 billion.
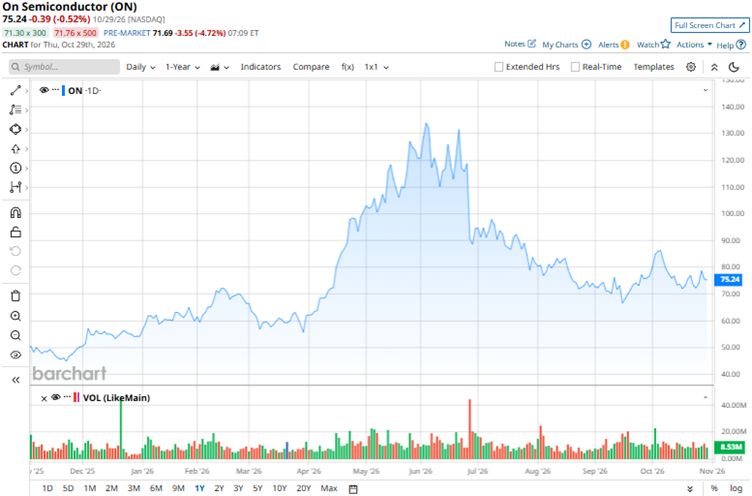
ON stock is up 41% over the past 52 weeks, mainly because investors see improving growth and a stronger position in artificial intelligence (AI) power, electric vehicles (EVs), and energy storage. However, ON stock is down 29% over the past six months because investors have become more worried about near-term demand in the company's biggest markets, especially cars and industrial equipment. The stock reached a 52-week high of $134.92 on June 3 but is currently down 47% from that level.
 www.barchart.com
Meanwhile, the forward price-to-earnings (P/E) ratio of 23.4 times is slightly higher than the industry average of 22.1 times.
Q2 Earnings Beat Expectations as AI and Auto Demand Lifted Revenue Growth
For the second quarter, Onsemi’s revenue increased 9% year-over-year (YOY) to $1.6 billion, surpassing the $1.59 billion that Wall Street analysts had expected.
Growth in the Power Solutions Group (PSG) led the results, with the segment’s top line growing 19% YOY to $829 million. PSG contains the company’s AI data-center and high-voltage power businesses, which saw the strongest demand.
Automotive demand also raised Intelligent Sensing Group (ISG) revenue by 7% YOY to $228.8 million. This segment contains the company's CMOS image sensors, SPAD, and SiPM technologies used heavily in automotive safety and industrial applications.
Onsemi’s non-GAAP operating margin grew from 17.3% to 20.8% over the same period. Non-GAAP EPS also grew 40% YOY to $0.74, topping the $0.72 analysts expected. Importantly, free cash flow margin expanded from about 7% to 27%, giving the company more money to reinvest in its business and carry out acquisitions.
Wall Street is robustly optimistic about Onsemi’s future earnings. Analysts expect EPS to climb 40% YOY to $0.88 in Q3. For fiscal 2026, EPS is projected to surge 37% YOY to $3.21, followed by 40% YOY growth to $4.50 in fiscal 2027.
What Do Analysts Think About ON Semiconductor Stock?
In October, B. Riley lowered its price target for ON stock from $127 to $105 while keeping a “Buy” rating. Following Texas Instruments' (TXN) report, analysts see a sustained analog semiconductor upcycle into 2027. However, analysts also believe recent sector share price gains have compressed valuation multiples.
Susquehanna analyst Christopher Rolland also recently lowered his price target from $150 to $120 while keeping a “Positive” rating on the stock. Susquehanna expects “modest upside” from the company's Q3 results and Q4 guidance, with AI trends and a broader semiconductor upcycle driving improvement.
Last month, StoneX also initiated coverage of Onsemi with a “Buy” rating and a $110 price target. StoneX believes the company is positioned to benefit from broadening chip cycle strength.
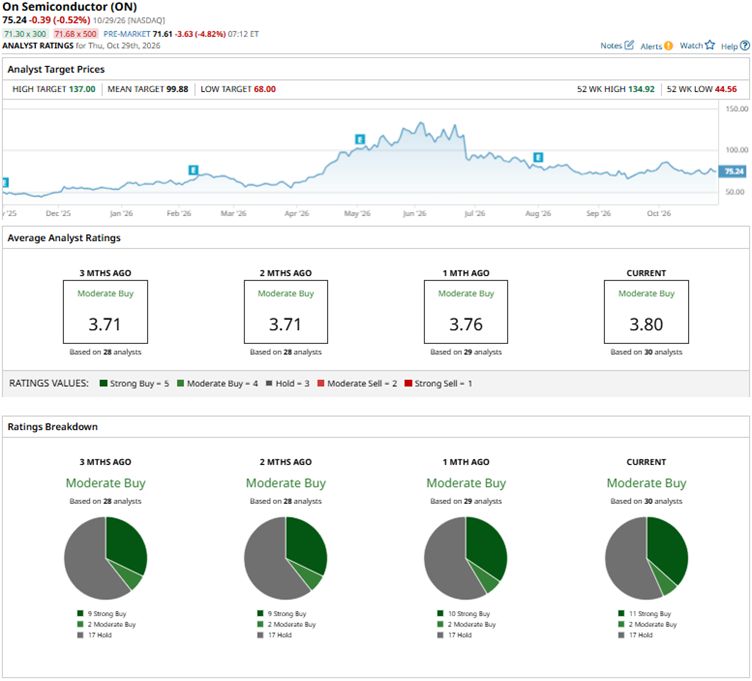
Overall, Onsemi is gaining praise on Wall Street, with analysts awarding ON stock a consensus “Moderate Buy” rating. Of the 30 analysts covering the stock, 11 have a “Strong Buy” rating, two analysts have a “Moderate Buy,” and 17 have a “Hold” rating. The average price target of $99.88 represents potential upside of 39% from current levels, while the Street-high price target of $137 implies 91% potential upside from here.
 www.barchart.com
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear ON Semiconductor Stock Fans, Mark Your Calendars for November 2 Why It's Time to Buy the Pullback in Alphabet Stock Dear Roku Stock Fans, Mark Your Calendars for November 2 Why Now Is Not the Time to Load Up on Netflix Stock