

The race to power the artificial intelligence (AI) boom is opening the door to a new generation of energy technologies, and Fervo Energy (FRVO) is emerging as one of Wall Street’s most closely watched geothermal plays. The company is developing enhanced geothermal systems (EGS) that use oil-and-gas drilling techniques, including horizontal drilling and hydraulic stimulation, to unlock geothermal resources beyond the limited locations suitable for conventional geothermal power.
The bullish case received a major boost when Morgan Stanley initiated coverage of Fervo with an “Overweight” rating and a $23 price target, arguing that geothermal could be entering its own “shale revolution.” The firm sees rapidly improving drilling technology, falling costs, and surging electricity demand from AI data centers creating the conditions for geothermal to evolve into a scalable source of 24/7, low-carbon power.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
The firm believes falling drilling costs and improving performance could put the technology on a learning curve similar to early shale development, potentially unlocking more than $300 billion of investment by 2030.
With Fervo’s Cape Station already entering commercial operation and a substantial pipeline of contracted power projects, Wall Street is increasingly betting that the company could become a major beneficiary if enhanced geothermal technology scales as expected.
About Fervo Stock
Fervo Energy is a Houston, Texas-based geothermal energy developer focused on commercializing EGS to provide reliable, 24/7, low-carbon electricity. The company uses technologies adapted from the oil and gas industry, including horizontal drilling, hydraulic fracturing, and advanced subsurface monitoring, to engineer geothermal reservoirs and unlock heat from underground rock.
Fervo has its flagship Cape Station project in Utah, which has moved toward utility-scale commercialization, with more than 1 gigawatt of binding PPAs signed across its portfolio. Fervo currently has a market cap of approximately $2.7 billion.
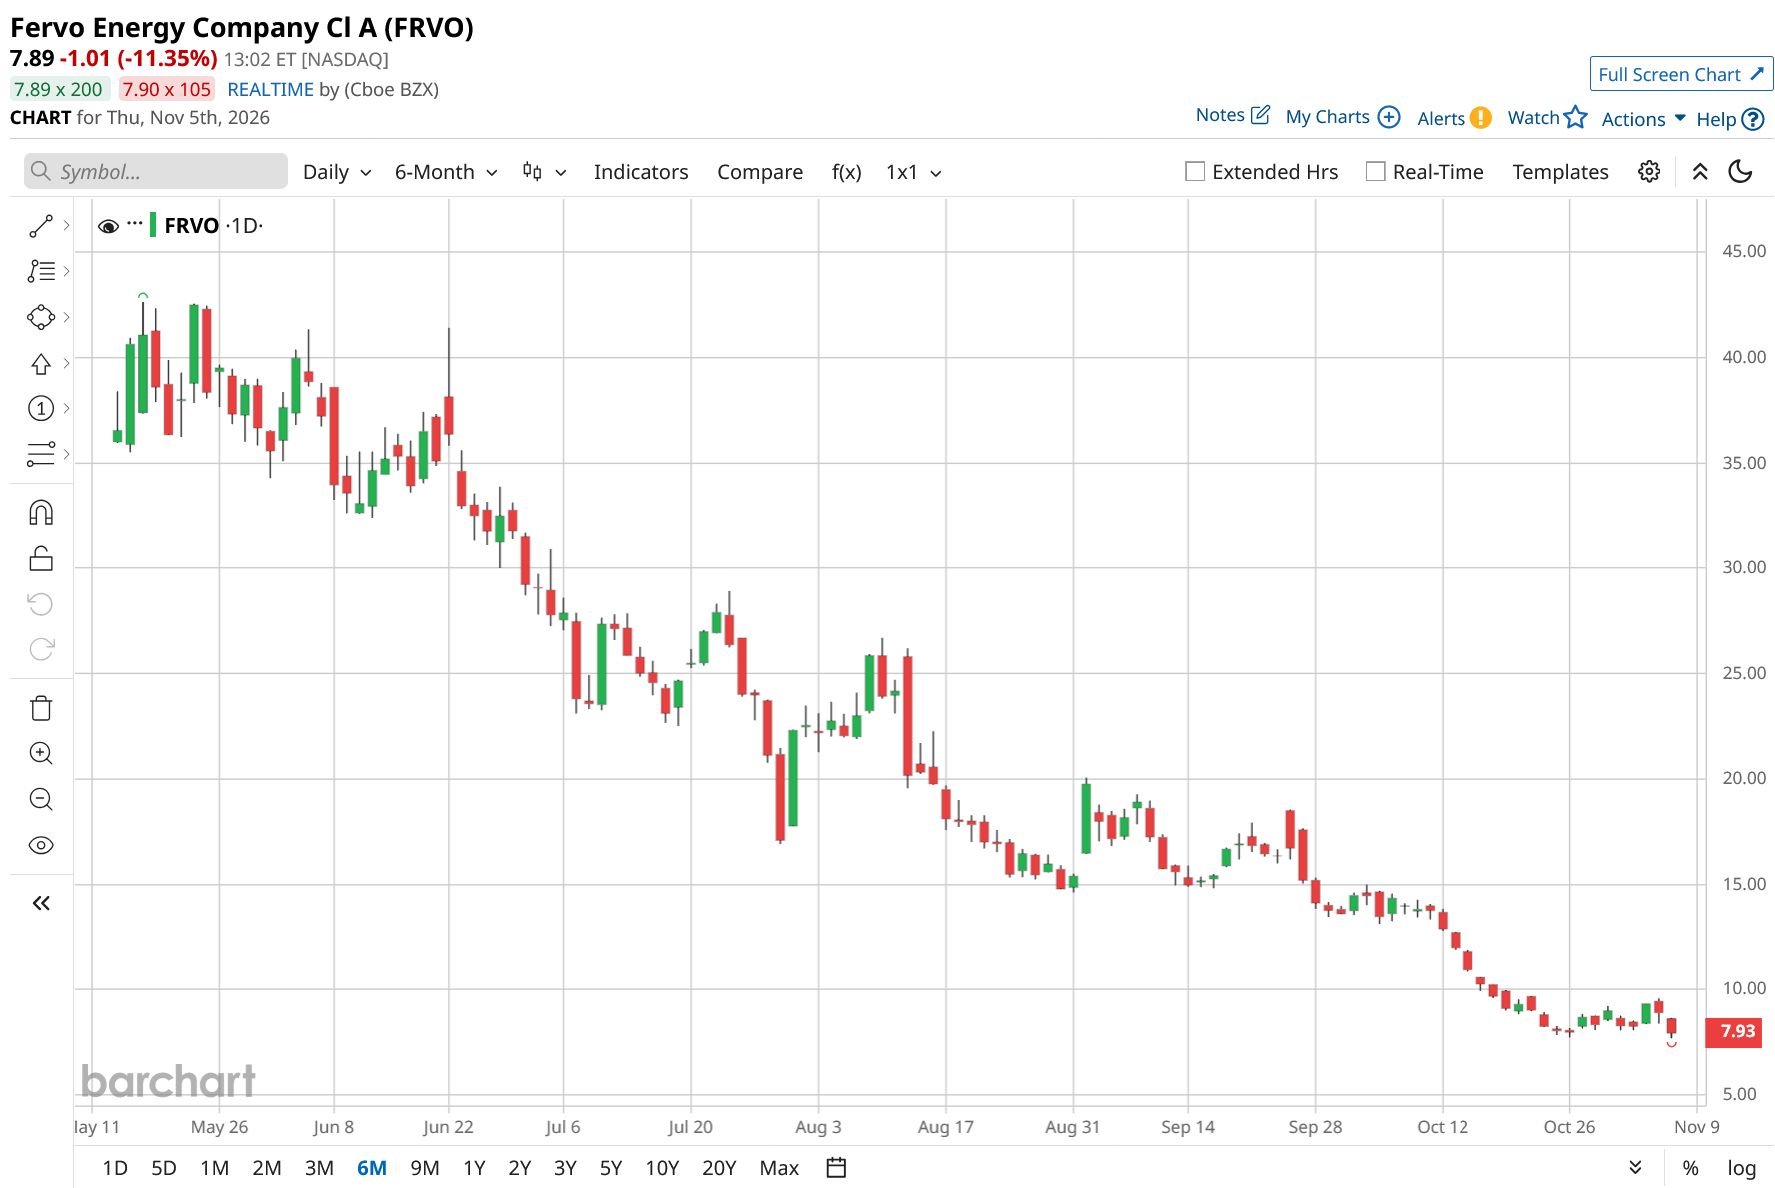
FRVO stock has experienced a sharp pullback since its IPO, reflecting the high volatility and execution risks associated with the emerging EGS market. The stock has slumped 41% over the past month and roughly 64% over the past three months, with the decline coming as investors reassessed the valuation of the newly public geothermal developer following its strong post-IPO run.
Fervo went public on May 13, 2026, pricing its IPO at $27 per share and initially surged 35.3% on its first trading day, but the early enthusiasm proved difficult to sustain.
More recently, however, FRVO has, at times, shown signs of renewed buying interest. The stock gained a healthy 13% on Nov. 3, helped by a 7.9% jump on Oct. 29, although it has since surrendered those gains with a particularly steep 11% decline on Nov. 5.
The rebound appears to reflect renewed investor interest in the geothermal opportunity, particularly after Morgan Stanley initiated coverage with an “Overweight” rating and a $23 price target, highlighting Fervo as a pure-play beneficiary of the potential “shale revolution” in geothermal energy. Nevertheless, the extreme swings underscore that FRVO stock remains a high-risk, high-reward growth stock.
The stock currently trades at a lofty valuation compared to the sector median at 19,907.18 times sales.
 www.barchart.com
Fervo Is Making Significant Progress
Fervo Energy’s most recent reported quarter is Q2 2026, and the company is scheduled to release its Q3 2026 results before the market opens on Nov. 9.
The company reported its Q2 results on Aug. 12, covering the quarter ended June 30. Revenue was only $113,000, up from zero revenue in Q2 2025, reflecting the company’s pre-commercial stage at the time. The company posted an operating loss of $28.7 million, compared with a $10.3 million loss a year earlier, while net loss widened to $55.9 million from $11.4 million.
Furthermore, Fervo reported a Q2 loss of $0.38 per share, compared with a loss of $1.31 per share in the prior-year quarter. Additionally, for the first six months of 2026, revenue was $174,000 versus zero a year earlier, while net loss widened to $87.7 million from $20.6 million.
The most important takeaway from the quarter, however, was operational rather than financial. Fervo raised its long-term development target to 1.1 gigawatts by 2030, up 100 MW from its previous target, as confidence in its commercial pipeline increased. Plus, Fervo’s Sawtooth 7 well set a company drilling record, reaching nearly 19,500 feet in just 21 days.
Fervo also significantly expanded its development pipeline. More than 50 GW of potential capacity was in the pipeline at quarter-end. About 400 MW was moved into Advanced Development, and another 10.5 GW entered Early Development. The company also planned to begin appraisal drilling in Q4 2026.
Importantly for investors, Fervo entered the second half of 2026 with substantial liquidity following its IPO. The May offering generated approximately $2.2 billion in gross proceeds, while cash and cash equivalents stood at $2.1 billion as of June 30, compared with $461.8 million at year-end 2025. However, capital spending is expected to remain substantial, as Fervo guided for around $850 million and $900 million in capital expenditures in the second half of 2026, primarily for Cape Station construction and broader pipeline development.
Since the Q2 report, Fervo has reached several major milestones that will be particularly important in the upcoming Q3 report. In September, it signed a 396-MW power purchase agreement with Alphabet (GOOG) (GOOGL), while Cape Station achieved First Power on Sept. 24. Moreover, on Oct. 1, Fervo declared the first GeoBlock commercially operational at 33 MW, ahead of schedule, and began generating revenue under its PPA.
Analysts expect Fervo’s loss per share of $0.58 for fiscal 2026 and to improve 10.3% to $0.52 for fiscal 2027. Its loss per share is expected to come in at $0.10 for Q3.
What Do Analysts Expect for FRVO Stock?
In addition to Morgan Stanley remaining bullish, JPMorgan analyst Mark Strouse also reiterated an “Overweight” rating on FRVO stock on Oct. 19 but lowered the price target to $27 from $38. Despite the target cut, the continued “Overweight” rating indicates that JPMorgan remained bullish on Fervo’s longer-term opportunity.
In October, Bernstein maintained an “Outperform” rating and a $47 price target on Fervo Energy.
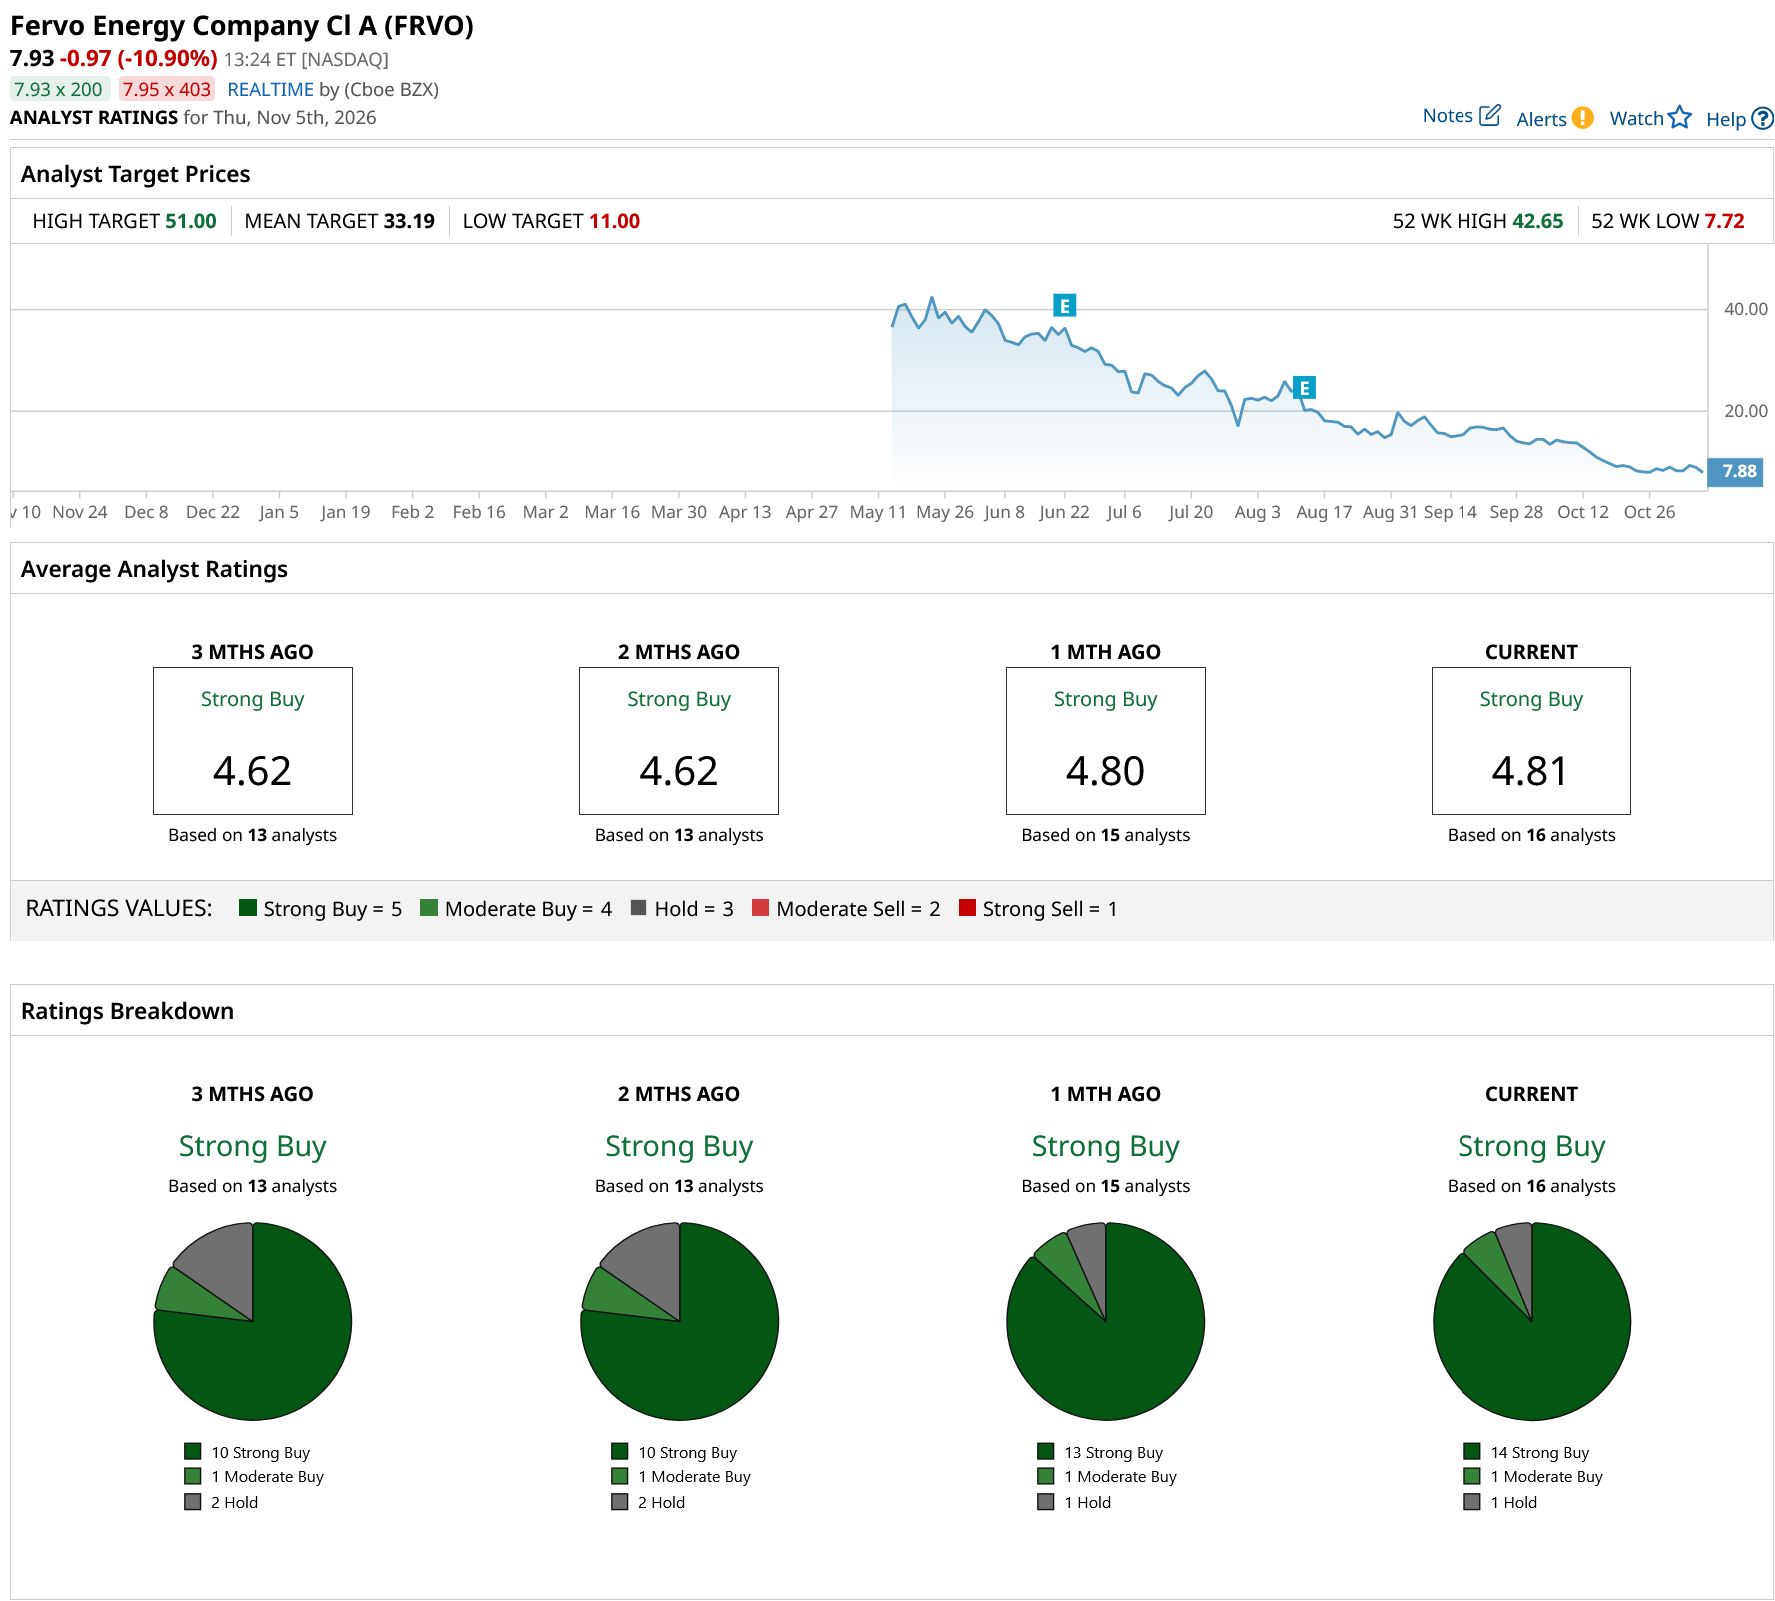
Overall, FRVO stock has a consensus “Strong Buy” rating. Of the 16 analysts covering FRVO, 14 advise a “Strong Buy,” one suggests a “Moderate Buy,” and one analyst gives it a “Hold” rating.
FRVO’s average analyst price target of $33.19 indicates an upside of 316%, while the Street-high target price of $51 suggests that the stock could rally as much as 540%.
 www.barchart.com
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Wall Street Is Betting a ‘Shale Revolution’ Can Make Fervo Stock a Huge Winner Lucid Stock is $3. That Doesn’t Mean It’s Cheap. Follow This 4-Part Total Portfolio Strategy to Prepare for Any Market – Not Just the Bull Market You Want Why AGI’s Fuzzy Definition Matters for Investors Betting on Google, Meta, and Microsoft