

SpaceX (SPCX) has reached orbit with Starship. Now, the challenge is bringing both stages back. Flight 14 launched on Sept. 28 and reached Earth orbit for the first time, deploying 26 next-generation Starlink V3 satellites before a planned splashdown. After 13 earlier test flights, that mission set the stage for an even tougher test.
Flight 15 is targeted for Friday, Nov. 13. SpaceX plans to catch both the Super Heavy booster and the Starship upper stage using the launch tower’s mechanical arms, a first if successful. On the Oct. 20 earnings call, Elon Musk said the flight was expected this month. President Gwynne Shotwell also said SpaceX expects its FAA license to cover both catches.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
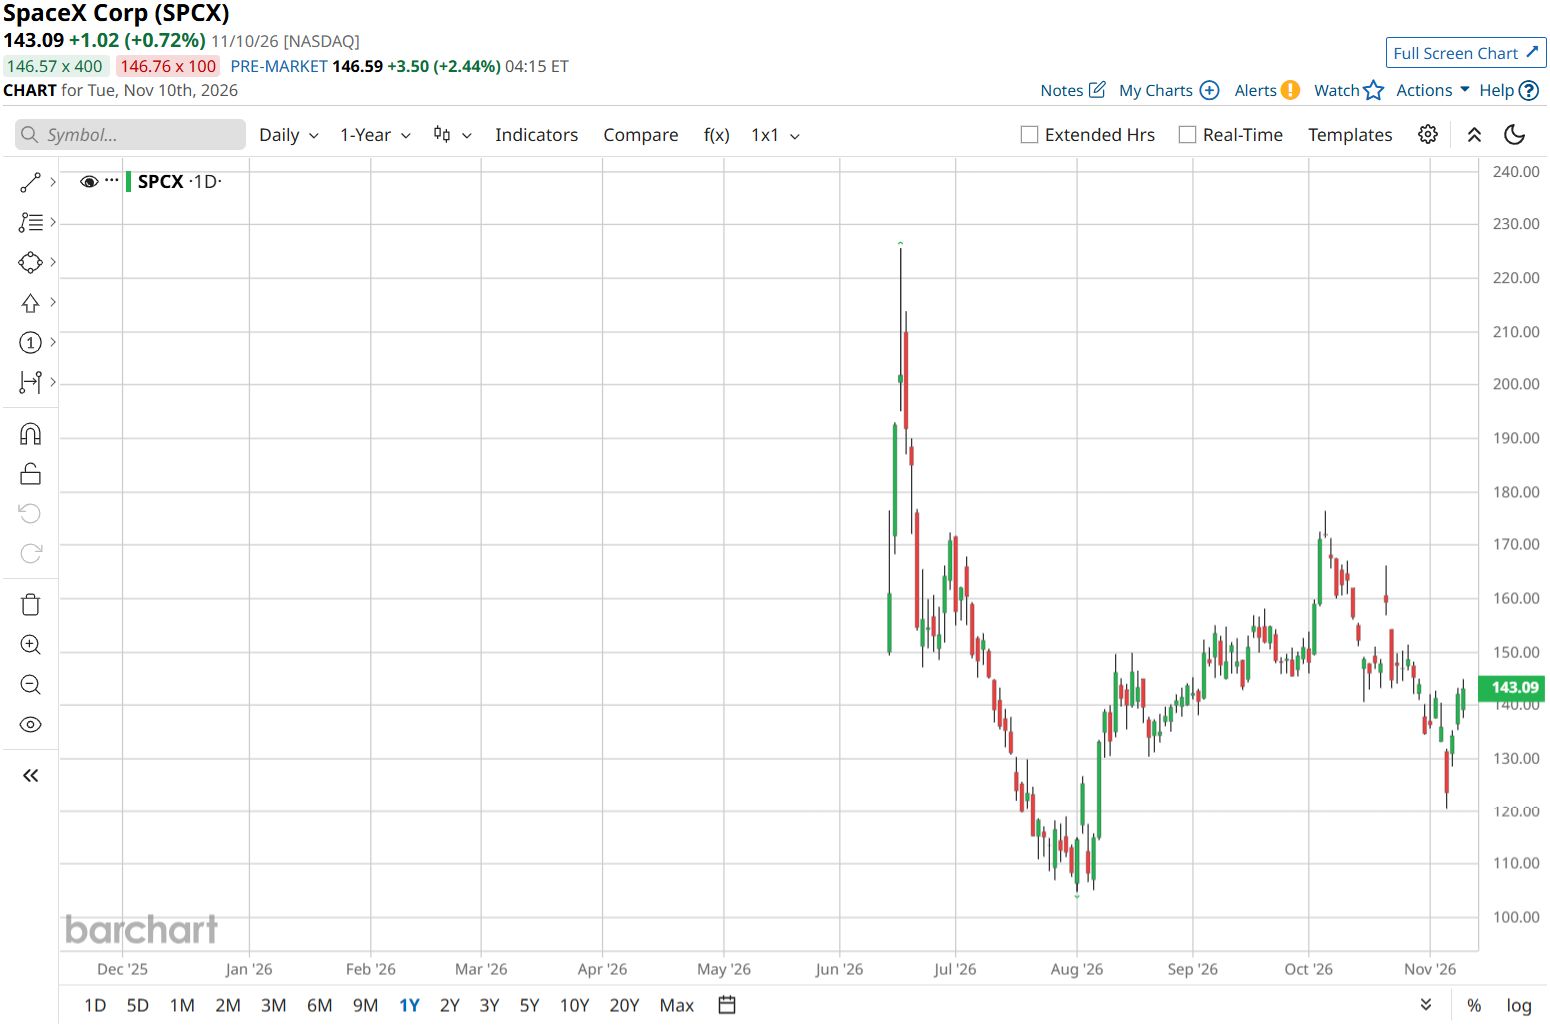
Shareholders could use some good news. SpaceX went public on June 12 at $135 per share and later hit a high of $225.64, but shares have fallen almost 12% over the past month. SpaceX and Tesla (TSLA) also lost about $456 billion in combined market value in the days after the midterm elections. Could a successful double catch on Nov. 13 help SpaceX stock bounce back? Let’s find out.
SpaceX’s Numbers Behind the Mission
Space Exploration Technologies, better known as SpaceX, earns money from rocket launches, Starlink internet services, and AI infrastructure and software. Shares have gained 3.14% over three months but dropped 11.98% over the past month.
 www,barchart.com
Despite that decline, the stock still trades at 723.61x forward earnings, compared with the sector’s 13.35x. At that price, investors are counting on strong growth to continue.
The third-quarter results show why expectations are high. Revenue rose 161% from a year earlier to $14.6 billion, beating Wall Street’s roughly $12.7 billion estimate. Net income came in at $4.4 billion, or $0.35 per diluted share, while adjusted EBITDA reached $8.8 billion. Operating income also improved sharply, turning a $273 million loss into a $2.8 billion profit.
Starlink helped drive those gains. Consumer subscribers reached 13.6 million, up from 12 million in June and 7.2 million a year earlier. Connectivity revenue grew 69% to $5.25 billion, producing $2.37 billion in operating income. Super Intelligence brought in even more revenue, jumping from $813 million to $7.56 billion and becoming the biggest contributor to sales.
That growth comes with a hefty bill. Quarterly capital spending totaled $19.6 billion, including $16.4 billion for Super Intelligence infrastructure, far exceeding adjusted EBITDA. SpaceX ended September with 1.7 gigawatts of installed computing capacity. It also completed its first revenue-generating Starship mission, delivering 26 Starlink V3 satellites and giving the rocket program its first commercial revenue.
The Growth Case for Full Reusability
In June, SpaceX agreed to buy AI coding startup Cursor for $60 billion. Cursor reportedly generates $4 billion in annual recurring revenue, and all 40,000 engineers at NVIDIA (NVDA) use its tools. SpaceX has since added Cursor to new X Subscription bundles, offering Grok, X features, and coding tools across five plans, from free access to a $200-per-month Ultra option.
The company is also expanding into mobile service. In October, SpaceX agreed to buy up to 14 megahertz of paired low-band spectrum in the 800 MHz band from Grain Management for about $8 billion. Those frequencies would help Starlink Mobile provide cellular coverage, including indoors. The FCC has also approved 15,000 next-generation Starlink Mobile satellites designed to connect directly to phones.
To help build the network, Qualcomm (QCOM) announced a multiyear agreement on Nov. 4 to supply Dragonwing radio equipment, baseband units, and software. Deployment of the ground-based 5G network is expected to start in 2027. Qualcomm called it its biggest 5G deal yet.
Meanwhile, NVIDIA is the exclusive technology provider for the planned AI data centers in orbit. The first satellites using its technology are targeted for launch in Q4 2027, making Starship’s reliability important to those plans. NASA has also awarded SpaceX $946 million for three more crewed Dragon missions to the International Space Station. That brings the total Commercial Crew contract value to $5.92 billion through 2030, adding booked work alongside the company’s longer-term projects.
Analyst Views and What Comes Next
SpaceX is expected to report on January 19, 2027. Analysts expect earnings of $0.30 per share for the December 2026 quarter and $0.22 per share for the full fiscal year.
Ahead of Starship Flight 15, Morgan Stanley (MS) analyst Adam Jonas has stayed bullish, reiterating an Overweight rating and a $300 price target. He calls SpaceX “cheap and getting cheaper” because of its expected growth. The company’s enterprise value is roughly 30x its estimated 2028 operating earnings, compared with about 16x for large AI peers. But after factoring in growth, Jonas puts its valuation about 40% below the group’s median.
Jonas also pointed to a possible opportunity among investors who have yet to buy. When he asked about 40 clients who owned SpaceX shares, “not a single hand went up.” That says something about that room, though it does not tell us how institutions as a whole are positioned.
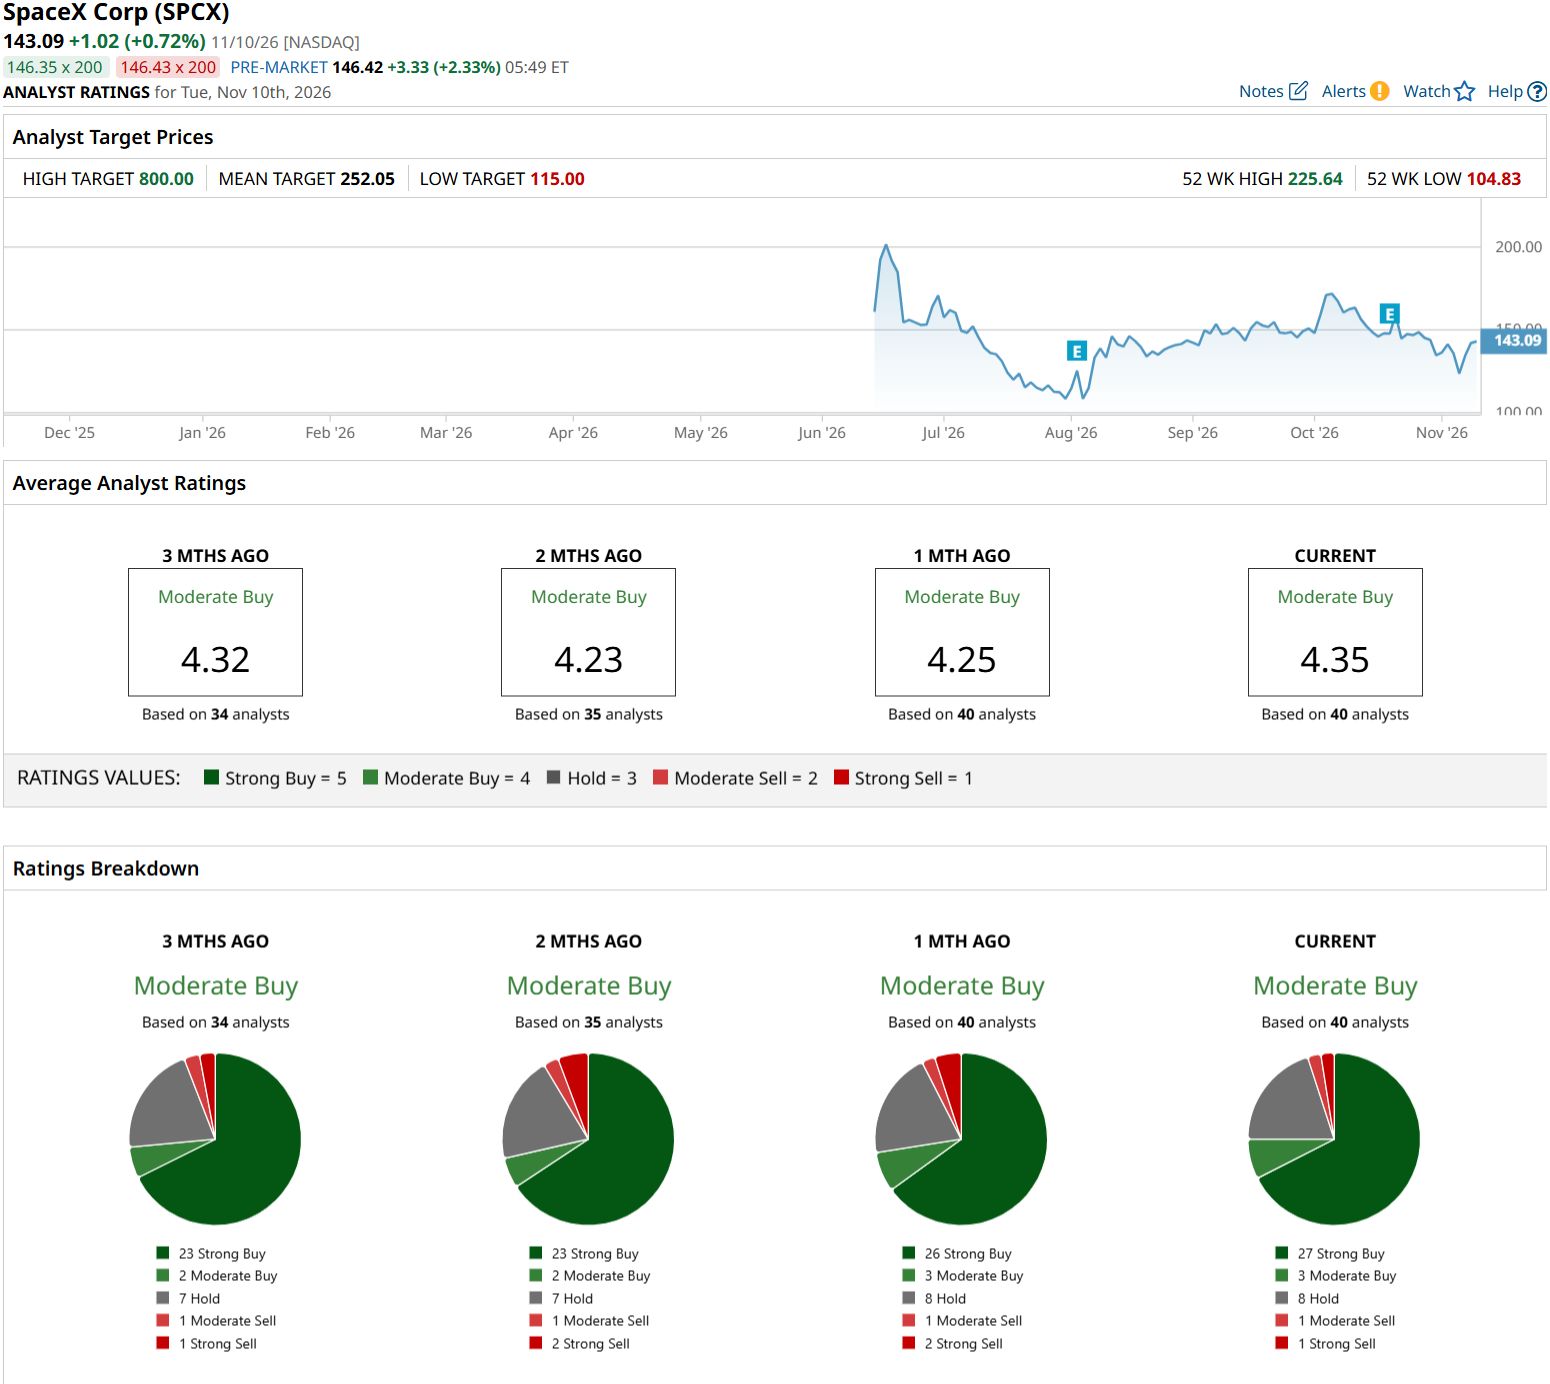
The broader analyst view is positive, too. The consensus across 40 surveyed analysts is “Moderate Buy,” with an average price target of $252.05. That suggests about 76.15% upside from current price levels.
 www.barchart.com
Conclusion
Yes, a successful double catch could give SpaceX stock a much-needed lift by strengthening confidence in Starship’s path toward full reusability. But Nov. 13 remains a target, and even a flawless mission would not erase valuation concerns or the demands of its spending plans. A successful recovery would make a near-term rebound more likely, though a sustained climb would need support from earnings and execution across the business. Mark the calendar, but treat the launch as a potential catalyst, not a guaranteed turning point for the stock.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
2 Bearish Option Ideas To Consider This Thursday As October Revenue Surges, Wall Street Is Still Bullish on Taiwan Semi Stock ANT Stock Alert: Anthropic Is Set for a Trillion-Dollar Debut With Its IPO Nasdaq Futures Slump as Nvidia Crisis Hits AI Trade; U.S. Economic Data and Fed Speak on Tap