

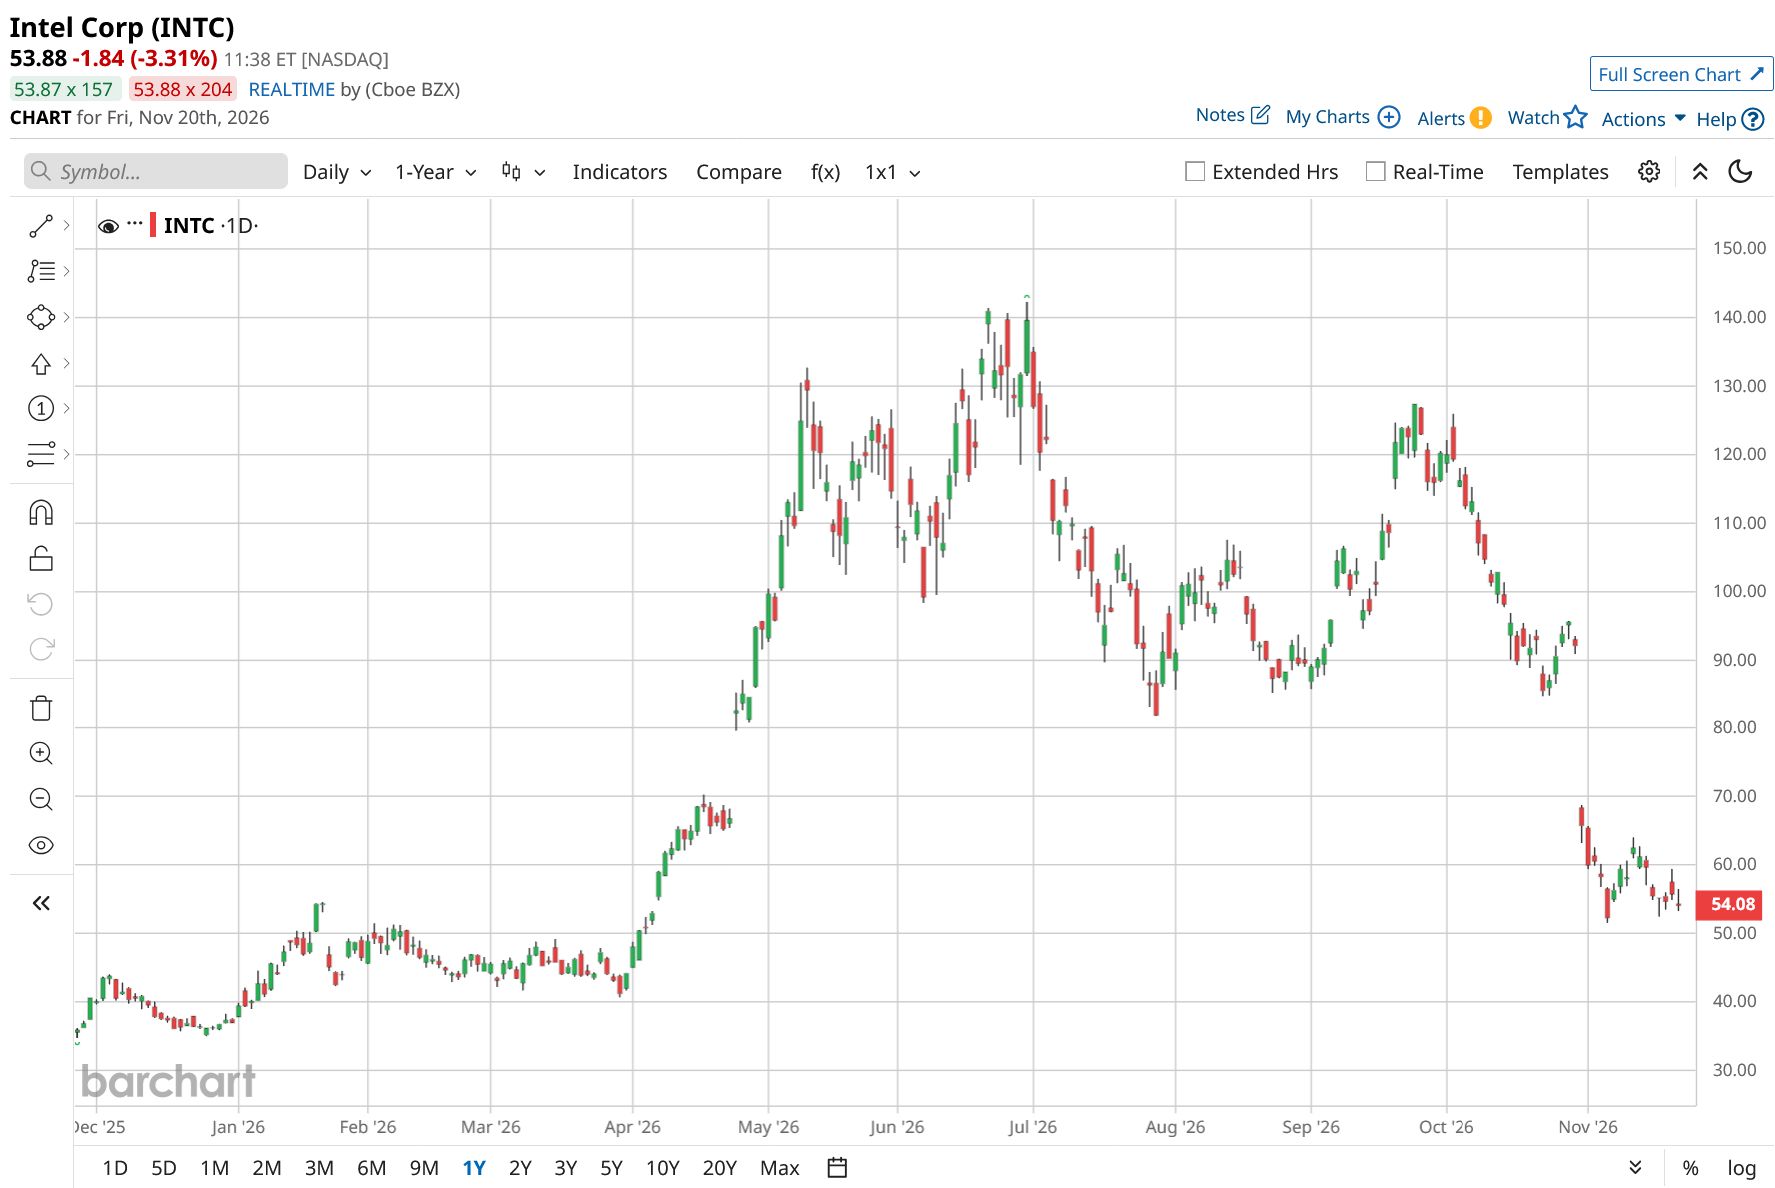
Intel (INTC) has long been a prominent name in the semiconductor industry, supplying processors for personal computers and data centers. Its stock, however, has had a difficult run, losing more than half its value since the end of September.
Sentiment deteriorated further late last month after management warned that quarterly revenue could fall at least $1 billion short of analyst expectations, blaming weaker PC demand and ongoing supply chain disruptions.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Against this backdrop, CEO Lip-Bu Tan delivered a much-needed positive development on Wednesday, Nov. 18, announcing that Intel had secured its first external customer for its 18A process node. The 18A platform sits at the heart of Intel's ambitions to become a serious competitor in advanced semiconductor manufacturing.
Described as a 1.8-nanometer-class process, the technology is designed to support increasingly sophisticated chips for artificial intelligence (AI), high-performance computing, and major cloud infrastructure providers. However, developing advanced technology is only half the challenge.
Intel has committed tens of billions of dollars to expanding and modernizing its manufacturing capabilities. Without third-party customers, the investment could remain heavily dependent on Intel's own chip designs.
Therefore, success in this area could help Intel compete more directly with industry leader Taiwan Semiconductor Manufacturing Company (TSM) for some of the market's most valuable manufacturing contracts.
About Intel Stock
The Santa Clara, California-based Intel Corporation designs, develops, manufactures, and markets processors, graphics chips, and advanced computing solutions. Its portfolio spans CPUs for personal computers and commercial devices, GPUs, server processors, AI accelerators, networking components, and data center technologies.
With a market cap of nearly $290.6 billion, its operations extend beyond chip design, with semiconductor manufacturing, wafer fabrication, autonomous driving technologies, and advanced packaging solutions also part of its business.
On the price-performance front, INTC stock is up 62% over the past 52 weeks and 47% year-to-date (YTD), but the recent slide has taken some shine off those gains. Shares have dropped 41% in a month, as manufacturing delays, tougher competition, and sluggish PC demand continue to test Intel’s turnaround, as its latest earnings made clear.
Valuation adds another layer to the discussion. INTC stock is currently trading at 36.77 times forward adjusted earnings and 4.71 times sales. Both multiples are above industry averages, suggesting the stock commands a premium despite its recent correction.
 www.barchart.com
Surpasses Q3 Earnings
Intel's Q3 FY2026 results, released on Oct. 29, offered plenty of financial positives, although the market reaction was anything but encouraging. Shares initially declined 3.6% on the announcement date before suffering a much steeper 28.6% drop in the following trading session.
Net sales increased 20.9% year-over-year (YoY) to $16.5 billion, extending a notable run of revenue outperformance. For the eighth consecutive quarter, actual revenue exceeded management's expectations. It also topped analysts' estimates of $16.42 billion.
Non-GAAP gross margin expanded to 44.1%, while non-GAAP operating margin climbed to 19.6%. Non-GAAP net income jumped 169.4% from its year-ago level to $2.8 billion, and non-GAAP EPS surged 126.1% YoY to $0.52, surpassing the $0.40 Street estimate.
Much of this strength came from Data Center and AI (DCAI), which emerged as the standout growth engine. Revenue in the division surged 78% YoY to $7.3 billion, supported by stronger demand from hyperscalers, enterprise customers, and neocloud providers. Increasing CPU requirements for AI infrastructure and agentic workloads provided an important tailwind for the segment.
Yet, the impressive demand figures also exposed a problem that the chipmaker has struggled to resolve. Advanced packaging shortages and manufacturing constraints continue to restrict shipments, leaving the business unable to fully translate customer demand into delivered products.
The picture was less encouraging in Client Computing and Physical AI (CCPG), where revenue declined 5% from the corresponding period last year to $8.1 billion. Higher memory prices, tighter IT budgets, and inventory reductions among original equipment manufacturers (OEMs) continued to pressure PC demand, making this division a notable weak spot in an otherwise stronger quarter.
Elsewhere, Intel Foundry delivered one of the more encouraging performances, with revenue climbing 58% YoY to $6.7 billion. Financial flexibility also improved, as adjusted free cash flow rose 92.9% YoY to $1.7 billion.
Looking ahead, management expects Q4 revenue to range between $15 billion and $16 billion. Its guidance also calls for a non-GAAP gross margin of 38% and non-GAAP EPS of $0.25, indicating the next quarter could see a moderation in profitability even as the business navigates supply constraints.
Analysts, meanwhile, anticipate Q4 FY2026 EPS of $0.15, up 275% YoY. The full-year FY2026 estimate stands at $1.04, reflecting 966.7% growth from the previous year. Further out, the FY2027 EPS forecast of $1.31 points to a 26% increase from the prior year.
What Do Analysts Expect for INTC Stock?
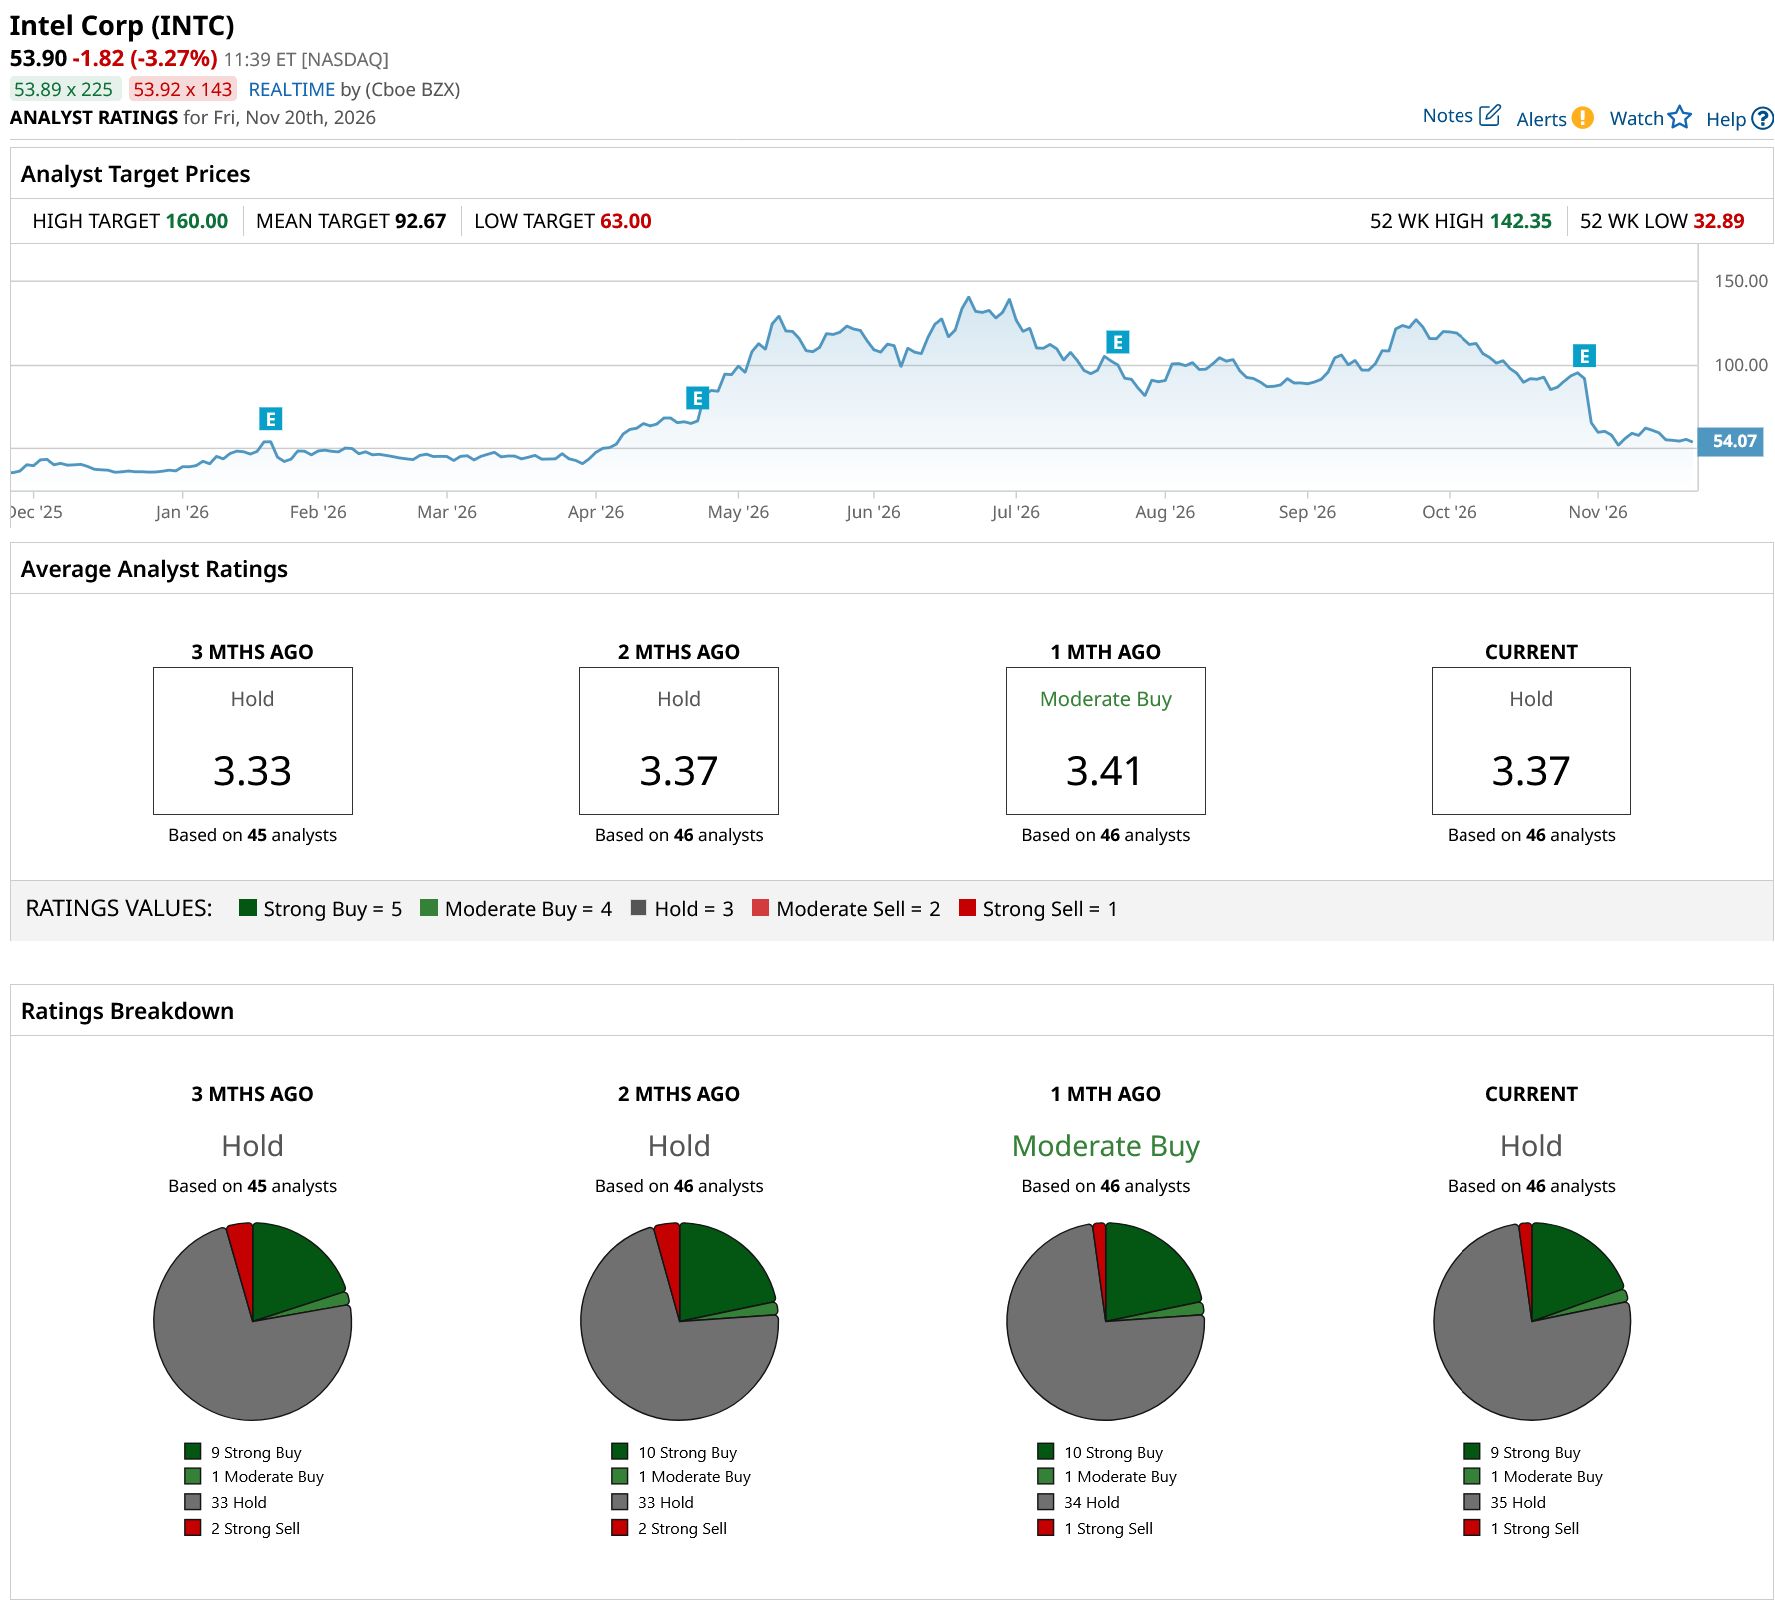
Despite the recent share-price setback, Wall Street's overall stance on Intel remains “Hold.” Of the 46 analysts covering INTC stock, nine have assigned a “Strong Buy” rating, one maintains a “Moderate Buy,” and 35 recommend “Hold,” while one analyst has issued a “Strong Sell” rating.
The average price target currently stands at $92.67, suggesting potential upside of 72%. Meanwhile, the Street-high target of $160 indicates a possible gain of 197% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Robinhood’s Outlook Appears to Be Positive Despite the Kalshi Threat Intel Just Landed Its First 18A-P Chip Customer. What That Means for INTC Stock. AMD Gained From Nvidia’s China Scandal. Now a Short Seller Says AMD Has a China Problem Too. Leadership Risk vs. Record Numbers: Nvidia Posted $115 Billion in Revenue in Its First Report Without Jensen Huang. What It Means for NVDA Stock.