

Shares of ManpowerGroup MAN have had an excellent run over the past three months. The stock has risen 66.8% compared with the industry's 25.2% growth. The Zacks S&P 500 Composite rose 3% during that period.
MAN has a Growth Score of B. This style score condenses key financial metrics to reflect a fair sense of the quality and sustainability of its growth.
The company’s third-quarter 2026 earnings are expected to increase 21.7% year over year. Its 2026 and 2027 earnings are projected to rise 21.9% and 41.2%, respectively. Revenues are anticipated to grow 7.3% in 2026 and 4.4% in 2027.
Factors That Bode Well for MAN’s Success
Broad-Based Demand Supports Growth: ManpowerGroup is benefiting from healthy demand across key verticals, including manufacturing, automotive, aerospace, logistics and retail, supported by strengthening sales activity in the United States. Manpower revenues increased 8% year over year in constant currency in the second quarter of 2026, marking its fifth consecutive quarter of growth. Sustained client demand across these end markets provides a firmer foundation for continued revenue growth and improved earnings over time.
ManpowerGroup Inc. Revenue (Quarterly YoY Growth)
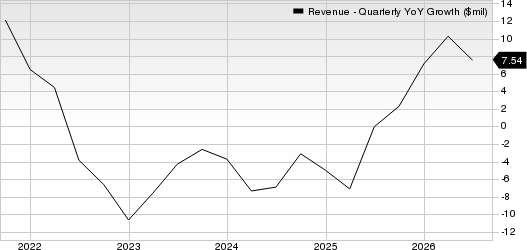
ManpowerGroup Inc. revenue-quarterly-yoy-growth | ManpowerGroup Inc. Quote
Cost Discipline & Technology Investments Boost Efficiency: The company remains focused on pricing discipline, cost control and technology-led efficiency. MAN is expanding artificial intelligence (AI) across sales and recruitment, while its transformation program targets $200 million in permanent annual savings by 2028. In the second quarter of 2026, sales, general and administrative expenses excluding impairment charges declined 4.6% year over year or 6% in constant currency, while adjusted EBITA rose 15% in constant currency to $103 million. Despite restructuring costs and the Jefferson Wells divestiture, ongoing efficiency measures should support profitability.
Consistent Dividend & Share Buybacks: ManpowerGroup maintains a consistent record of returning capital through share repurchases and dividends. Share repurchases totaled $179.8 million in 2023, $140 million in 2024 and $38 million in 2025, while dividend payments were $144.3 million, $145.8 million and $66.7 million, respectively. In the first half of 2026, the company paid an additional $33.5 million in dividends. These sustained capital returns reflect management’s commitment to enhancing shareholder value.
Watch Out for These Risks to MAN Stock
Competition & AI Threats Intensify: ManpowerGroup operates in a fragmented staffing market with low barriers to entry and intense competition from global providers, specialized firms and in-house recruiters. AI could further pressure demand by automating sourcing, screening and candidate matching, reducing reliance on external staffing services.
Liquidity Cushion Narrows: ManpowerGroup’s cash balance fell to $180.6 million in the second quarter of 2026 from $871 million at 2025-end, largely due to $585.8 million of debt repayments. Though long-term borrowings declined to $567.3 million, operating activities used $129 million in the first half. Stronger cash generation will be needed to rebuild liquidity and support the improved leverage profile.
ManpowerGroup has a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Stocks to Consider
A couple of better-ranked stocks in the broader Business Services sector are Thomson Reuters Corporation TRI and Veralto Corporation VLTO.
Thomson Reuters carries a Zacks Rank #2 (Buy) at present. It has a long-term earnings growth expectation of 11.7%.
TRI delivered a trailing four-quarter earnings surprise of 2.7%, on average.
Veralto also holds a Zacks Rank of 2 at present. It has a long-term earnings growth expectation of 8%.
VLTO beat earnings estimates in each of the trailing four quarters, with an average earnings surprise of 6.6%.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ManpowerGroup Inc. (MAN): Free Stock Analysis Report
Thomson Reuters Corp (TRI): Free Stock Analysis Report
Veralto Corporation (VLTO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).