

Aehr Test Systems, Inc. AEHR has become a semiconductor winner in 2026, but expectations now leave little room for disappointment. Investors are weighing two possibilities. Either the market is still catching up to Aehr’s expanding role in AI-related semiconductor testing, or the share price has moved too far ahead of what the business has proved so far.
A Premium Valuation Sets a High Bar
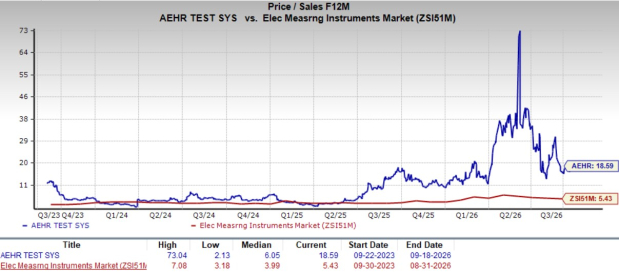
AEHR currently trades at a forward 12-month price-to-sales multiple of 18.59X. That is more than three times its three-year median of 6.05X and well above the broader industry’s average of 5.43X. The gap is also clear against peers. Teradyne, Inc. TER trades at 10.08X, while Cohu, Inc. COHU trades at 3.86X.
The premium leaves little room for shortfalls in bookings, revenue or margins. AEHR’s Value Score of F reinforces the view that the stock is expensive on valuation measures.
Wall Street Still Sees More Upside
Analyst sentiment remains positive despite the elevated multiple. AEHR trades below the average analyst price target of $128, implying about 41.4% upside. The high target stands at $175, while the low target is $110. The wide target range highlights uncertainty over how much future growth is already priced in and whether Aehr can deliver consistently.
AEHR Stock Has Already Repriced the Story
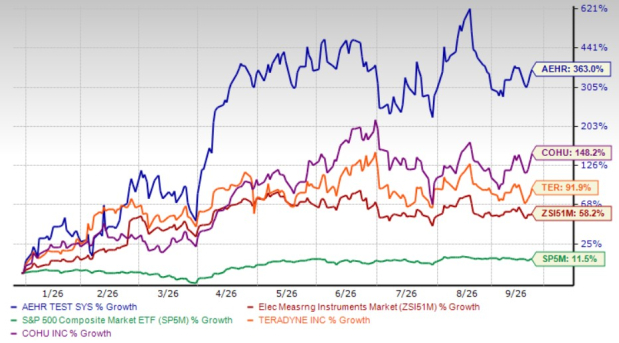
AEHR shares have surged 363% so far this year, far outpacing the industry’s 58.2% growth and the S&P 500’s 11.5% advance. The stock has also beaten Teradyne, up 91.9%, and Cohu, up 148.2%, over the same period.
AEHR entered 2026 weighed down by weak EV-related SiC demand. Its rapid shift toward AI applications has since reshaped the market’s view of the company.
AEHR YTD Performance Vs. TER, COHU, Industry & S&P 500
A Stronger Balance Sheet Supports the Ramp
Aehr ended May 29, 2026, with $116.4 million in cash and cash equivalents, up from $24.5 million a year earlier. Total liabilities stood at $27.2 million. The cash build, supported by equity financing, gives the company flexibility as it prepares for a much larger revenue base. It can fund working-capital needs and support higher production levels.
AI is Driving the Next Phase
The clearest source of growth is AI-related semiconductor testing.Its lead wafer-level AI account is expanding production capacity, supporting demand for FOX-XP systems and WaferPak contactors, while a separate hyperscale customer is scaling package-level burn-in for custom AI processors using Sonoma systems.
Silicon photonics is opening another growth avenue as AI data centers adopt faster optical interconnects. Aehr's lead customer is increasing production, and a newer networking customer has also moved into follow-on system orders for hyperscale deployments.
Silicon carbide offers an additional source of recovery, particularly in electric vehicles, while growing AI data-center power requirements could support renewed demand for both SiC and GaN test solutions.
Aehr is also developing wafer-level burn-in opportunities in memory, including NAND and potential HBM applications. The company is working with multiple memory suppliers, although this remains an early-stage opportunity and is not yet a meaningful contributor to current guidance.
Aehr entered fiscal 2027 with $100.6 million of effective backlog, supporting visibility into its $130-$150 million revenue outlook. Subsequent AI and silicon-photonics production orders further strengthened its order pipeline.
Estimates for AEHR Point to Another Big Step Up
For fiscal 2027, the Zacks Consensus Estimate for Aehr Test Systems’ EPS is projected at 74 cents, a sharp increase from 3 cents a year ago. For fiscal 2028, the estimate is pegged at $1.54, indicating another 108.8% increase. Moreover, analysts project fiscal 2027 revenues of $140.75 million, up 181.5%, followed by $216.67 million in fiscal 2028, implying another 53.9% increase.
Aehr beat earnings estimates in three of the past four quarters and matched once, producing an average earnings surprise of 321.9%.
Aehr Test Systems Price, Consensus and EPS Surprise
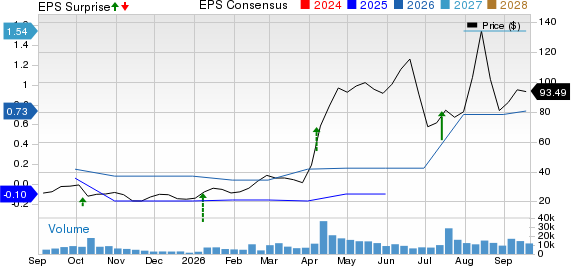
Aehr Test Systems price-consensus-eps-surprise-chart | Aehr Test Systems Quote
What Could Go Wrong
Customer concentration remains a key risk for AEHR. Its five largest customers accounted for roughly 70% of fiscal 2026 revenues, leaving results exposed to shifts in production schedules or spending by a small group of customers. Given the high value of individual system orders, even modest delays or rescheduling can create significant quarterly volatility.
AEHR also remains exposed to semiconductor capital-spending cycles. AI and data-center demand is strong, but equipment spending remains uneven, and orders can shift between quarters.The company itself cautions that backlog does not necessarily translate directly into future revenues.
Execution risk has increased alongside expectations. While manufacturing capacity has been expanded, the company must convert demand into timely shipments and profitable growth while managing supplier and component constraints. After the stock’s sharp rally, setbacks in orders, deliveries or margins could trigger an outsized market reaction.
Conclusion
Aehr’s growth outlook has strengthened, supported by AI demand, silicon photonics, a recovering SiC business and a sizable backlog. Still, the stock’s strong run has pushed valuation to demanding levels, leaving less room for execution missteps.
Customer concentration, lumpy semiconductor spending and the need to convert backlog into profitable growth remain key risks. With strong revenue and earnings growth already reflected in expectations, the risk-reward looks more balanced at current levels. AEHR currently carries a Zacks Rank #3 (Hold), suggesting investors may want to wait for a better entry point or clearer evidence of sustained execution. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Aehr Test Systems (AEHR): Free Stock Analysis Report
Cohu, Inc. (COHU): Free Stock Analysis Report
Teradyne, Inc. (TER): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).