

Arista Networks, Inc. ANET has gained 64.7% year to date compared with the Internet software industry’s growth of 8.8%. The stock has outperformed the Zacks Computer & Technology sector and the S&P 500 during the same time frame.
Image Source: Zacks Investment Research
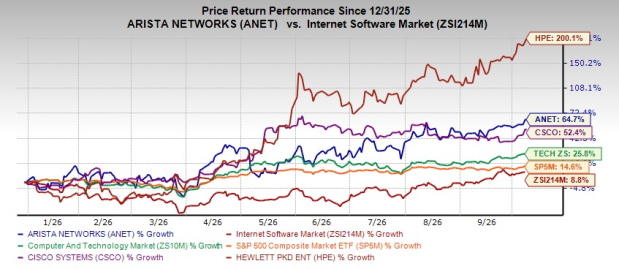
It has underperformed its peers like Hewlett Packard Enterprise Company HPE but outperformed Cisco Systems, Inc. CSCO. HPE has gained 200.1%, and Cisco has increased 52.4% during this period.
AI Networking and Expanding Ethernet opportunity are Growth Drivers
Arista is benefiting from rapidly rising demand for Ethernet-based networking infrastructure used in AI data centers. The company said cumulative customers using its Etherlink AI-fabric switches had surpassed 100 by the second quarter of 2026 compared with only a handful of customers in 2024. Its newer 7060XE7 platform supports up to 1.6-terabit throughput. Features such as Smart System Upgrade (SSU) and Multipath Reliable Connection (MRC) are engineered to improve network reliability and accelerator utilization.
This creates an important opportunity as AI clusters become larger and more geographically distributed. Arista's Scale-Across architecture is designed to connect AI infrastructure across multiple locations. The company expects the Scale-Across switching and routing opportunity to reach roughly $15-$20 billion by 2030.
Enterprises’ transition toward high-speed switching has created a major opportunity for the company. Its portfolio, which consists of traditional Ethernet deployments to 1.6-terabit AI networking platforms, is witnessing sustained market-share gains.
Moreover, Arista’s growth opportunity is increasingly diversified beyond its traditional data-center switching. AI/cloud networking, campus and routing, and cognitive networking through software and services are high-margin areas where Arista is expanding its foothold.
Major Challenges for Arista
One of the biggest risks is customer concentration. Arista generates a significant portion of its sales from large hyperscale customers. Any changes in the capital-spending plans of a relatively small group of buyers can have a material impact on revenue. Arista's inventory reached approximately $2.5 billion at the end of the second quarter, up from $2.4 billion in the prior quarter. Inventory fluctuations could continue as the company balances component availability with customer deployment schedules. This high inventory level can become a burden if customer deployments are delayed or AI infrastructure spending slows.
Arista operates in highly competitive data-center switching, AI networking and Ethernet markets. Competitors include major companies such as Cisco and HPE. Stiff competition puts pressure on pricing and hinders margins. The pressure is already visible in gross margins: second-quarter non-GAAP gross margin was 63.4% compared with 65.6% a year earlier. Management expects the full-year margin to remain within a 62-64% range. In addition to fierce competition, the declining gross margin also reflects higher costs related to memory and silicon.
Estimate Revision Trend
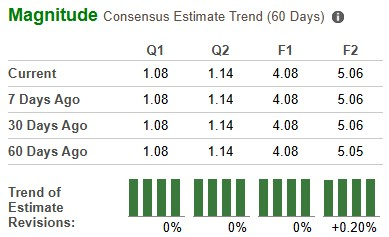
Earnings estimates for Arista for 2026 have remained unchanged and for 2027 it has increased over the past 60 days.
Image Source: Zacks Investment Research
Key Valuation Metric of ANET
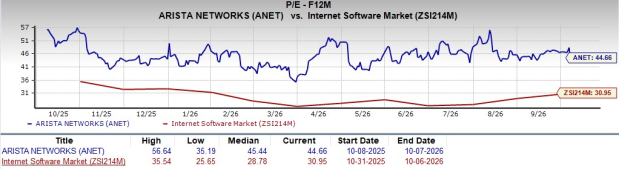
From a valuation standpoint, Arista appears to be relatively more premium than the industry. Going by the price/earnings ratio, the company's shares currently trade at 44.66 book value, higher than 30.95 of the industry average.
Image Source: Zacks Investment Research
End Note
Arista is positioned to benefit from the continued expansion of AI infrastructure and high-speed Ethernet networking. Rising adoption of its Etherlink AI fabrics, expanding Scale-Across opportunity, and broader campus and routing portfolio are positives. However, Heavy reliance on large hyperscale customers makes revenue sensitive to changes in their capital-spending plans. Persistent component shortages and high input costs create supply chain uncertainty. With a Zacks Rank #3 (Hold), Arista has a balanced outlook, as strong AI-driven growth prospects are offset by customer concentration, supply-chain risks and valuation concerns. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Arista Networks, Inc. (ANET): Free Stock Analysis Report
Cisco Systems, Inc. (CSCO): Free Stock Analysis Report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).