

Honeywell Aerospace Inc. HONA reported third-quarter 2026 adjusted earnings of $2.21 per share, which beat the Zacks Consensus Estimate of $1.90 by 16.3%.
HONA’s Q3 Sales Discussion
Revenues increased 2.4% year over year to $4.64 billion, surpassing the consensus estimate of $4.59 billion by 1.1%. Backlog grew 12% to $19.32 billion, supported by a 9% increase in trailing 12-month orders.
Commercial Original Equipment sales increased 7% year over year to $690 million. Organic sales grew 8%, driven by higher commercial air transport production rates and increased demand for selectable aircraft equipment.
Commercial Aftermarket sales rose 2% to $2.13 billion, supported by healthy underlying demand and aircraft returning to active service. Third-quarter orders increased 12% year over year.
Defense and Space revenues increased 1% to $1.83 billion. Robust growth driven by the CAES and Civitanavi acquisitions was partly tempered by supply-chain constraints limiting international deliveries and the phaseout of a restricted government program.
Honeywell Aerospace inc. Price, Consensus and EPS Surprise
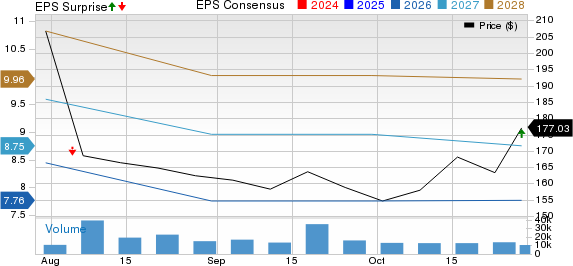
Honeywell Aerospace inc. price-consensus-eps-surprise-chart | Honeywell Aerospace inc. Quote
HONA’s Segment Performance Stays Mixed
Electronic Solutions sales increased 4% year over year to $1.78 billion, with organic growth of 5%. Strength in Commercial Original Equipment and Defense and Space supported the improvement. Segment adjusted EBIT rose 11% to $564 million as tariff refunds and pricing gains more than offset unfavorable sales mix and higher costs.
Engines & Power Systems sales increased 3% to $1.52 billion, driven by higher Commercial Aftermarket volumes. Organic sales advanced 2%. However, segment adjusted EBIT declined 16% to $250 million as unfavorable mix and higher costs outweighed pricing benefits and tariff refunds.
Control Systems revenues remained relatively flat at $1.35 billion. Defense and Space growth was offset by weaker Commercial Aftermarket sales. Segment adjusted EBIT increased 2% to $382 million as favorable pricing more than compensated for higher costs and unfavorable mix.
HONA's Profitability Benefits From Tariff Refunds
Adjusted EBIT increased 0.9% year over year to $1.16 billion from $1.15 billion. The adjusted EBIT margin contracted 40 basis points to 25%, reflecting unfavorable sales mix and incremental standalone operating costs.
Results included approximately $50 million in net tariff refund benefits, which contributed more than 100 basis points to adjusted EBIT margin. Reported net income increased 12.7% to $737 million from $654 million.
HONA’s Financial Position
HONA generated $668 million in operating cash flow during the third quarter compared with $839 million a year earlier. Capital expenditures totaled $168 million, resulting in free cash flow of $500 million.
Cash and cash equivalents amounted to $1.56 billion as of Sept. 26, 2026, compared with $213 million as of 2025-end. Long-term debt totaled $15.85 billion, reflecting financing transactions associated with the company's separation from Honeywell.
HONA Raises 2026 Earnings Outlook
Management raised its full-year 2026 pro forma standalone adjusted earnings guidance to $7.85-$8.00 per share from $7.60-$7.90. The Zacks Consensus Estimate is pinned at $7.77 per share, which is lower than the company’s newly guided range.
The company maintained its organic sales growth outlook of 4-5%.
Pro forma standalone adjusted EBIT is now projected to be $4.375-$4.425 billion compared with the previous guidance of $4.35-$4.45 billion.
HONA’s Zacks Rank
The company currently has a Zacks Rank #5 (Strong Sell).
You can see the complete list of today's Zacks #1 Rank (Strong Buy) stocks here.
Recent Defense Releases
Hexcel Corporation HXL reported third-quarter 2026 adjusted earnings of 50 cents per share, which improved 35.1% from the year-ago quarter’s figure of 37 cents. The bottom line surpassed the Zacks Consensus Estimate of 48 cents by 4.2%.
HXL’s net sales totaled $496.4 million, which missed the Zacks Consensus Estimate of $500 million by 0.8%. The top line, however, witnessed an improvement of 8.8% from the year-ago quarter’s figure of $456.2 million.
RTX Corporation’s RTX third-quarter 2026 adjusted earnings per share (EPS) of $2.26 beat the Zacks Consensus Estimate
of $1.78 by 27%. The bottom line improved 32.9% from the year-ago quarter’s level of $1.70.
RTX’s revenues rose 11.1% year over year to $24.97 billion and beat the consensus mark of $24.01 billion by 4%. Growth was supported by higher commercial aftermarket and defense demand.
Lockheed Martin Corporation LMT reported third-quarter 2026 adjusted earnings of $7.97 per share, which beat the Zacks Consensus Estimate of $7.49 by 6.4%. The bottom line increased 14.7% from the year-ago quarter's reported figure of $6.95.
LMT’s net sales were $20.71 billion, which beat the Zacks Consensus Estimate of $20.44 billion by 1.4%. The top line inched up 11.3% from $18.61 billion reported in the year-ago quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Honeywell Aerospace inc. (HONA): Free Stock Analysis Report
Lockheed Martin Corporation (LMT): Free Stock Analysis Report
Hexcel Corporation (HXL): Free Stock Analysis Report
RTX Corporation (RTX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).