

Howmet Aerospace Inc. HWM reported third-quarter 2026 adjusted earnings of $1.46 per share, up 54% year over year. The figure beat the Zacks Consensus Estimate of $1.37 by 6.6%.
Revenues of $2.70 billion increased 29% year over year and surpassed the consensus mark of $2.59 billion by 4.2%. Organic growth was 25%, supported by strong commercial aerospace, defense aerospace and gas turbine demand. Gas turbine revenues surged 45%, while commercial aerospace revenues increased 32%.
HWM's Aerospace and Gas Turbine Markets Drive Growth
Commercial aerospace revenues rose 32% year over year and represented 54% of total revenues. Growth reflected stronger demand for aircraft engine components and spare parts, supported by increasing aircraft production activity.
Gas turbine revenues advanced 45% and accounted for 13% of total revenues. Defense aerospace revenues increased 10%, while commercial transportation revenues rose 28%. Other-market revenues grew 48%. Management highlighted strengthening gas turbine demand and increasing customer volume requirements.
Howmet Aerospace's Engine Products Posts Strong Gains
Engine Products generated revenues of $1.45 billion, accounting for 53.7% of consolidated revenues. Segment revenues increased 33% year over year, driven by commercial aerospace and gas turbine demand, including higher demand for engine spare parts.
Segment adjusted EBITDA climbed 57% to $567 million. The adjusted EBITDA margin expanded 580 basis points to 39.1%. Howmet Aerospace added approximately 520 net employees in the segment during the quarter to support expected revenue growth.
HWM's Fastening Systems Benefits From Acquisitions
Fastening Systems revenues increased 41% year over year to $630 million, representing 23.3% of total revenues. Results benefited from commercial and defense aerospace growth as well as contributions from the CAM and Brunner acquisitions. Excluding acquisitions, revenues increased 10%.
Segment adjusted EBITDA rose 34% to $185 million. However, the adjusted EBITDA margin contracted 140 basis points to 29.4%, reflecting the impact of the CAM acquisition. The segment continued benefiting from stronger demand across its aerospace markets.
Howmet Aerospace's Other Segments Show Mixed Trends
Engineered Structures revenues declined 4% to $295 million, primarily due to the divestiture of the Savannah disk forging facility. Excluding the divestiture, organic revenues increased 8%. Segment adjusted EBITDA rose 9% to $70 million, while the margin expanded 290 basis points to 23.7%, benefiting from the exit of lower-margin business and product rationalization.
Forged Wheels revenues climbed 32% to $327 million, driven by higher commercial transportation volumes and increased aluminum cost pass-through. Segment adjusted EBITDA increased 18% to $86 million. However, the margin contracted 330 basis points to 26.3%, reflecting the impact of higher aluminum cost pass-through.
Howmet Aerospace Inc. Price, Consensus and EPS Surprise
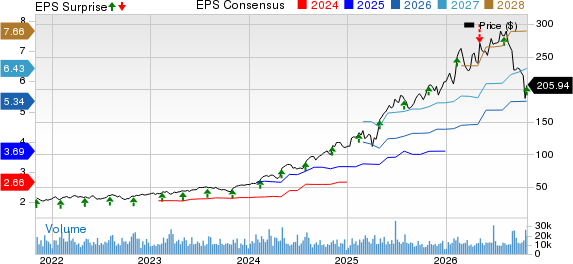
Howmet Aerospace Inc. price-consensus-eps-surprise-chart | Howmet Aerospace Inc. Quote
HWM's Margin Expansion Supports Profitability
Adjusted EBITDA increased 43% year over year to $879 million. The adjusted EBITDA margin expanded 310 basis points to 32.5%, supported by growth across commercial aerospace, defense aerospace, gas turbines and commercial transportation markets.
Adjusted operating income rose 45% to $786 million. The adjusted operating margin improved 320 basis points to 29.1%. On a GAAP basis, operating income increased 43% to $777 million, while the operating margin expanded 280 basis points to 28.7%.
Howmet Aerospace's Cash Flow Backs Capital Deployment
Howmet Aerospace generated $709 million in cash from operations during the quarter, up 34% year over year. Capital expenditures were $147 million, resulting in free cash flow of $562 million, up 33% year over year. The company ended the quarter with a cash balance of $508 million.
The company repurchased $500 million of common stock during the quarter, bringing year-to-date repurchases to $1.1 billion. It also paid down $60 million of debt and increased its quarterly dividend 17% to 14 cents per share. On Oct. 28, the board authorized an additional $5 billion in share repurchases, raising the total authorization to approximately $5.4 billion.
HWM Raises 2026 Guidance
For the fourth quarter of 2026, HWM expects revenues of $2.74-$2.76 billion. Adjusted EBITDA is projected between $895 million and $905 million, while adjusted earnings are expected in the range of $1.49-$1.51 per share.
For 2026, Howmet Aerospace raised its revenue outlook to $10.29-$10.31 billion. Adjusted EBITDA is now anticipated between $3.325 billion and $3.335 billion, with adjusted earnings projected at $5.49-$5.51 per share. Free cash flow is expected in the range of $1.95-$2.05 billion.
The company also introduced its 2027 revenue outlook of approximately $11.5 billion, representing expected growth of about 12% year over year.
HWM’s Zacks Rank
The company currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Other Stocks to Consider
Some other top-ranked stocks are discussed below.
RTX Corporation’s RTX third-quarter 2026 adjusted earnings per share (EPS) of $2.26 beat the Zacks Consensus Estimate of $1.78 by 27%. The bottom line improved 32.9% from the year-ago quarter’s level of $1.70.
Revenues rose 11.1% year over year to $24.97 billion and beat the consensus mark of $24.01 billion by 4%. Growth was supported by higher commercial aftermarket and defense demand.
Northrop Grumman Corporation NOC reported third-quarter 2026 adjusted earnings of $7.89 per share, which beat the Zacks Consensus Estimate of $7.22 by 9.3%. The bottom line also increased 2.9% from the year-ago quarter’s level of $7.67.
NOC’s total sales of $11.12 billion in the third quarter beat the Zacks Consensus Estimate of $11.06 billion by 0.6%. The top line also improved 6.7% from $10.42 billion in the year-ago quarter.
Grupo Aeromexico, S.A.B. de C.V. AERO reported $1.62 billion in revenues in the third quarter of 2026, representing no change year over year. EPS was 28 cents compared with break-even earnings a year ago.
Reported revenues exceeded the Zacks Consensus Estimate of $1.61 billion by 0.62%. EPS missed the consensus mark of $0.29, delivering an average negative surprise of 3.45%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Howmet Aerospace Inc. (HWM): Free Stock Analysis Report
Northrop Grumman Corporation (NOC): Free Stock Analysis Report
Grupo Aeromexico SAB DE CV - Sponsored ADR (AERO): Free Stock Analysis Report
RTX Corporation (RTX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).