

With a market cap of $39.1 billion, California-based NetApp, Inc. (NTAP) is a leading provider of enterprise data storage and intelligent data infrastructure, helping businesses manage, protect, and activate data across on-premises systems, hybrid environments, and major public clouds. Its portfolio combines all-flash storage, cloud services, and data-management software, with its ONTAP platform at the core.
Companies valued at $10 billion or more are generally considered “large-cap” stocks, and NetApp fits this criterion perfectly. Its leadership lies in its enterprise storage, strong hybrid-cloud capabilities, and deeply embedded customer relationships. Its ONTAP platform offers unified data management across on-premises and cloud environments, while partnerships with major cloud providers strengthen its position as enterprises shift toward hybrid infrastructure. NetApp also benefits from its growing all-flash storage portfolio, recurring software and services revenue, and expanding AI-focused data infrastructure offerings.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
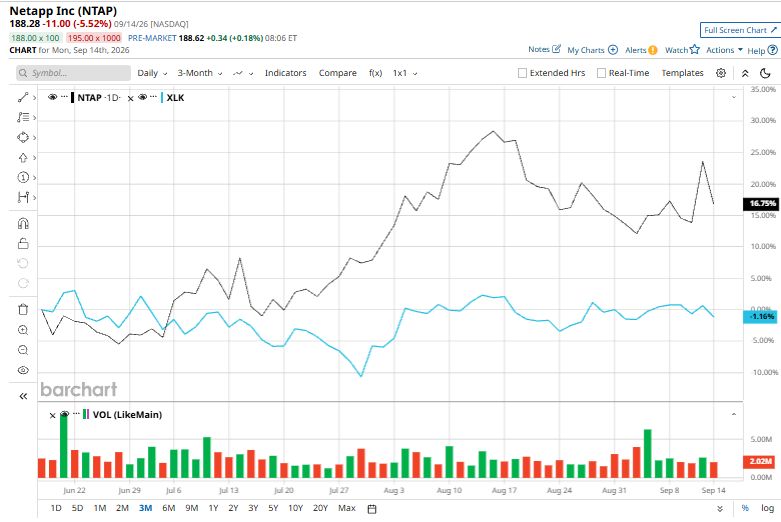
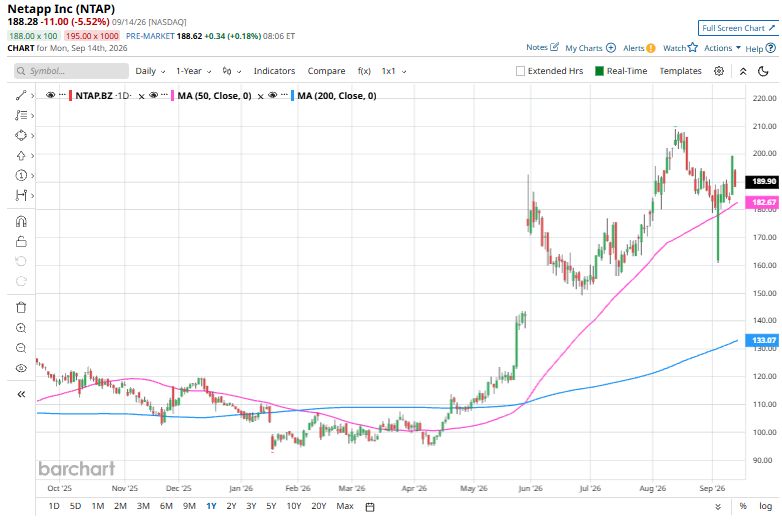
NetApp may be off its recent peak, but the broader trend remains firmly bullish. Shares have slipped 9.9% from their 52-week high of $209.06, reached on Aug. 13, but the pullback follows a strong rally. NTAP has surged 16.5% over the past three months, easily outperforming the State Street Technology Select Sector SPDR ETF (XLK), which declined marginally.
 www.barchart.com
The stock’s longer-term performance is even more impressive. NTAP has gained 75.8% year to date and 51.8% over the past 52 weeks, outpacing XLK’s gains of 28% and 36.1%, respectively.
Technically, the bullish momentum remains intact, with shares trading above both their 50-day and 200-day moving averages since April.
 www.barchart.com
NTAP’s strong execution and growing foothold in AI and enterprise data infrastructure have helped propel the stock ahead of the broader market over the past year. As businesses race to build AI capabilities, demand is rising for the storage and data-management infrastructure needed to handle increasingly data-intensive workloads. NetApp is well positioned to benefit, with improving profitability and a growing mix of recurring software and services revenue adding to investor confidence.
That AI and cloud momentum got another boost on Sept. 3, when NetApp and Amazon Web Services announced that AWS Transform would now support Amazon FSx for NetApp ONTAP. The integration brings agentic AI into the cloud-migration process, automating workload discovery, planning, and migration while allowing enterprises to move computing, networking, and storage together.
On Sept. 2, NetApp delivered a standout Q1 FY2027, with results beating expectations across the board. Revenue jumped 29.9% year over year to a record $2.03 billion, while non-GAAP EPS surged 66% to $2.58, comfortably topping analyst estimates. Strong demand for AI-ready infrastructure and all-flash storage led growth, with all-flash array revenue climbing 47% to a record $1.3 billion. Public Cloud revenue also rose 28% to $206 million, while billings increased 36.1% to $2.06 billion. The company also acquired AI data-infrastructure provider DataPelago, reinforcing its push into AI workloads
The strong quarter prompted NetApp to significantly raise its FY2027 outlook, now calling for revenue of $7.98 billion-$8.23 billion and non-GAAP EPS of $9.73-$10.03. Investors were pleased and sent the shares up 2.6% in the next trading session.
In comparison, rival Western Digital Corporation (WDC) has significantly outperformed NTAP stock. Shares of Western Digital have soared 337.2% over the past 52 weeks and 147.8% on a YTD basis.
Nevertheless, analysts remain moderately optimistic about its prospects. Among the 21 analysts covering the stock, there is a consensus rating of “Moderate Buy,” and the mean price target of $197.71 suggests a premium of 5% to its current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.