

Since artificial intelligence (AI) burst onto the scene a few years ago, the technology’s explosive popularity has put a spotlight on companies positioned to benefit from the AI infrastructure boom, and Vertiv Holdings (VRT) is one name that has increasingly grabbed investors’ attention. Vertiv has carved out a niche as a developer of equipment that keeps data centers up and running. The company does not make chips. Instead, it focuses on the critical infrastructure behind them, including power systems, cooling solutions that keep compute hardware running around the clock, and specialized racks integrated into data centers.
As a result, Vertiv’s long-term growth story is closely tied to the rapid adoption of AI and the massive capital expenditures being poured into data centers. The liquid-cooling company returned to focus on Thursday after announcing that it had entered into an agreement to acquire King Environmental Services, a Europe-based provider of fluid management, commissioning, and load-testing services for high-density, liquid-cooled data centers and other applications.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The acquisition is expected to expand Vertiv’s global thermal-management services capabilities across Europe, the Middle East, and Africa while advancing its strategy of supporting customers across the entire thermal chain. The deal also builds on Vertiv’s established North American fluid-management presence, including its 2025 acquisition of PurgeRite, and represents the next step in expanding its global thermal- and fluid-management services platform.
By combining King Environmental’s regional field expertise and load-testing capabilities with Vertiv’s broader services portfolio, the company expects to provide more comprehensive support as customers deploy and operate increasingly complex AI and high-density infrastructure with greater reliability, efficiency, and accountability. So, with this latest acquisition adding another piece to Vertiv’s AI infrastructure story, how should investors approach VRT stock now?
About Vertiv Stock
Founded in 1946 and headquartered in Columbus, Ohio, Vertiv Holdings is a company that helps keep the world’s data centers running. Think of Vertiv as the behind-the-scenes infrastructure provider for the digital economy. While chipmakers build the processors that power AI, Vertiv provides the equipment needed to keep those chips and servers powered, protected, and cool. Its customers include data centers, cloud providers, and other businesses that rely on always-on computing infrastructure.
Vertiv’s business revolves around two things data centers cannot afford to get wrong: power and cooling. Its portfolio includes uninterruptible power supplies (UPS), power distribution systems, cooling and thermal-management solutions, racks and enclosures, monitoring software, and related services. As AI makes data centers more powerful and significantly hotter, demand for advanced cooling and reliable power infrastructure is rising. That puts Vertiv at an interesting spot in the AI boom, supplying the essential systems that help turn massive computing power into a reliable, always-on operation.
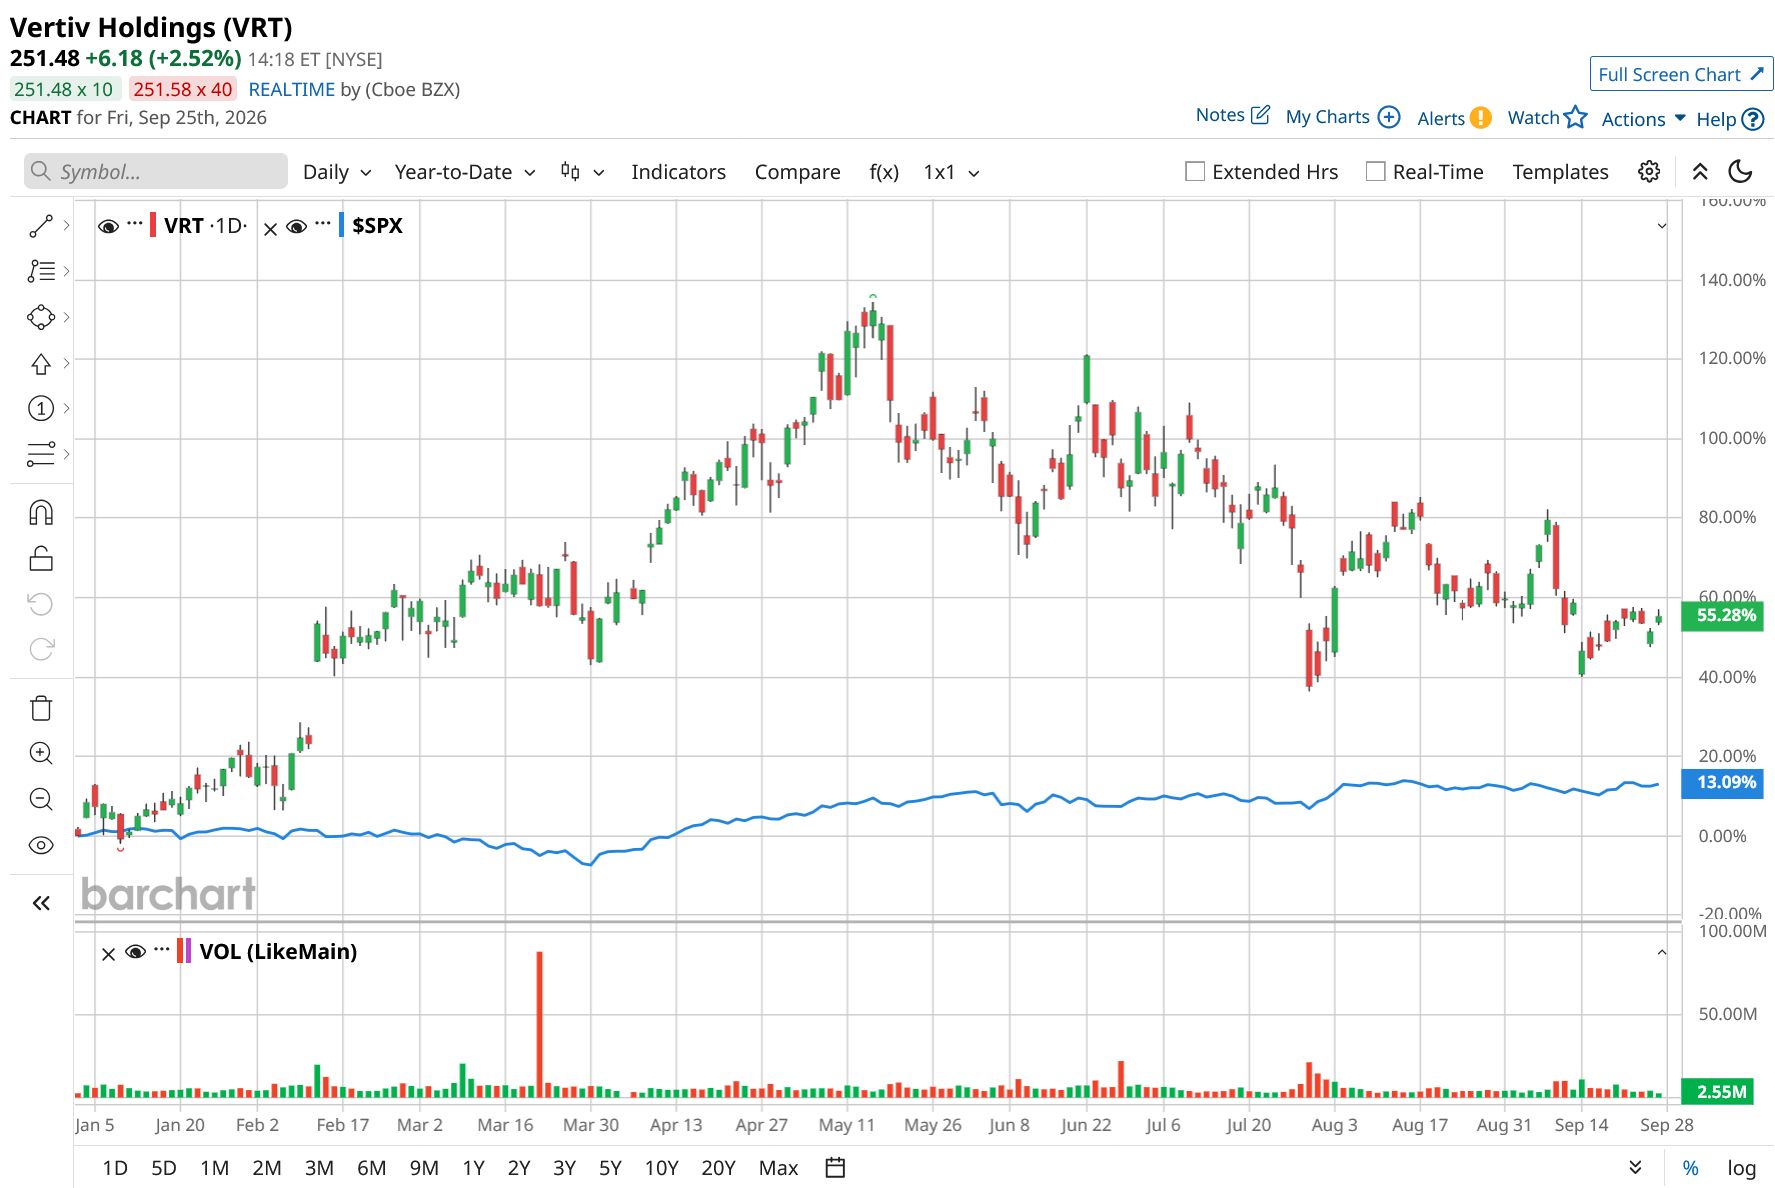
Having said that, Vertiv’s stock performance has been anything but smooth lately. Shares have fallen roughly 23% over the past three months, as investors digest a revenue miss in the company’s latest quarterly report and worry that some AI data center projects are taking longer than expected to translate into reported sales. For perspective, the broader S&P 500 Index ($SPX) has gained roughly 5.2% over the same three-month period.
With a market capitalization of roughly $94.44 billion, Vertiv is currently sitting nearly 34% below its 52-week high of $379.93, reached on May 14. But zoom out, and the picture looks considerably brighter. Despite the recent pullback, the liquid-cooling giant’s shares are still up a notable 80% over the past year and have climbed 55% so far in 2026. That compares with gains of 16.6% over the past year and 12.5% year-to-date (YTD) for the broader market, showing that Vertiv’s longer-term AI infrastructure story remains firmly in focus despite the recent turbulence.
 www.barchart.com
Q2 Earnings Snapshot
Vertiv’s fiscal 2026 second-quarter results delivered a mixed picture for investors. The company released its earnings report on July 29, and while it comfortably beat Wall Street’s bottom-line expectations, a slight revenue miss weighed heavily on sentiment, triggering a 17.3% selloff in Vertiv shares on the day. Net sales came in at $3.27 billion, up 24% year-over-year (YoY), but fell slightly short of Wall Street’s consensus estimate of roughly $3.38 billion.
Management attributed the shortfall largely to minor timing shifts, including temporary supply-chain congestion and the execution of multi-phased projects as deployments continue to grow larger and more complex. The revenue miss, however, did little to take the shine off Vertiv’s profitability. Second-quarter operating profit surged 44% YoY to $638 million, while adjusted operating profit jumped 51% to $738 million.
The adjusted operating margin expanded by 410 basis points to 22.6%, supported by strong operational execution, continued productivity gains, and favorable price-cost dynamics, including the impact of tariffs and related countermeasures. The bottom line was another clear bright spot. Adjusted EPS came in at $1.52, up 60% YoY and comfortably ahead of Wall Street’s $1.43 estimate.
Cash generation was arguably even more impressive, highlighting the underlying strength of Vertiv’s business. Net cash generated from operating activities reached $1.1 billion, while adjusted free cash flow came in at $925 million, soaring 241% and 234%, respectively, from the second quarter of 2025. Vertiv also ended the quarter with $5.6 billion in liquidity and a net cash position, further strengthening its balance sheet and giving the company significant strategic flexibility.
Looking ahead, Vertiv appears increasingly confident in the strength of its growth pipeline. With demand expanding globally and its pipeline continuing to strengthen, management raised its outlook for fiscal 2026. Full-year net sales guidance was bumped up to a $14 billion midpoint, while adjusted EPS guidance was raised to $6.70, signaling management’s confidence in sustaining strong performance as AI-driven infrastructure demand continues to accelerate.
How Do Analysts View VRT Stock?
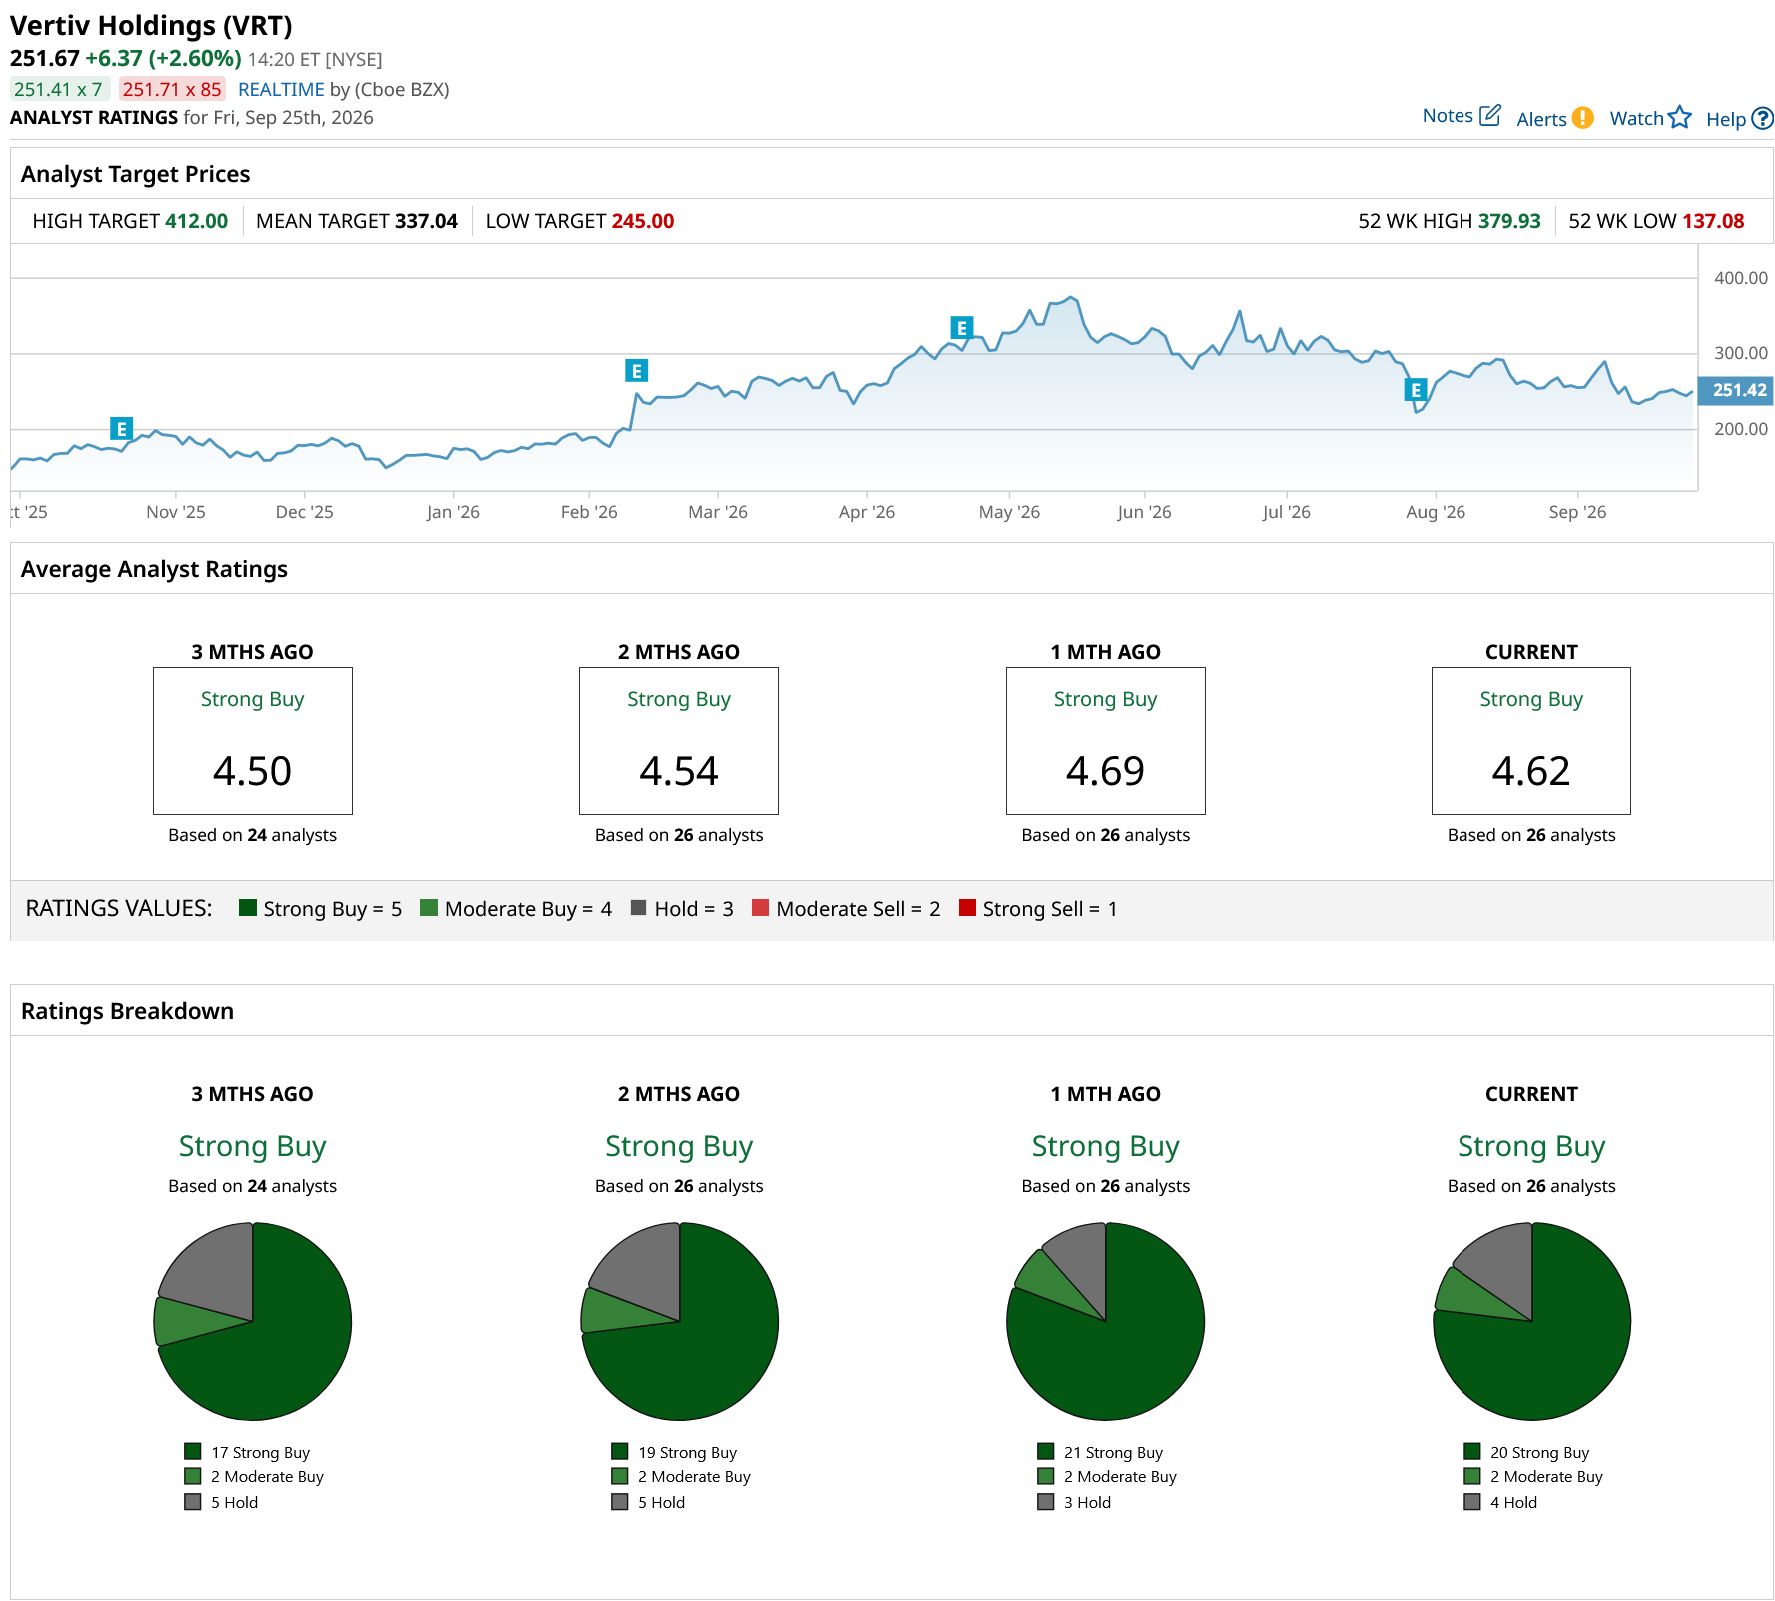
Despite the recent pullback, Wall Street hasn’t lost faith in Vertiv. The stock continues to command a consensus “Strong Buy” rating, reflecting broad optimism around its longer-term growth prospects. Of the 26 analysts covering the company, 20 recommend a “Strong Buy,” while two have a “Moderate Buy” rating and four advise investors to “Hold.”
The bullish outlook is also reflected in analysts’ price targets for VRT stock. The average target of $337.04 suggests roughly 34% upside from current levels. Even more striking, the Street-high target of $412 points to potential gains of nearly 64%, underscoring just how much upside some analysts see if Vertiv can overcome its near-term challenges and capitalize on continued AI-driven data center demand.
 www.barchart.com
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
PYPL Stock Alert: What to Know as PayPal Takeover Rumors Restart How to Play VRT Stock as Vertiv Acquires King Environmental Services Unusual Options Activity in Microsoft Stock Is Already Paying Off (and 3 Other Stocks to Watch) Ford Is Expected to Lose Market Share in Q3. Don’t Panic-Sell F Stock on the News.