

Rocket Lab (RKLB) may be about to inherit some of SpaceX’s (SPCX) customers. SpaceX has stopped selling new rideshare missions on Falcon 9, according to a Wall Street Journal report last week. Some operators also can’t book flights beyond 2028. SpaceX is shifting its focus to Starship, its massive new rocket. With launch demand expected to outpace supply until at least 2030, customers need another way to orbit. Rocket Lab’s reusable Neutron rocket is being positioned as that alternative.
The demand is already showing up in Rocket Lab’s numbers. The company signed more than $437 million in new launch contracts in the second quarter and the weeks after. That pushed its launch backlog above 90 launches, the highest in the company's history. Kepler Communications, a Canadian satellite operator, is a good example of this shift. It flew its latest satellites on a SpaceX rideshare in January, but has now booked an entire Neutron rocket for as early as 2028, the same year Falcon 9 bookings run out. Rocket Lab CEO Peter Beck called it a sign that Neutron is on track to become the industry’s alternate ride to space for larger payloads.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Neutron Now Has to Deliver
As I have covered previously, the debate around Rocket Lab has shifted to whether its success is already priced in. Earlier this month, I pointed out reasons why RKLB stock keeps going down as the company gets better. This news adds to the demand story, but Neutron still hasn’t flown.
Rocket Lab stated in August that the window for Neutron’s first launch this year is narrowing. Beck said the goal is to reach 10 launches as quickly as possible. The reason this matters is that customers leaving Falcon 9 will want a proven rocket.
Rocket Lab has the money to get there, holding about $2.4 billion in cash and marketable securities as of the end of Q2. Now, the firm needs Neutron to build a track record before 2028. In short, it is on the right track, but delivering Neutron on time is now more important than ever to capitalize on Falcon 9's possible retirement.
Even if Neutron fails, however, there is a lot for the company to fall back on. Neutron is only one part of the bull thesis. The reason Neutron takes all the limelight is because it is what will open the door to the space economy for Rocket Lab.
About Rocket Lab Stock
Rocket Lab is a space company that launches satellites and builds spacecraft. The company is now developing Neutron, a reusable rocket designed to carry much larger payloads than the firm's Electron rocket. Founded in 2006, Rocket Lab is headquartered in Long Beach, California.
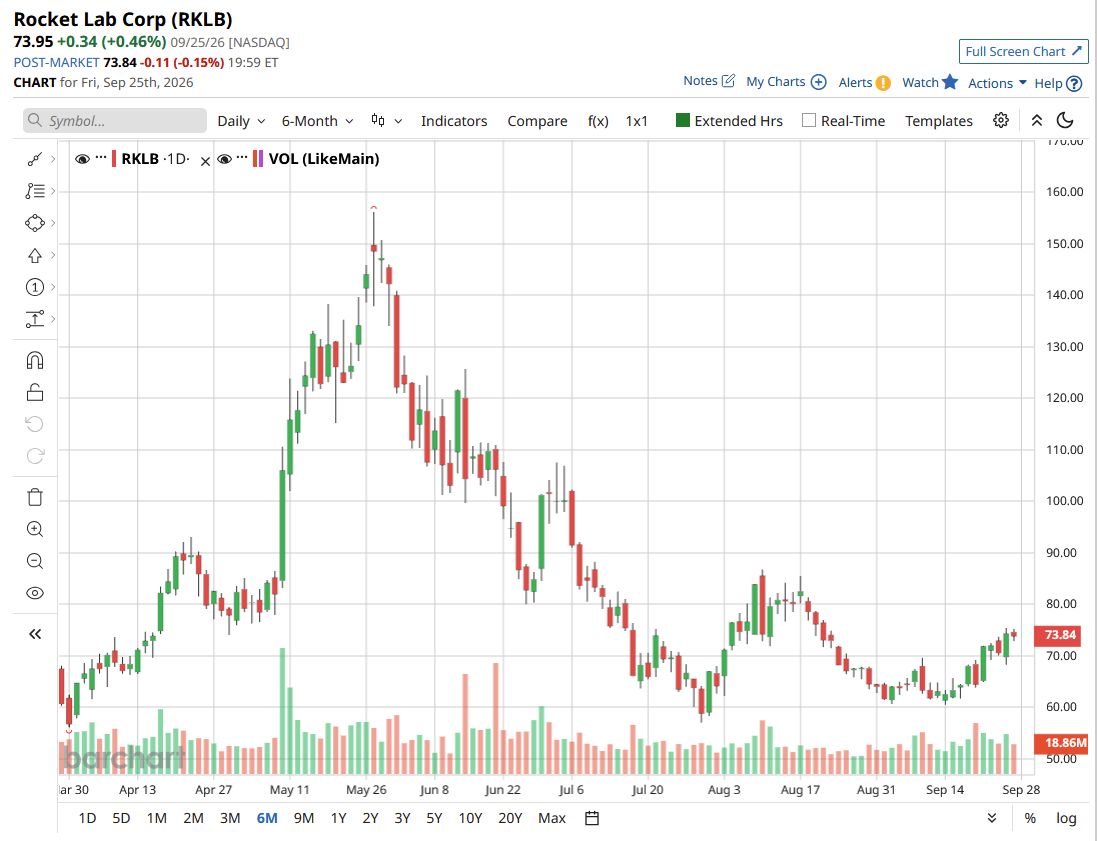
Over the past 12 months, RKLB stock has surged 48%, far outperforming the SPDR S&P Aerospace and Defense ETF’s (XAR) 1% gain during the same period. Since reaching its 52-week high of $151 in late May, though, the stock has lost more than half its value and now sits around the $70 mark. SpaceX’s initial public offering (IPO) and Neutron delays have both weighed on RKLB stock.
 www.barchart.com
Rocket Lab Guides for Another Record Quarter as Iridium Deal Moves Forward
Rocket Lab released its second-quarter earnings on Aug. 10. The company reported revenue of $234 million, up 62% year-over-year (YOY). Loss per share came in at $0.08, worse than the $0.06 loss that analysts expected. The company’s GAAP gross margin for the quarter was 36.1%, above guidance of 33% to 35%. Cash and funding capacity were central to investors' focus. Cash, cash equivalents, restricted cash, and marketable securities came in at roughly $2.4 billion as of Q2. CFO Adam Spice said the increase was driven by Rocket Lab's at-the-market (ATM) program, which generated $1.08 billion during the quarter.
Looking forward, the company expects Q3 revenue to come in at a range between $250 million and $265 million. Management also guided for a GAAP gross margin of 29% to 31% and a non-GAAP gross margin of 35% to 37%. Adjusted EBITDA loss is expected to range between $17 million and $23 million.
Management said that Neutron remains on track for delivery to the pad in Q4 2026. The company also pointed to a growing backlog, strong government demand, and continued expansion in Europe through Rocket Lab Germany.
What Do Analysts Expect for Rocket Lab Stock?
Raymond James analyst Brian Gesuale recently started coverage of RKLB stock with an “Outperform” rating and an $80 price target. Gesuale pointed to Rocket Lab’s strong backlog growth and a path to positive cash flow by 2028.
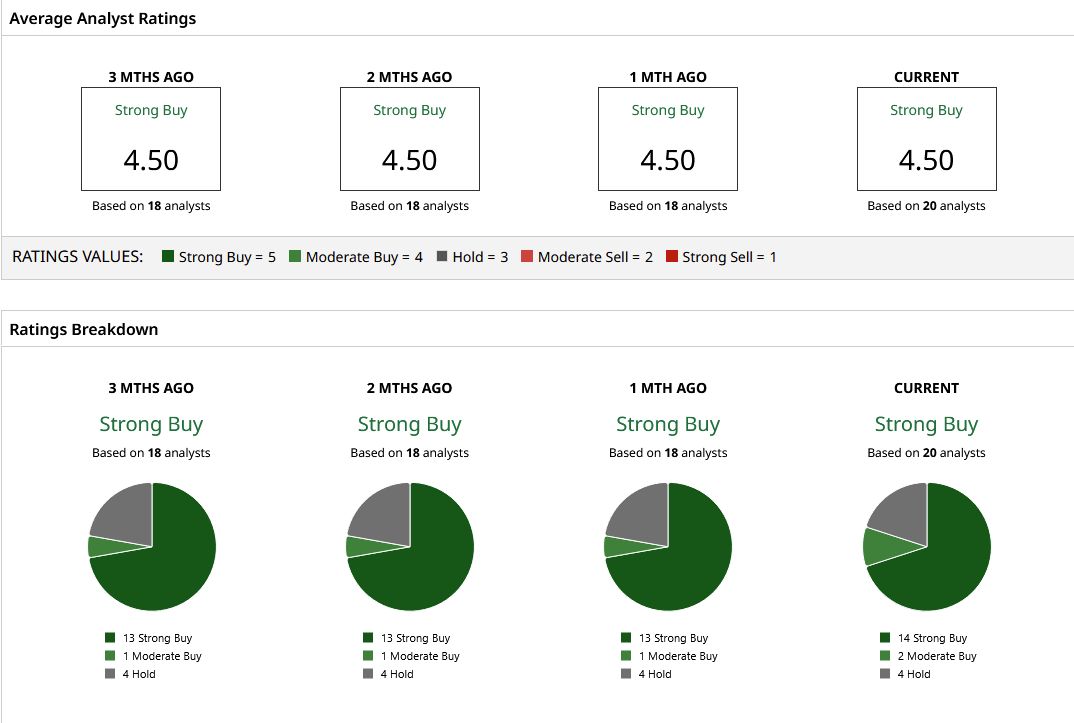
Based on 20 Wall Street analysts covering the stock, Rocket Lab holds a consensus “Strong Buy” rating overall. The mean price target of $110.11 indicates potential upside of 57% from current levels. Further, none of the 20 analysts with coverage hold a “Sell” rating on RKLB stock, and even the lowest price target of $76 reflects a rise from the current share price. This suggests that Wall Street is largely bullish on Rocket Lab.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Rocket Lab Steps In Where SpaceX Just Walked Away This Analyst Says It's Time to Buy Royal Caribbean Stock. Here's Why. Bloom Energy Is Up More Than 200% So Far This Year. What Comes Next for BE Stock. A $2 Billion Reason Why AstraZeneca Stock Is Down Today