

Keep an eye on American Express (AXP). Not only can you collect a yield from the down, but far from out credit card stock, you can also benefit from how oversold it has become heading into earnings. With a yield of 1.24%, AXP will pay a dividend of 95 cents per share on Nov. 10 to shareholders of record as of Oct. 9.
 www.barchart.com
Plus, we’ll get a better view of consumer spending habits, borrowing trends, and the cost of keeping premium cardholders happy when the recovering stock posts third-quarter earnings ahead of the bell on Friday morning. American Express is expected to report earnings of $4.58 per share on revenue of about $20.12 billion. That would represent earnings growth of approximately 10.6% and revenue growth of roughly 9.2% compared with the $4.14 per share and $18.43 billion in revenue posted a year earlier.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
One of the key numbers to watch will be billed business. In the second quarter, the billed business number of $455.8 billion was 9% higher year-over-year (YoY). This number will be important to watch for the third quarter too, especially after American Express raised its full-year revenue growth guidance to 10% thanks to spending in travel, dining, and entertainment.
Premium Cards Create More Opportunity
Premium card growth is also vital to keep an eye on. While the costs can be steep, American Express wants its customers to see those cards as worth it YoY. After all, customers who value the benefits of those cards may renew, use their cards more frequently, and continue to pay relationship fees year after year. Investors will want to keep a close eye on these numbers in the latest report. In the second quarter, the company added three million new cards, with 75% of those being fee-paying cards.
To carry a Platinum Card, you’ll pay an annual fee of about $895, which also gives you solid benefits. The American Centurion Card, or the Black Card, has a $10,000 initiation fee, plus an annual fee of $5,000. Meanwhile, the Gold Card will cost $325 a year.
Second Quarter Numbers Were Mixed
For comparison, in its second quarter, the company’s EPS of $4.53 beat by 13 cents. Revenue of $19.64 billion missed by $60 million. “We had another excellent quarter, with 10% revenue growth, EPS of $4.53, and card member spending growth of 9%, the highest rate we've seen in three years on an FX-adjusted basis,” said Chairman and CEO Stephen J. Squeri, as quoted in the company’s earnings report.
“We are raising our full-year revenue growth guidance to 10 percent and plan to reinvest this outperformance in growth initiatives given the significant opportunities we see ahead. We continue to expect full-year EPS of $17.30 to $17.90. Six months into the year, we’re seeing stronger momentum than we expected. The investments we made in our value propositions have driven accelerated spend and revenue growth; our Platinum portfolio is now the fastest-growing in our U.S. Consumer business,” they added, as noted in the earnings report.
What Do Analysts Say About AXP Stock?
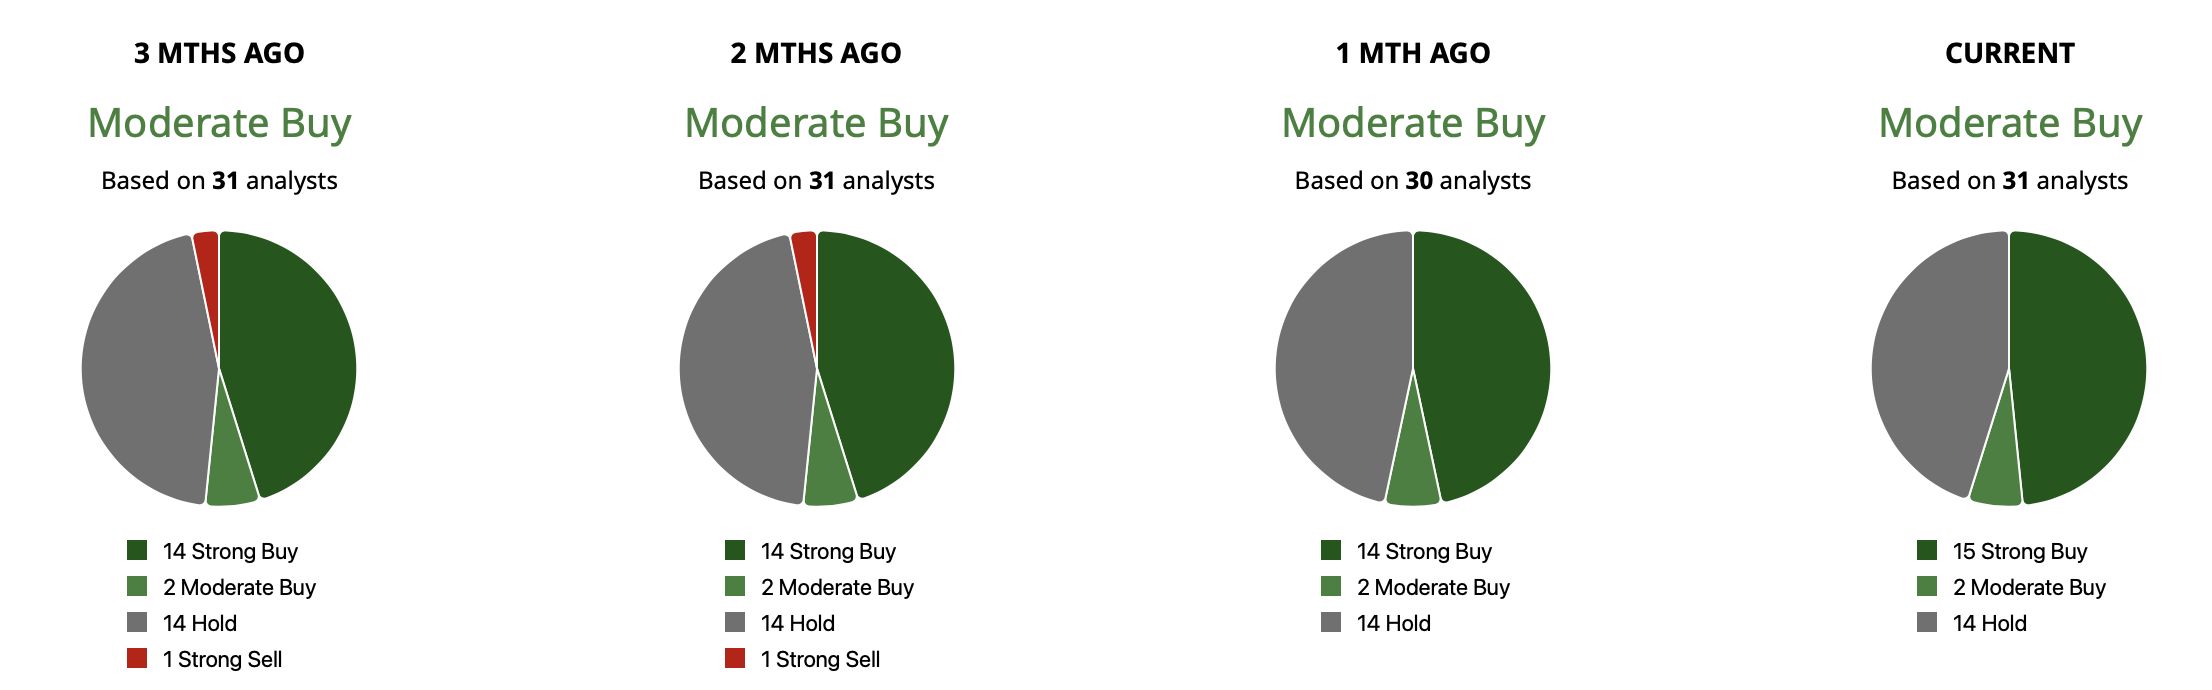
Overall, American Express has a consensus “Moderate Buy” rating on Wall Street. Of the 31 analysts covering AXP stock, 15 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and 14 have a “Hold” rating. The mean target price of $368.59 implies a potential upside of 13% from current levels. Meanwhile, its high-end price target of $450 implies potential upside of 38% from its current price of about $326.
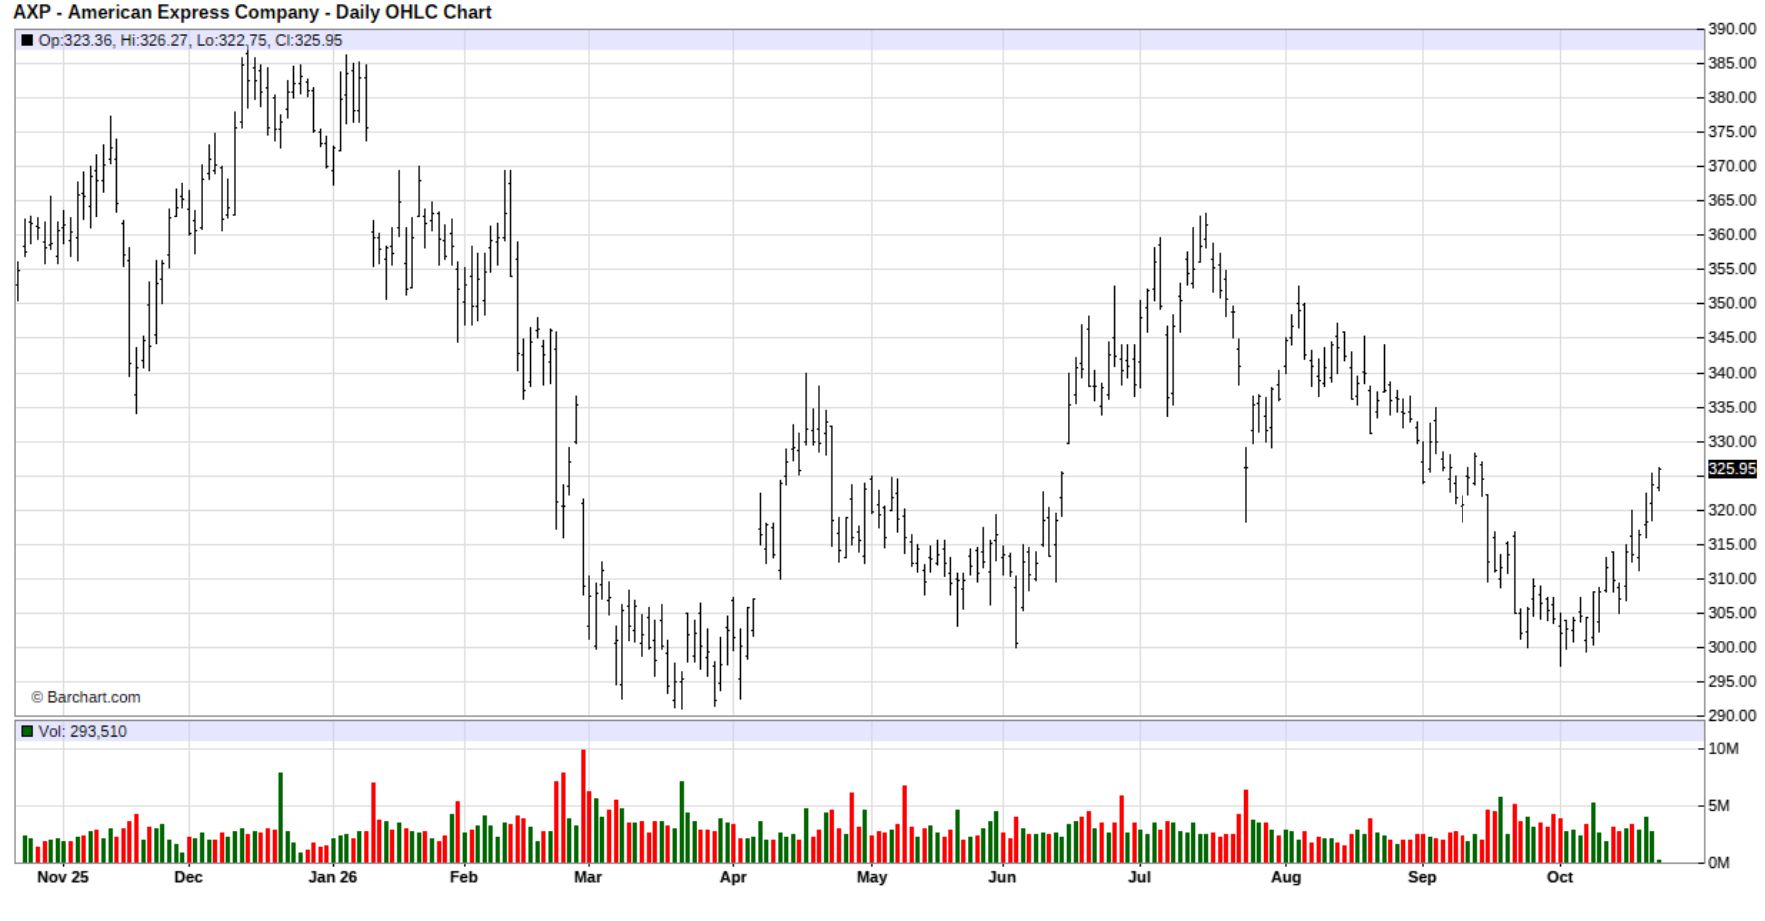
It also appears that AXP priced in a good deal of negativity. After dropping from about $360 to strong support at around $300, the stock is just starting to pivot higher. Last trading at $326, I’d like to see AXP rally back to $360 again long-term. In addition, analysts at BMO Capital Markets recently initiated coverage of the AXP stock with an outperform rating and a $380 price target. “We believe concerns around premium card competition and elevated reinvestment overlook a more important development; namely that AXP's premium ecosystem is still gaining scale as younger cohorts attach to fee-paying products, card-fee revenues compound, and management's reinvestment strategy delivers healthy returns,” said the research note, as quoted by Seeking Alpha.
 www.barchart.com
On the date of publication, Ian Cooper did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
INTC Stock Alert: What to Know as Intel Hits Construction Milestone at Ohio Fab Dear American Express Stock Fans, Mark Your Calendars for October 23 Why Deutsche Bank Wants You to Buy the Dip in CoreWeave Stock Dear Western Digital Stock Fans, Mark Your Calendars for October 22