

AppLovin (APP) has found itself in a place where no S&P 500 company wants to be. Over the past 52 weeks, the stock has performed the worst out of the index’s names. Investors have pressed it over slowing growth, although the adtech giant posted robust numbers in the first half of this year. Third-quarter earnings (to be reported on Nov. 4, after the market closes) are now in focus as the company is expected to benefit from an upgrade.
Gaming remains AppLovin’s largest revenue source, and its growth depends mainly on how well its advertising models perform. As models improve, advertisers can spend more profitably while meeting return-on-ad-spend targets, so their budgets increase. The company said the second quarter’s weaker results were due to timing, i.e., its models improved more slowly than usual, and the next major improvement came just after the quarter ended. Moreover, AppLovin did not report weakening advertiser demand.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
However, investors were not convinced. As a result, the upcoming Q3 results have become especially important for the company, as investors want to see the model improvements boost results.
About AppLovin Stock
AppLovin is a mobile advertising company based in Palo Alto, California. It helps app developers and businesses find new users, show ads, and earn money from their apps. Its technology uses AI to match ads with people likely to be interested, helping advertisers get better results. It has a massive market capitalization of $76.88 billion.
AppLovin’s stock fell 57% over the past 52 weeks as investors worried about slowing ad-model improvements, weaker earnings, and rising AI competition. Over the past six months, it has dropped 45%. AppLovin reached a 52-week low of $225.19 on Oct. 30, but is up 16% from that level.
On a forward-adjusted basis, APP stock trades at a price-to-earnings (non-GAAP) ratio of 13.74x, moderately higher than the industry average of 12.56x. However, this is lower than its 28.69x five-year average P/E ratio.
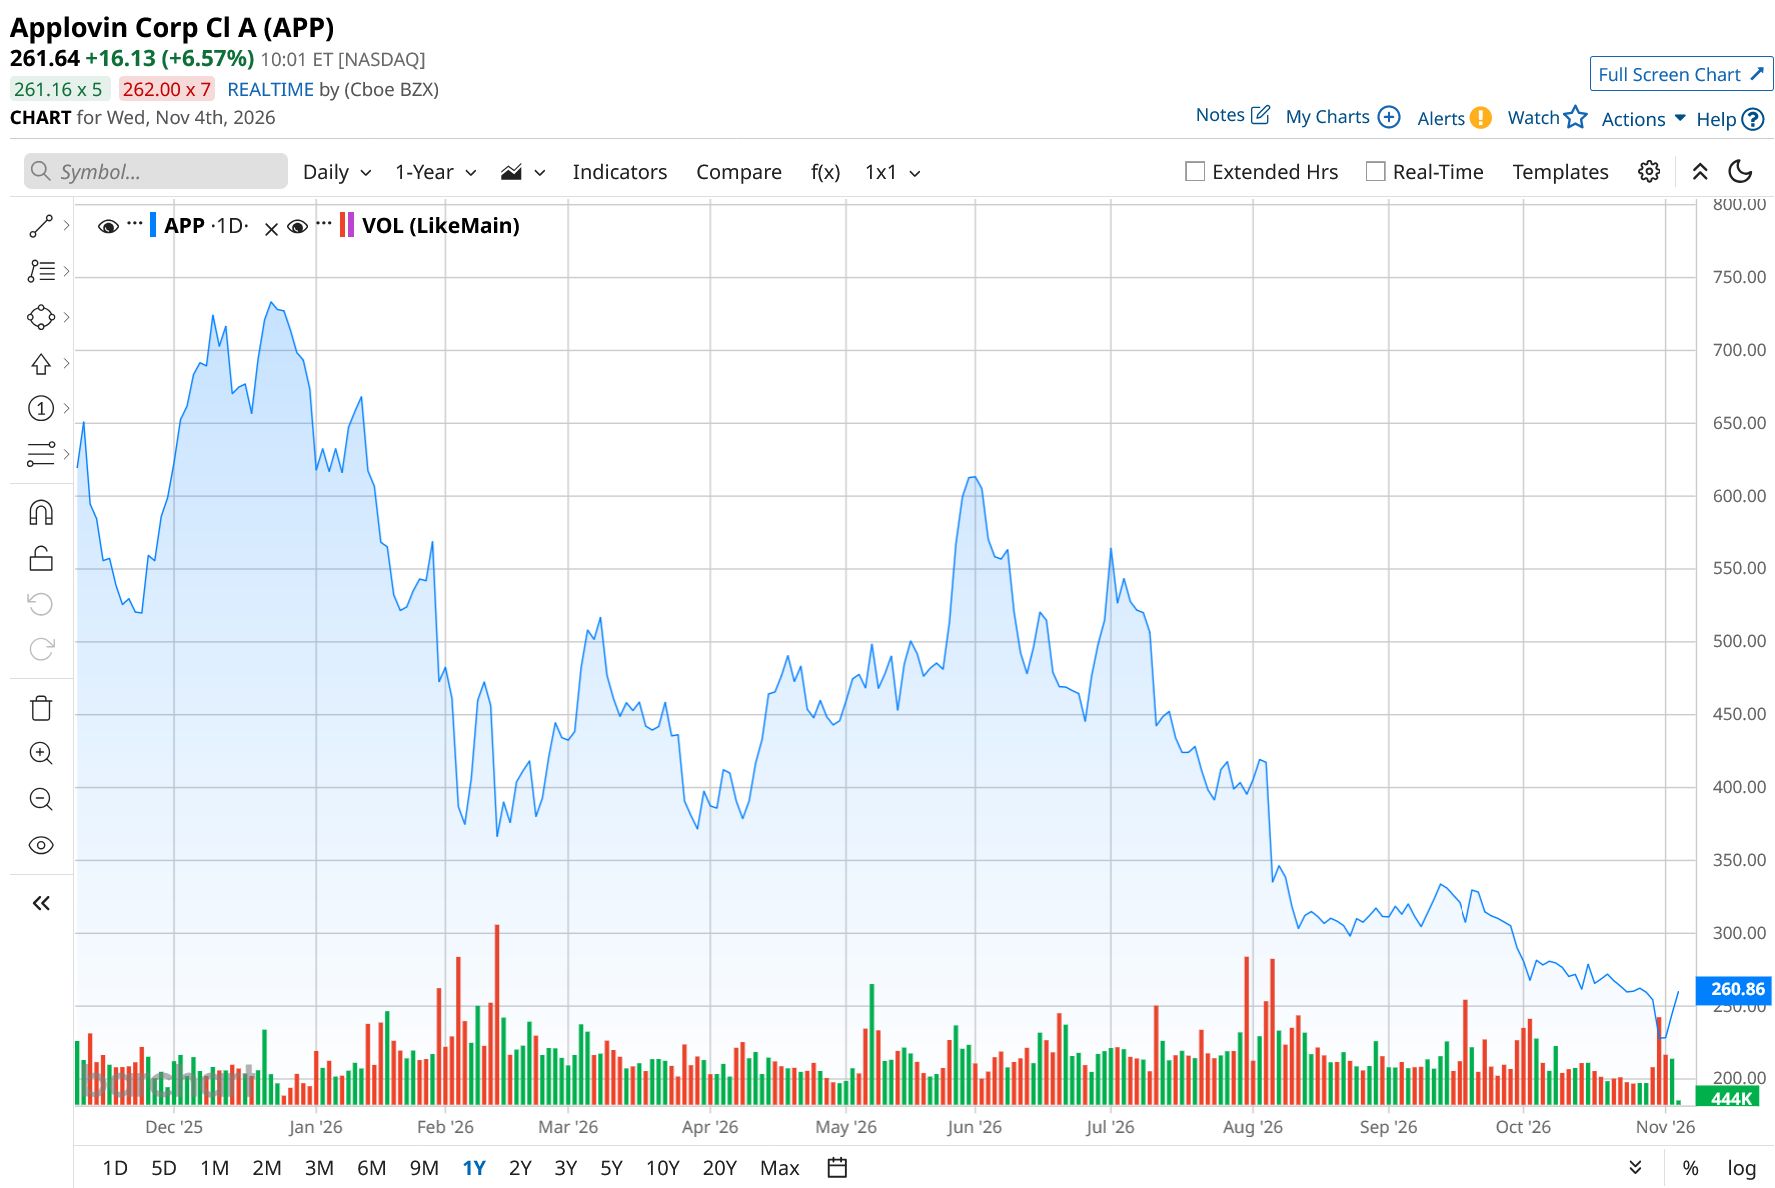 www.barchart.com
Missed Q2 Revenue Estimate on Slower Model Gains
AppLovin reported slower model gains in the second quarter, leading to revenue below the midpoint of its guidance range. The company’s topline rose 53% year-over-year (YoY) to $1.92 billion. Adjusted EBITDA increased by 58% from the prior-year period to $1.61 billion, just below its guided range.
On the brighter side, the company did not report a slowdown in advertiser demand. In fact, MAX publisher earnings rose by double digits quarter-over-quarter, while AppLovin’s share of publisher waterfalls stayed consistent. Advertiser spending reached another record, ending 28% higher than in Q4 2025, even though the fourth quarter is typically the seasonal peak for advertisers.
In the third quarter, AppLovin expects revenue of $2.06 billion to $2.09 billion, while adjusted EBITDA is projected to be $1.71 billion to $1.74 billion. Wall Street analysts are also robustly optimistic about the company’s bottom-line trajectory. For fiscal 2026, AppLovin’s EPS is expected to climb 55.5% YoY to $15.61, followed by a 25.8% improvement to $19.63 in fiscal 2027. For the about-to-be-reported third quarter, EPS is projected to rise 60.8% YOY to $3.94.
What Do Analysts Think About APP Stock?
Last month, analysts at RBC Capital maintained an “Outperform” rating on APP stock but lowered the price target from $575 to $500 as part of research on adtech names ahead of Q3 earnings. The company was set to post an 8% quarter-over-quarter revenue growth. However, investors’ concerns about competition and the total addressable market may be tough to address in one quarter.
UBS analysts maintained a “Buy” rating but lowered the price target from $790 to $410. Goldman Sachs analysts maintained a “Neutral” rating and cut the price target from $465 to $400.
AppLovin remains a popular name on Wall Street, with analysts awarding it a consensus “Strong Buy” rating overall. Of the 30 analysts rating APP stock, a majority of 21 analysts have given it a “Strong Buy” rating; two analysts gave a “Moderate Buy,” while seven analysts are taking the middle-of-the-road approach with a “Hold” rating. The consensus price target of $455.97 represents a 73% upside from current levels. Moreover, the Street-high price target of $710 indicates a 169% upside.
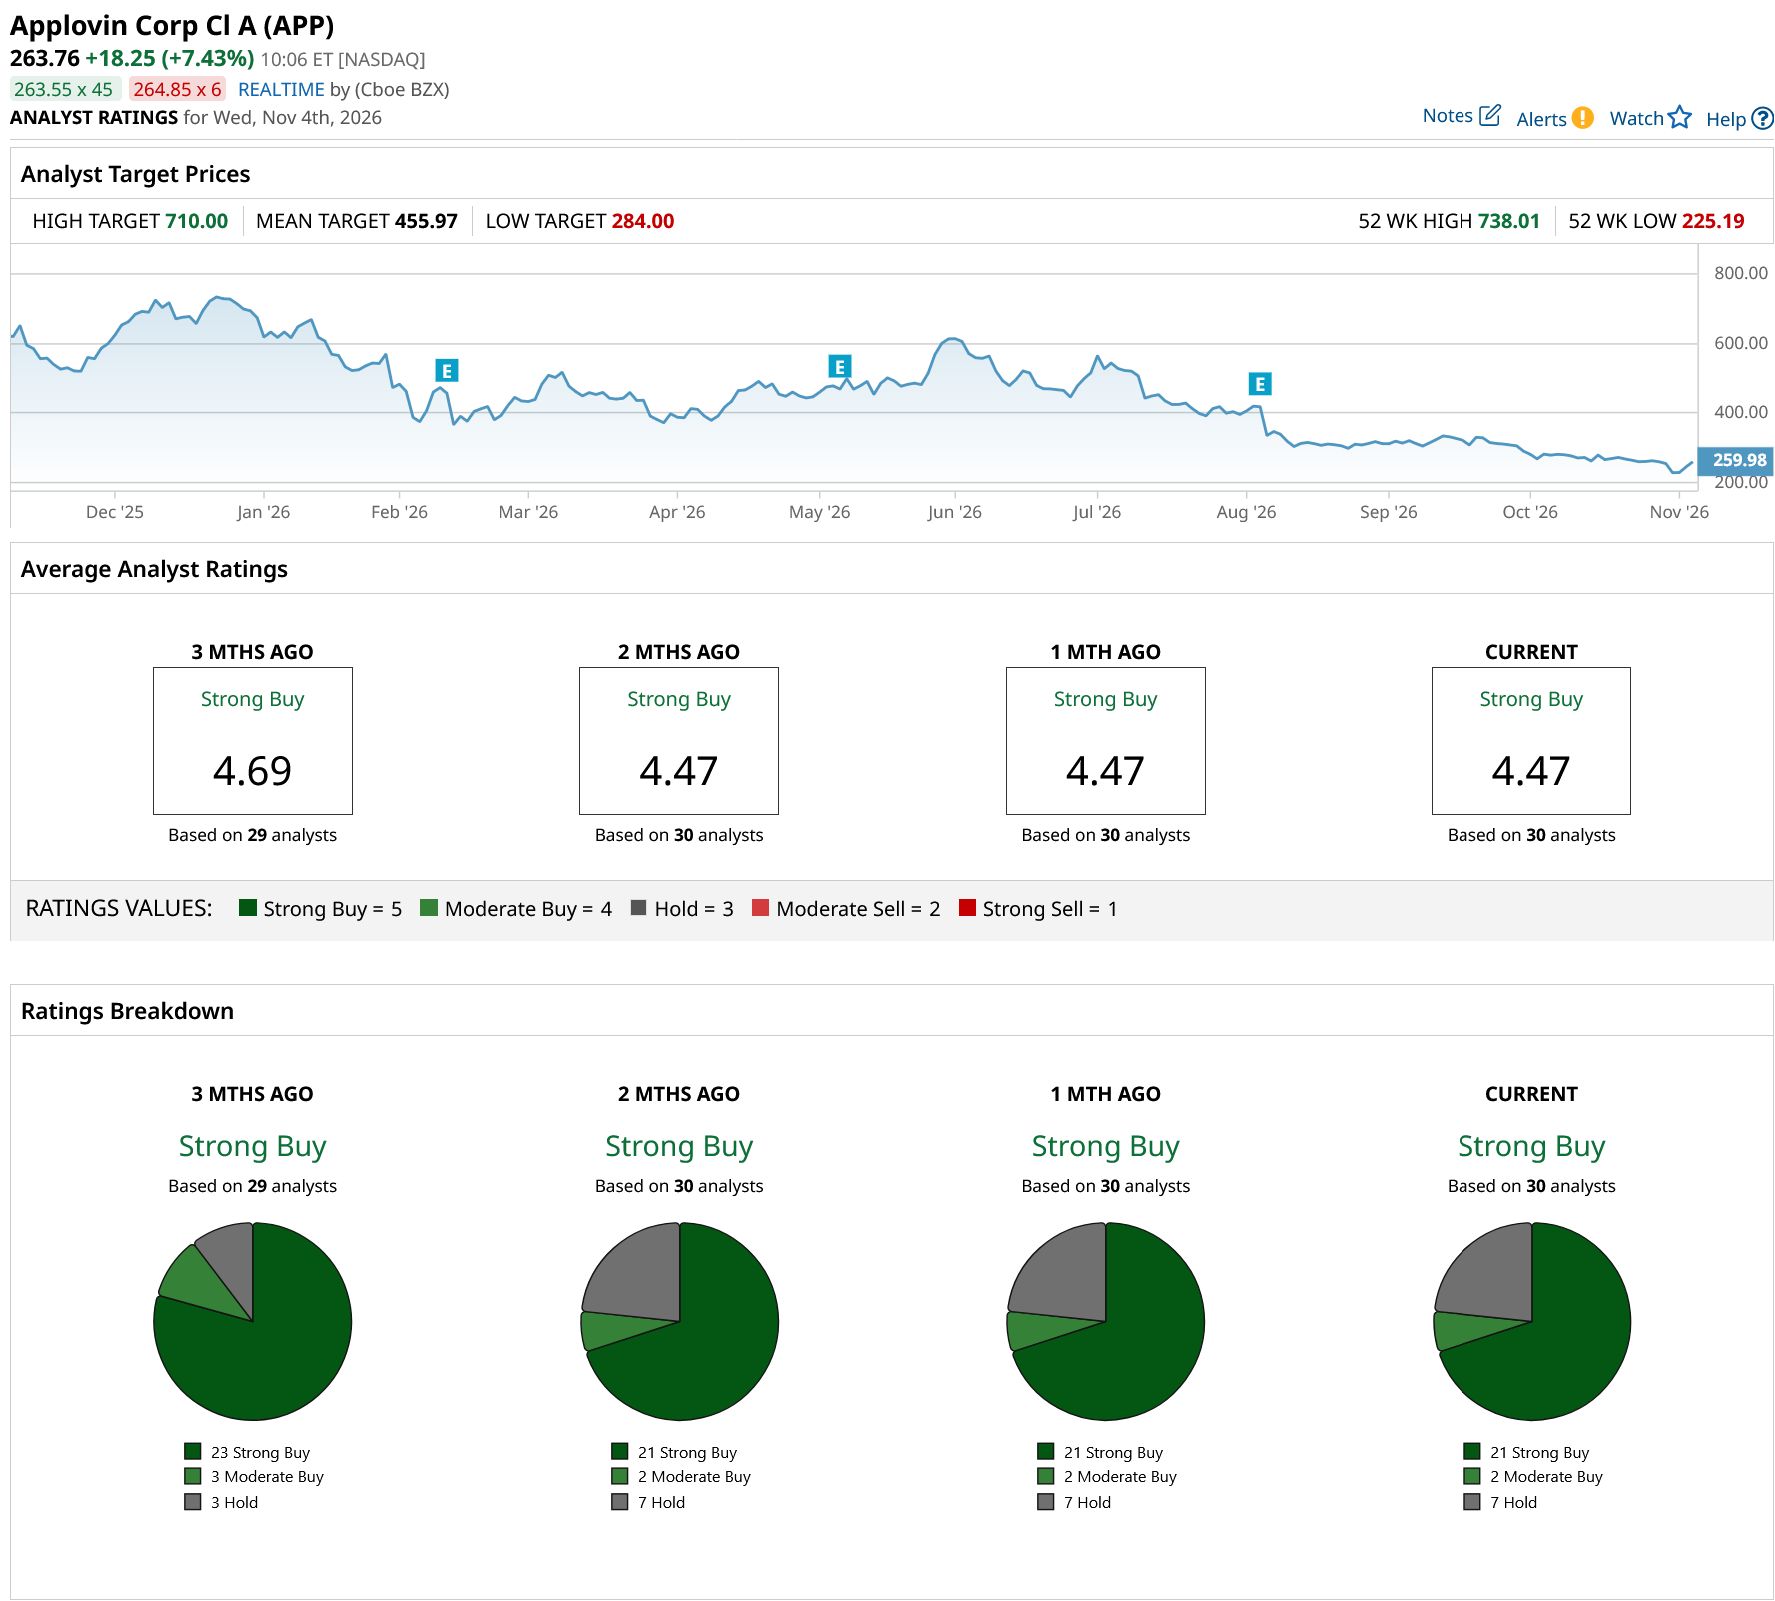 www.barchart.com
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear AppLovin Stock Fans, Mark Your Calendars for November 4 Coca-Cola Pays Warren Buffett’s Berkshire $848 Million a Year as Jim Cramer Says Buy KO Stock A Deep Correction in Nebius Stock Presents an Accumulation Opportunity as Financial Metrics Improve Why Piper Sandler Thinks You Should Buy Take-Two Stock Before November 19