

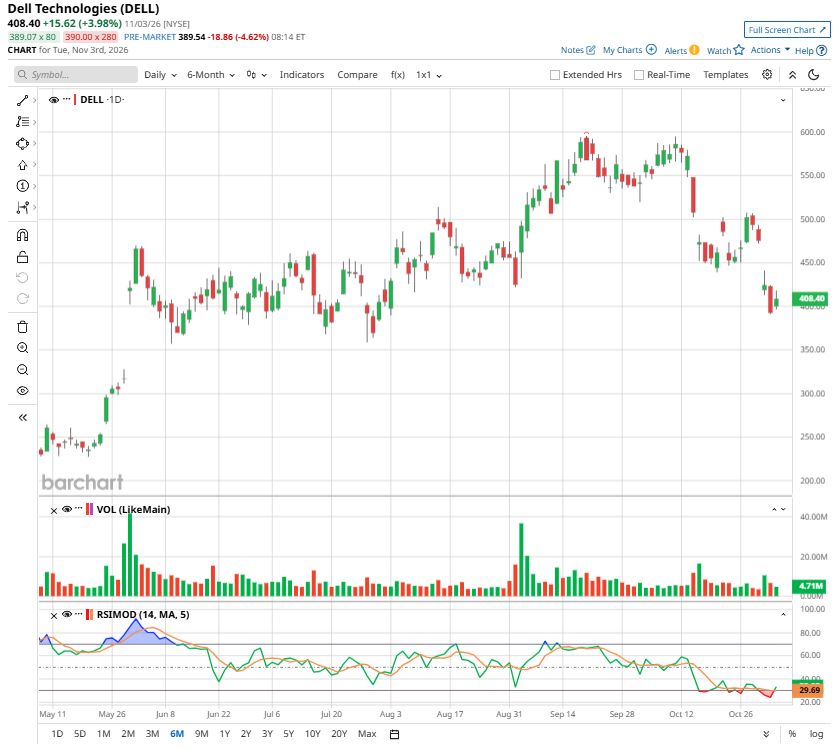
After a strong rally, Dell Technologies' (DELL) stock has corrected sharply, down more than 27% over the past month and trading about 31% below its 52-week peak. The sell-off reflects a shift in investor sentiment, driven by profit-taking and renewed concerns about near-term challenges in the PC market. These concerns have intensified following Intel’s (INTC) recent warnings about memory shortages and continued softness in PC demand.
Despite the challenges, Dell’s underlying fundamentals remain solid. Dell's massive $95 billion AI backlog and solid pipeline provide strong revenue visibility. Continued investment in AI infrastructure and sustained demand for data center solutions could support stronger growth in the quarters ahead.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
While Dell is expected to deliver solid growth, the decline in its share price has eased some of the valuation concerns.
 www.barchart.com
AI Infrastructure Demand Positions Dell for Sustained Growth
Despite emerging signs of weakness in the PC market, Dell appears well-positioned to sustain its growth momentum, supported by robust demand for AI infrastructure and traditional enterprise computing solutions. Dell reported second-quarter revenue of $47 billion, up 58% year-on-year, while earnings per share (EPS) surged 203% to $7.04.
AI infrastructure buildout is driving demand for its products and solutions. Dell secured a record $60.9 billion in AI-related orders and generated $16.4 billion in AI server revenue in Q2. Its AI backlog reached $95 billion at quarter-end, while the sales pipeline expanded sequentially and remained several times larger than the existing backlog.
Importantly, AI demand is expanding beyond a relatively narrow group of hyperscale customers. Neocloud providers, government-backed sovereign AI initiatives and enterprise customers are increasingly contributing to order growth. Dell's customer base has now exceeded 6,500, indicating broader adoption across customer segments. This diversification could improve the sustainability of its AI business by reducing reliance on a limited number of large-scale buyers.
Growth is also extending into Dell's traditional server business, where revenue increased 122% year over year. This performance reflects benefits from enterprises continuing to upgrade and modernize existing data center infrastructure and the growing adoption of AI and agentic applications.
Looking ahead, ongoing data center modernization and accelerating AI deployment are likely to drive infrastructure investment. Dell's presence across AI servers, traditional computing systems, networking, storage, and PCs provides multiple avenues to capture this investment cycle. Its broad portfolio also offers opportunities to deepen customer relationships through integrated infrastructure solutions, supporting both revenue growth and customer retention.
Management's outlook strengthens Dell’s investment appeal. Dell is projected to deliver stronger performance in the second half of the current fiscal year. For the third quarter, Dell expects revenue of $49 billion at the midpoint, representing year-over-year growth of around 80% and a notable acceleration from the second quarter's 58% expansion. The Infrastructure Solutions Group (ISG) is expected to remain the primary growth engine, with revenue projected to increase approximately 145%, supported by AI server revenue of $19 billion. This compares with 89% revenue growth in ISG during the second quarter, indicating that the infrastructure business is entering a period of substantially faster expansion.
Thanks to the solid top-line growth and operating leverage, Dell is also expected to deliver solid earnings growth. Analysts expect Dell to report earnings of $6.41 in Q3, up about 173% year over year.
Overall, Dell's growth outlook remains solid, making its stock attractive near the current levels.
Dell’s Pullback Offers an Attractive Entry Point
Dell’s recent pullback reflects near-term concerns about PC demand and memory shortages. Its $95 billion AI backlog, expanding customer base, and accelerating infrastructure demand provide strong revenue visibility and position the company to capitalize on sustained AI investment.
With management expecting a significant acceleration in growth in the second half of the fiscal year, the recent correction has improved the stock’s valuation appeal. While PC market weakness and supply constraints remain risks, Dell’s strong AI positioning and earnings growth outlook make the current pullback an attractive buying opportunity.
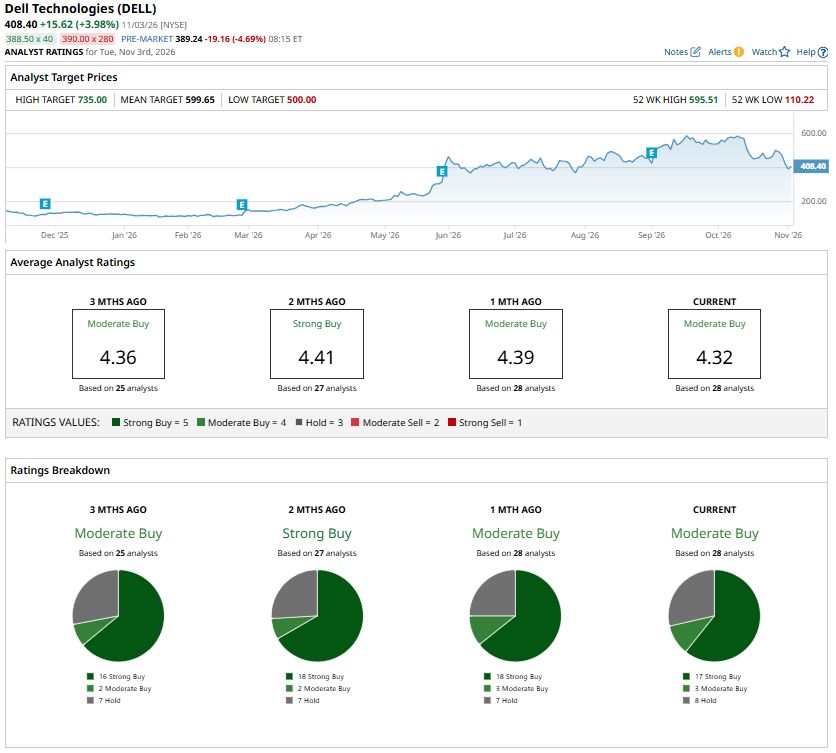
Although Dell stock carries a “Moderate Buy” consensus rating, most analysts maintain a “Strong Buy” recommendation.
 www.barchart.com
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘I Think That the Goal of the Bears Out There Is to Derail the Anthropic IPO’: Jim Cramer Warns as Amazon and Alphabet Slide KeyBanc Just Downgraded Vistra Stock. Here's Why. Short Straddle Screener Results for November 5th Nasdaq Futures Slip as Chip Selloff Rages On; Earnings and Fed Speak on Tap