

Google parent Alphabet (GOOG) (GOOGL) is caught in the crosshairs of Wall Street’s cooling artificial intelligence (AI) enthusiasm, with investors increasingly backing away from the trade that fueled some of the market’s biggest winners over the past few years. The pullback has hit Alphabet, too, with its shares in the red in 2026. Heavy AI spending, slowing search revenue growth, and negative free cash flow have only added to the pressure, giving investors more reasons to turn cautious.
But not everyone is turning bearish. Despite the growing concerns, Alphabet has earned a spot on HSBC's list of 11 stocks to consider amid the broader market selloff triggered by the AI trade reversal. HSBC analyst Paul Rossington sees plenty of upside in Google’s AI opportunity, pointing to strong Google Cloud demand, potential TPU sales growth, and fresh monetization opportunities across AI-powered Search. HSBC maintains a “Buy” rating on the stock with a $360 price target, implying approximately 23.1% upside from current levels.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
With AI sentiment taking a hit, could GOOG stock's pullback present an opportunity to buy the dip? Let's take a closer look.
About Google Stock
Google, owned by parent company Alphabet, is one of the world's largest technology companies, headquartered in Mountain View, California. Founded in 1998 by Larry Page and Sergey Brin, Google started as an internet search engine and has since evolved into a global technology powerhouse. Its offerings span Google Search, YouTube, Gmail, Google Maps, Google Chrome, Android, Google Play, and Google Workspace, alongside its growing cloud computing business, Google Cloud.
Through its diverse ecosystem of digital products and services, the company generates revenue primarily from advertising, subscriptions, software, and cloud services. Over the years, Google has also made artificial intelligence a central pillar of its growth strategy. Its AI journey includes research breakthroughs through Google DeepMind, the development of its Gemini family of models, and the integration of AI across Search, Workspace, Android, and Cloud.
The company is also investing heavily in its own AI infrastructure, including Tensor Processing Units (TPUs), which power its AI models and cloud services. With AI Overviews and AI Mode transforming the search experience, and Gemini expanding its reach across consumer and enterprise products, Google is positioning itself to capture a larger share of the rapidly growing AI market. However, Alphabet’s shares have come under significant pressure in 2026 as investors reassess the costs and potential returns of the AI boom.
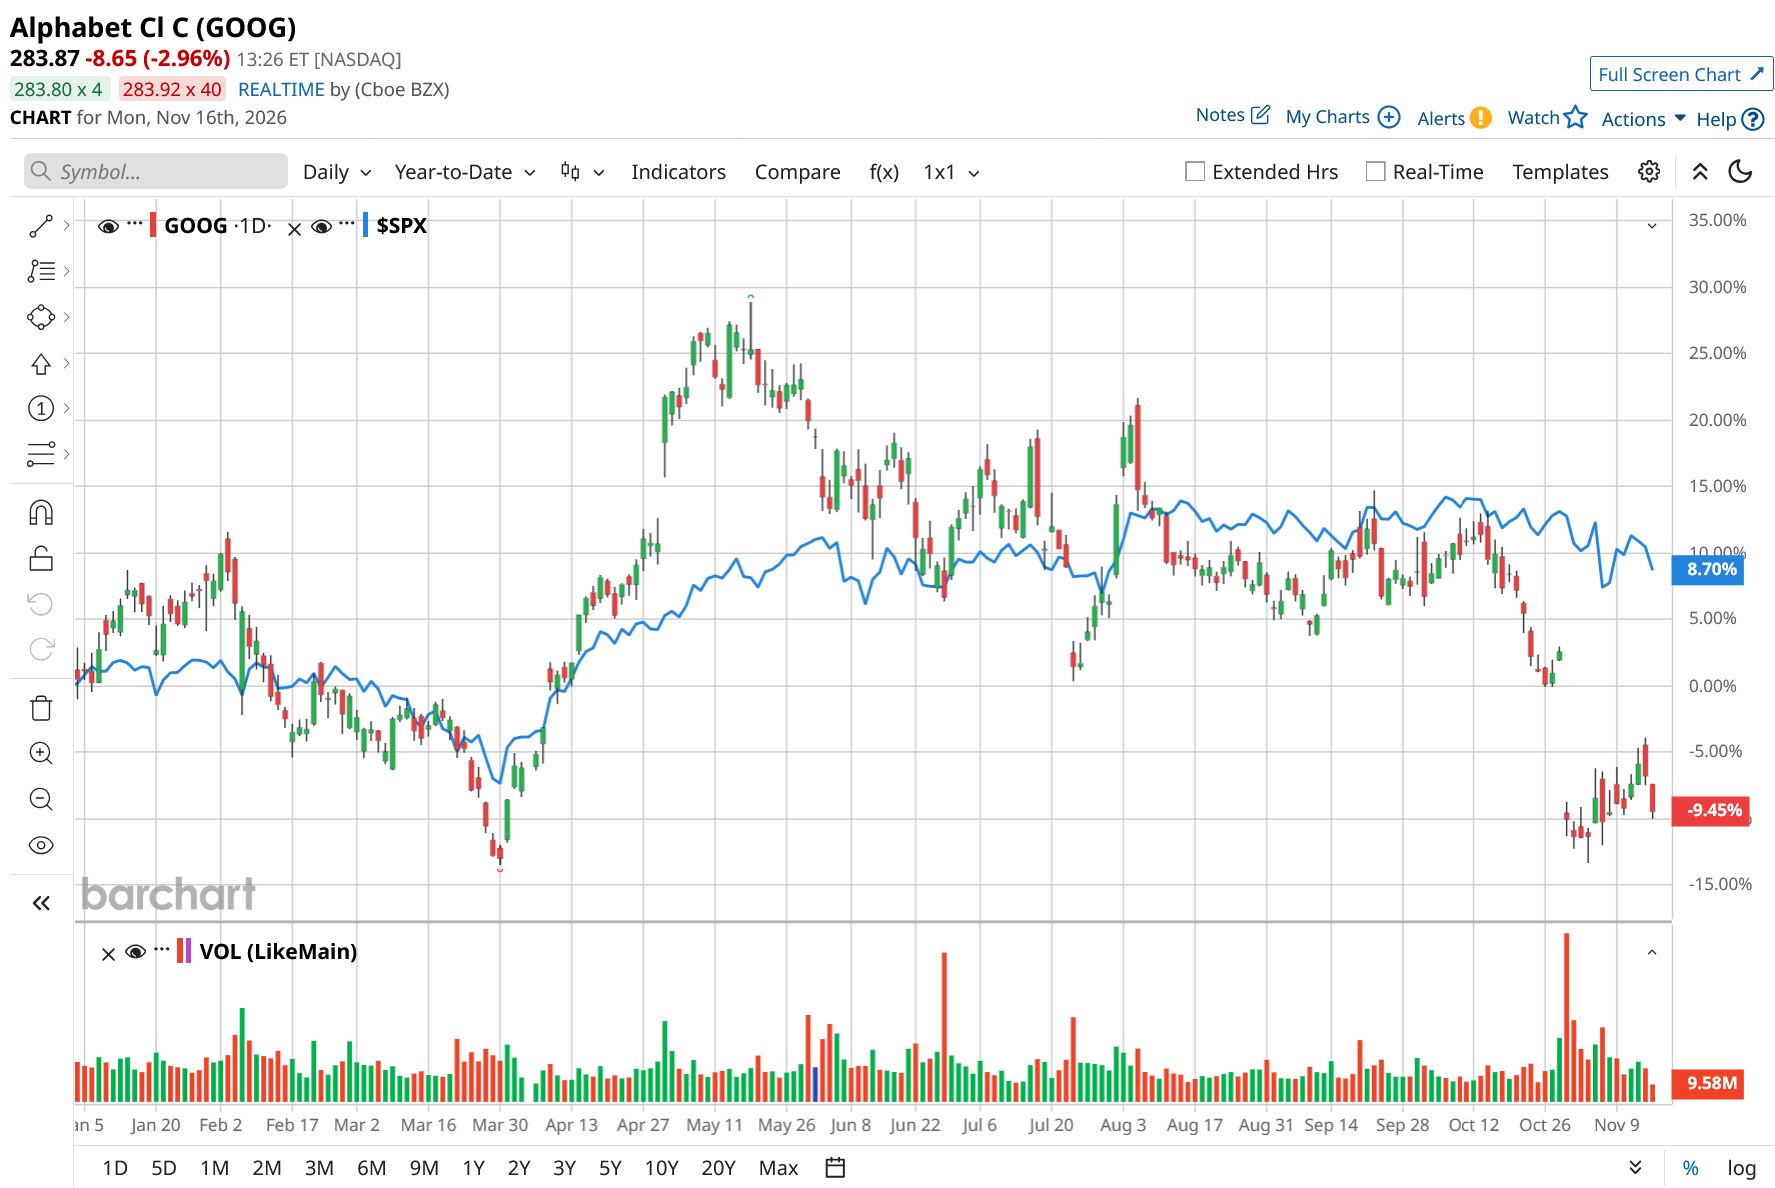
The pressure intensified after Alphabet's third-quarter earnings report in October, when the company missed Wall Street's revenue and advertising expectations and reported negative free cash flow. Currently carrying a market capitalization of approximately $3.59 trillion, GOOG stock has gained about 2.5% over the past year but is down 10% so far in 2026. That puts the stock well behind the broader S&P 500 Index ($SPX), which has climbed 10.6% over the past year and 8.9% in 2026. Even more striking, shares have plunged approximately 30% from their 52-week high of $404.47, reached in May.
 www.barchart.com
Q3 Earnings Snapshot
Alphabet delivered a mixed fiscal 2026 third-quarter performance on Oct. 28, marking its first top- and bottom-line miss in nearly four years. Despite solid revenue growth and an exceptional showing from Google Cloud, the tech giant fell short of Wall Street's expectations, while soaring AI infrastructure spending raised fresh questions about the returns on its massive investments. Investors reacted sharply, sending the stock tumbling nearly 12.3% on Oct. 29.
Consolidated revenue climbed 25% year-over-year (YoY) to $127.6 billion, marking the company's 13th consecutive quarter of double-digit revenue growth and reflecting strength across its business segments. However, the figure missed Wall Street's consensus estimate of $128.2 billion, taking some shine off an otherwise strong quarter.
The biggest standout was Google Cloud, which delivered a remarkable 103% YoY revenue surge to a record $30.71 billion, comfortably beating analyst expectations. The explosive growth was fueled by rising enterprise demand for AI infrastructure, Google's Tensor Processing Units (TPUs), and its broader suite of cloud-based solutions, highlighting the growing contribution of AI to the company's cloud business.
On the other hand, Google's core Search and other revenue showed signs of moderation, growing 12% to $63.35 billion and falling short of Wall Street estimates. Although AI is driving greater search activity, the slower growth in this key segment has raised questions about the pace of monetization and the resilience of Google's traditional advertising engine.
Meanwhile, Google’s AI momentum extends well beyond Cloud and Search. Its Gemini 4 Argon and Carbon models are gaining traction at the AI frontier, while its first-party model APIs are processing nearly 32 billion tokens per minute, more than four times the volume recorded a year earlier. The Gemini app has also crossed one billion users, becoming the fastest-growing product in the company's history. Adding to its subscription momentum, YouTube Music and Premium surpassed 150 million subscribers globally, including trial users.
However, Google's growing AI ambitions come with an increasingly hefty price tag. Capital expenditures surged to $51.36 billion in Q3, up sharply from $44.92 billion in the previous quarter and $23.95 billion in the year-ago period. As hyperscalers ramp up their AI infrastructure investments, investors are demanding tangible returns to justify these enormous spending commitments. The pressure was evident in Alphabet's cash flow, with quarterly free cash flow sinking further into negative territory at approximately $9.07 billion.
The bottom line offered little relief, either. Alphabet reported earnings per share (EPS) of $2.12, down from $2.87 in the year-ago quarter and well below analysts' expectations of $2.94. Despite the mounting investment burden, the tech giant retains a substantial financial cushion. It ended the quarter with $265.1 billion in cash and marketable securities, including $90.4 billion in marketable equity securities, against long-term debt of $125.1 billion.
Looking ahead, Alphabet has kept its full-year 2026 capital expenditure guidance unchanged at $195 billion to $205 billion, signaling that its massive AI infrastructure push is far from slowing down. More importantly, the company expects capital expenditure to increase significantly again in 2027, with further details expected during its fourth-quarter earnings call.
How Do Analysts View GOOG Stock?
Alphabet has recently earned a spot on HSBC's list of 11 stocks to consider amid the AI-driven market selloff, with analyst Paul Rossington highlighting the company's growing potential to turn AI investments into revenue. HSBC sees strong momentum in Google Cloud, backed by a sizeable order backlog, rising enterprise demand, and the prospect of meaningful TPU sales in 2027. Its in-house chip business also gives Alphabet another way to capitalize on the growing AI infrastructure boom.
Meanwhile, Google Services continues to provide the cash flow needed to fund its AI ambitions, while AI Overviews and AI Mode could open up fresh advertising opportunities by driving more search queries. Adding to the bullish case, Google’s latest AI model, Carbon, secured the highest intelligence score on Artificial Analysis, strengthening its competitive position in the AI race. HSBC believes these developments could support stronger AI monetization across Search and Cloud.
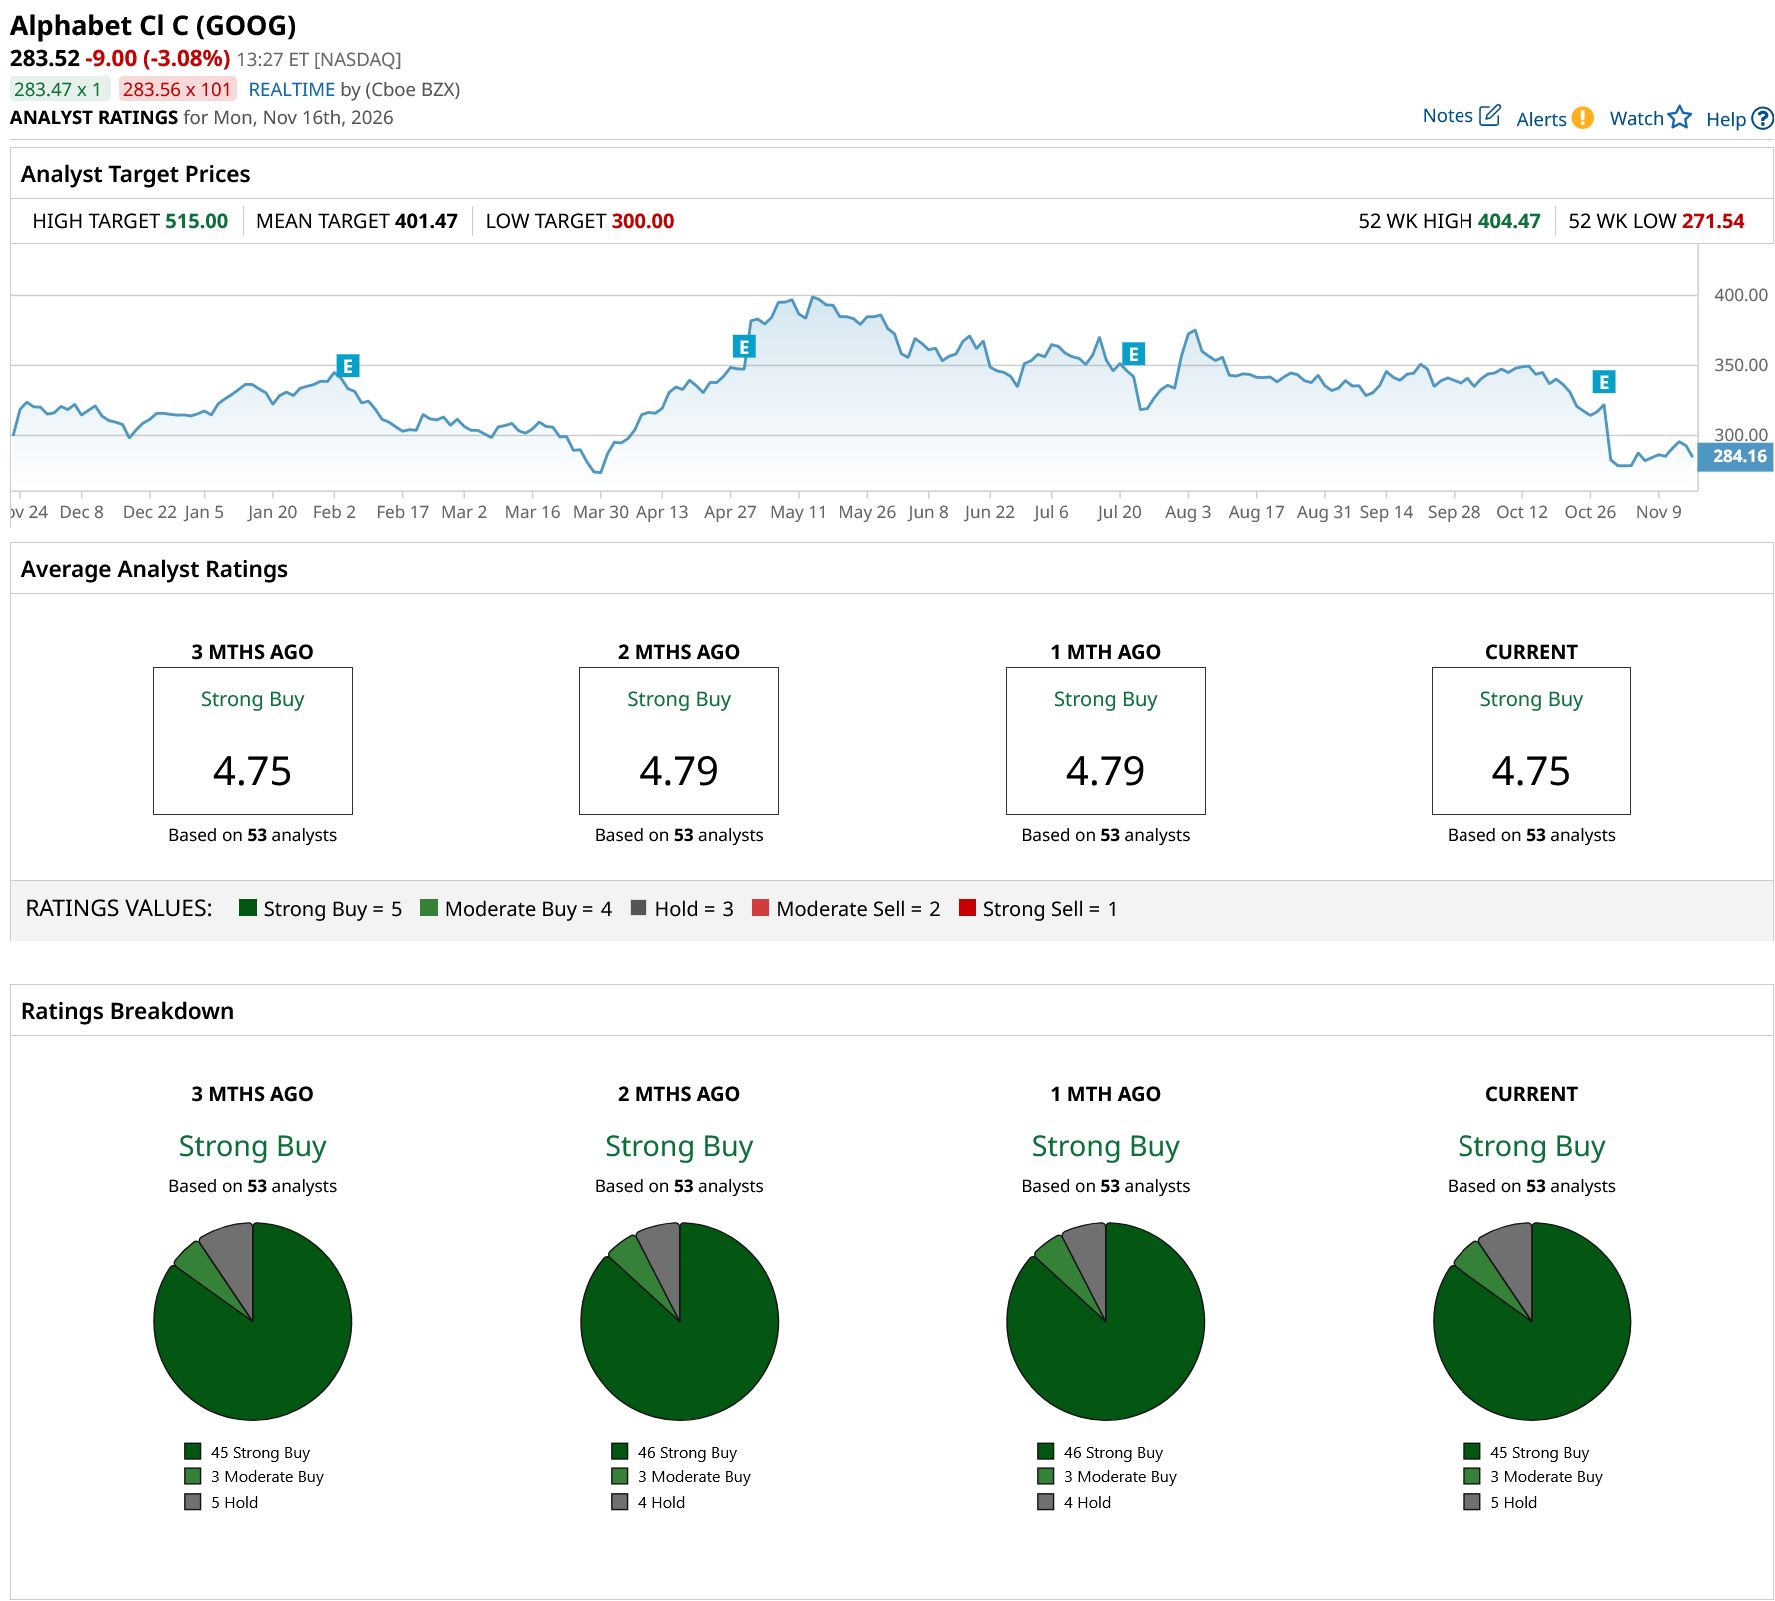
Despite the recent selloff, Wall Street hasn't lost faith in Alphabet. GOOG stock commands a consensus “Strong Buy” rating, with 45 of the 53 analysts covering it backing a “Strong Buy,” three assigning a “Moderate Buy,” and just five recommending “Hold.” The Street's average price target of $401.47 signals 41% upside potential, while its most bullish target of $515 points to a staggering 81% rally from current levels.
 www.barchart.com
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear MicroStrategy Stock Fans, Mark Your Calendars for November 30 Here’s Why Colette Kress Is Actually Nvidia’s Best Choice to Replace Jensen Huang Why HSBC Says You Should Buy Google Stock Right Now How CoreWeave Just Gave Nebius Stock a Major Lifeline