

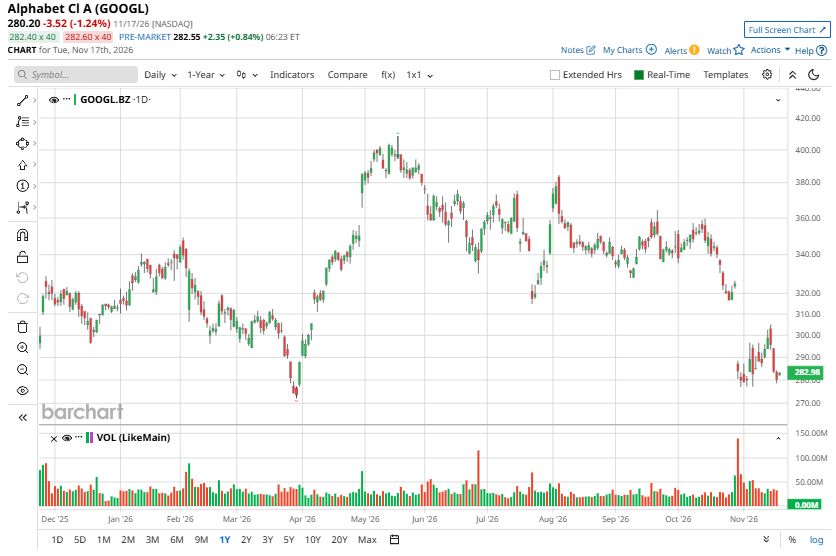
Alphabet (GOOG) (GOOGL) stock has taken a hit, falling nearly 17% over the past month and trading more than 30% below the 52-week high. The decline followed the tech giant’s third-quarter results, reflecting slower growth in Google Search and growing pressure on free cash flow.
A moderation in Search growth and negative free cash flow amid massive spending on Artificial Intelligence (AI) infrastructure has weighed on investors’ sentiment.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
However, the slowdown in Search growth may not be as concerning as it initially appears. In the second quarter, Google Search and other revenue grew 17%. In the third quarter, it moderated to 12%. This reflects tougher comparisons with the previous year. During its second-quarter earnings call, Alphabet’s management pointed out that Search growth had started accelerating in the third quarter of the prior year. This means the company is now comparing its results against a stronger performance, making it more difficult to sustain the same growth rates.
More importantly, Alphabet has multiple growth drivers that will support its performance in the coming quarters. Google Cloud is growing rapidly as businesses increasingly adopt AI tools and cloud infrastructure. Its advertising business also continues to provide a strong revenue base, while the Subscriptions, Platforms and Devices segment is helping diversify the company's revenue streams.
Of course, Alphabet's rising spending on AI and infrastructure cannot be overlooked. These investments are putting pressure on free cash flow, and investors will want to see clear evidence that the spending is translating into stronger revenue and earnings growth. However, Alphabet is monetizing its AI investments well. Moreover, Alphabet's valuation appears compelling.
 www.barchart.com
Growth Outlook Remains Strong
Alphabet's prospects remain solid despite slowdown concerns. Google Services could experience slower year-over-year (YoY) advertising growth in the fourth quarter as it laps strong spending associated with the U.S. presidential election in the prior-year period, particularly on YouTube. However, strong AI-driven engagement across Search and YouTube, strength in the cloud business, and solid subscriptions point to continued growth.
Google Cloud is expected to be a significant growth catalyst. In the third quarter, the segment’s revenue surged 103% YoY to $30.7 billion, accelerating from 82% growth in the previous quarter. The segment’s solid growth is driven by its integrated AI ecosystem. Its proprietary chips, advanced models, cloud infrastructure, cybersecurity tools, and agent-based solutions allow it to deliver a broader technology offering to enterprise customers. This integrated approach deepens customer relationships, encourages wider platform adoption, and increases switching costs.
With 18 product lines generating more than $1 billion in annual revenue each, Google Cloud has diverse sources of growth. Third-quarter momentum extended beyond AI applications, with strong contributions from core Google Cloud Platform (GCP) services and sales of its in-house Tensor Processing Units (TPUs).
Demand across GCP remains broad-based, spanning AI infrastructure powered by TPUs and GPUs, enterprise adoption of Gemini 2.5 and other proprietary models, and traditional cloud services such as computing, cybersecurity and data analytics.
Subscriptions provide another important growth driver. Revenue from Subscriptions, Platforms and Devices rose 21% YoY to $12.9 billion in the third quarter, supported by YouTube and Google One. Growing recurring revenue allows Alphabet to monetize its user base more effectively while reducing its dependence on advertising.
Overall, Alphabet is well-positioned to deliver solid growth led by resilient advertising demand, rapid cloud expansion, increasing AI adoption, and subscription growth. Although difficult YoY comparisons may temper near-term results, Google Cloud's accelerating momentum and broader AI ecosystem offer meaningful opportunities for sustained growth ahead.
Alphabet Stock's Valuation Offers an Attractive Entry Point
The recent correction in Alphabet’s share price has compressed its valuation, positioning the stock at a notable discount to both its historical trading multiples and major tech peers. At 14.9 times forward earnings, GOOGL stock appears relatively undervalued compared with other large-cap technology companies. Microsoft (MSFT), for instance, trades at 26.3 times forward earnings, while Amazon (AMZN) has a significantly higher multiple of 34.2 times.
While Alphabet's stock is trading cheaper than peers, it continues to benefit from robust expansion in its Google Cloud business, increasing contributions from subscription-based services, and higher AI-led engagement across Search and YouTube.
Its relatively modest forward P/E multiple and solid growth prospects indicate a buy.
GOOGL Stock: A Strong Buy
GOOGL stock's decline reflects near-term concerns over moderating Search growth and elevated AI-related capital expenditures. However, its growth prospects remain solid. Google Cloud’s accelerating momentum, AI monetization opportunities, resilient advertising business, and growing subscription revenue provide multiple avenues for sustained growth.
While rising infrastructure spending could weigh on free cash flow in the near term, Alphabet’s ability to convert these investments into revenue and earnings growth remains encouraging. At 14.9 times forward earnings, GOOGL stock’s valuation appears attractive relative to its growth opportunities and major technology peers.
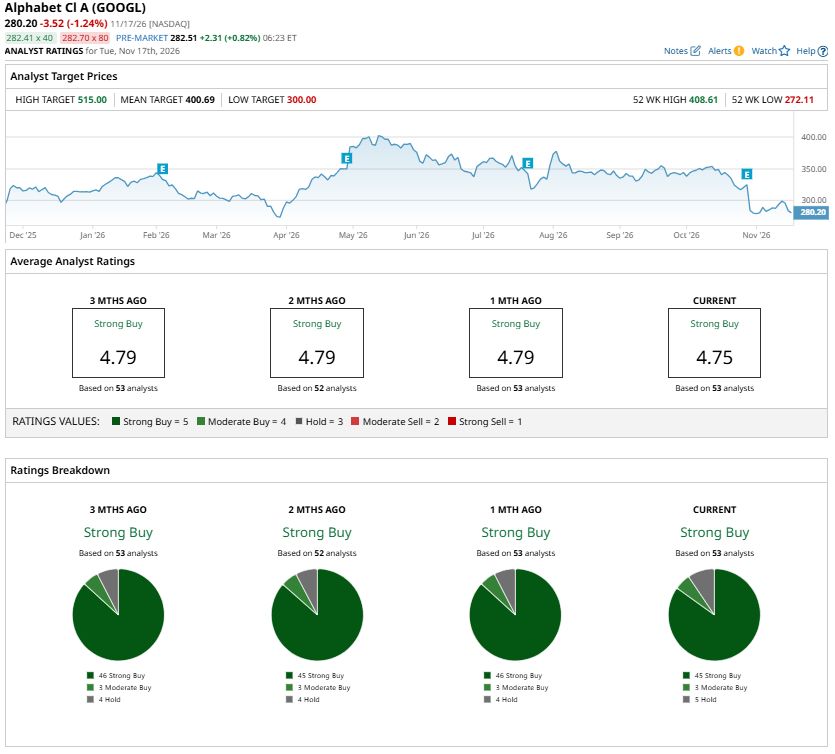
Overall, Alphabet’s strong competitive positioning, diversified revenue streams, and long-term AI opportunities support a positive investment outlook. Analysts’ sentiment for GOOGL stock remains favorable, with most analysts assigning a “Strong Buy” rating.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
I Used This Options Strategy to Profit from the Post-IPO Plunge in SpaceX. Now I’ll Use It Again on ANT Stock After Anthropic Starts Trading. Alphabet Stock Is Falling. Here’s Why Investors Should Be Buying the Dip. Dear Nvidia Stock Fans, Mark Your Calendars for December 1 Ahead of Intuit Earnings, Here's What Barchart Data Says Comes Next for INTU Stock