

CoStar Group, Inc. (CSGP), headquartered in Arlington, Virginia, provides information, analytics, and online marketplace services. Valued at $12 billion by market cap, the company offers a subscription-based integrated platform for commercial real estate intelligence, which includes information about commercial real estate properties, properties for sale, comparable sales, tenants, space available for lease, industry news, and market status.
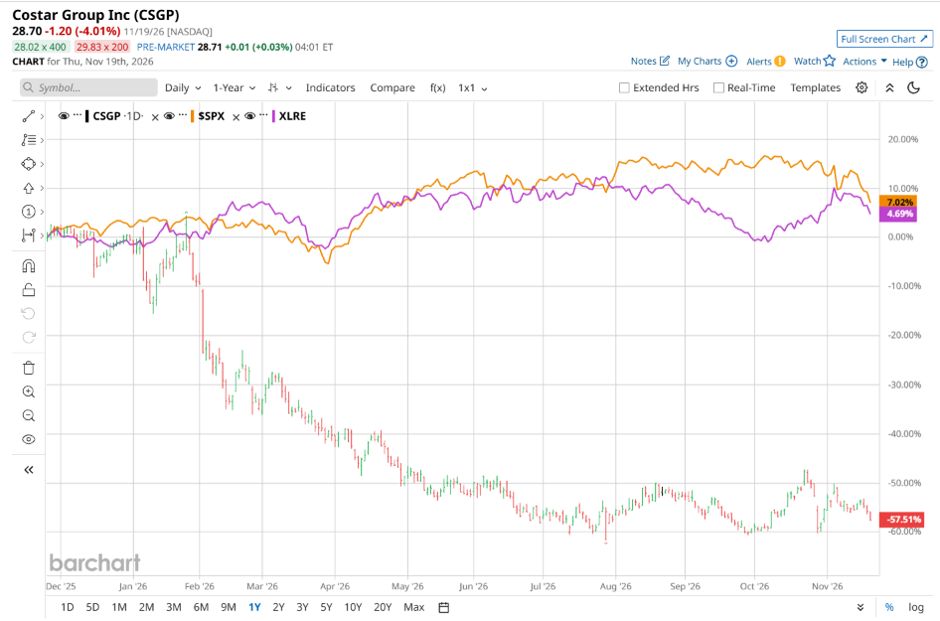
Shares of this leading commercial real estate information and marketplace listing platforms provider have considerably underperformed the broader market over the past year. CSGP has declined 56.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8%. In 2026, CSGP stock is down 57.3%, compared to the SPX’s 4.8% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, CSGP’s underperformance is also apparent compared to the State Street Real Estate Select Sector SPDR ETF (XLRE). The exchange-traded fund has gained about 5.9% over the past year. Moreover, the ETF’s 6.3% returns on a YTD basis outshine CSGP’s double-digit losses over the same time frame.
 www.barchart.com
CSGP’s underperformance stemmed from slower-than-expected net new bookings, coming in at $37 million in Q3, driven by macro headwinds and reduced sales capacity, particularly inside sales affecting Apartments.com and Homes.com.
On Oct. 28, CSGP shares plunged 14% after reporting its Q3 results. Its adjusted EPS of $0.38 beat Wall Street expectations of $0.34. The company’s revenue was $952 million, topping Wall Street forecasts of $951 million. CSGP expects full-year adjusted EPS in the range of $1.38 to $1.41, and revenue ranging from $3.75 billion to $3.77 billion.
For the current fiscal year, ending in December, analysts expect CSGP’s EPS to decline 9.3% to $0.49 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
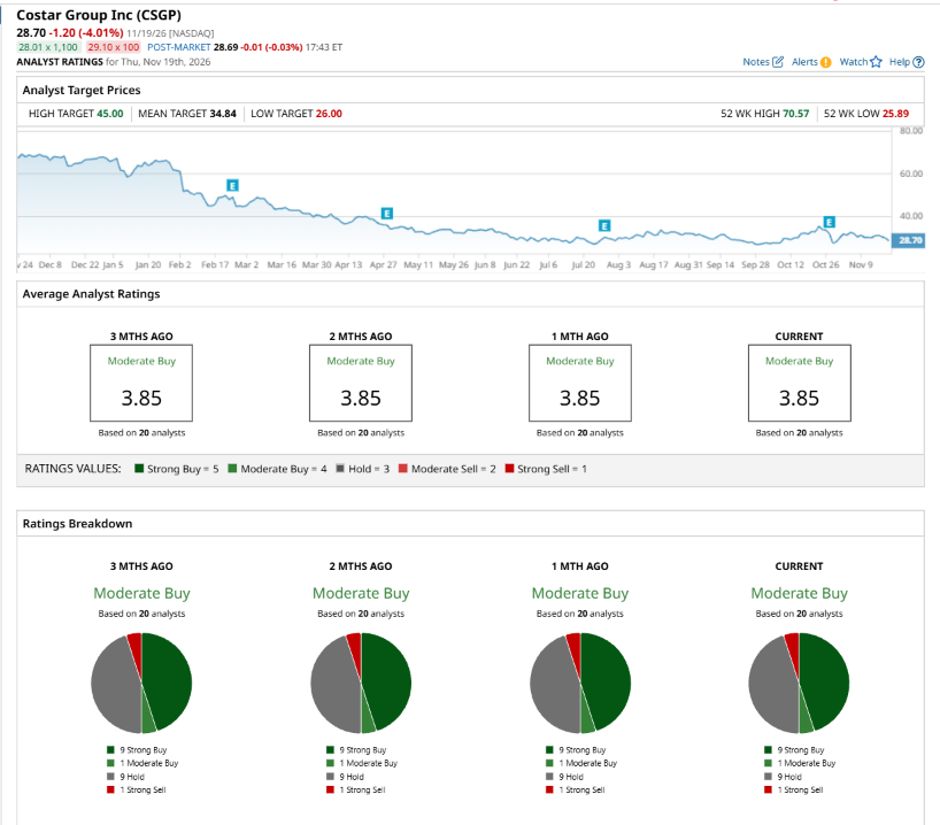
Among the 20 analysts covering CSGP stock, the consensus is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, one “Moderate Buy,” nine “Holds,” and one “Strong Sell.”
 www.barchart.com
The configuration has been consistent over the past three months.
On Oct. 29, BMO Capital analyst Jeffrey Silber maintained a “Hold” rating on CSGP and set a price target of $33, implying a notable potential upside of 15% from current levels.
The mean price target of $34.84 represents a 21.4% premium to CSGP’s current price levels. The Street-high price target of $45 suggests an ambitious upside potential of 56.8%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Disney Just Boosted Its Dividend by 33%. That Gives DIS Stock Investors a Real Reason to Stick Around. The Worst Might Be Over for Somnigroup as Credit Metrics Improve HSBC Just Turned Bullish on Cisco Stock Again. Here’s Why It Expects 40% Upside. Paul Tudor Jones’ Initiates a New Position in This Profitable Midcap Tech Stock