

Best Buy Co., Inc. BBY has a stronger earnings setup, but investors must weigh that improvement against a valuation above its historical norm. Higher guidance, positive estimate revisions and stronger cash generation support further progress.
Memory-cost inflation, promotion-sensitive consumers and a forward multiple above its five-year median keep the risk-reward balance from becoming one-sided. Better fundamentals now have to justify a higher price.
Best Buy Co., Inc. Price, Consensus and EPS Surprise
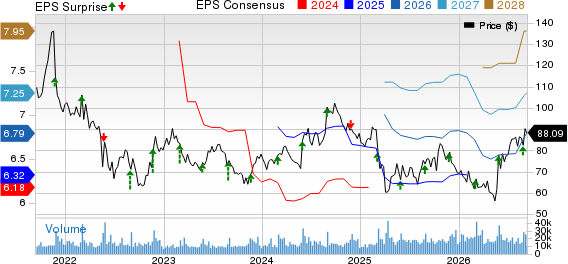
Best Buy Co., Inc. price-consensus-eps-surprise-chart | Best Buy Co., Inc. Quote
BBY's Earnings Picture Is Improving
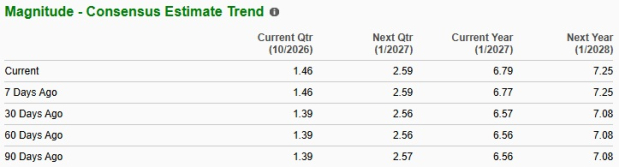
The Zacks Consensus Estimate for fiscal 2027 earnings is $6.79 per share, above $6.43 in fiscal 2026. The fiscal 2027 earnings estimate has moved 3.8% higher over the past four weeks.
BBY's latest quarterly earnings surprise was 7.3%. That result adds to recent estimate momentum and strengthens the case that the earnings trajectory is improving.
Image Source: Zacks Investment Research
Best Buy's Higher Guidance Raises the Earnings Bar
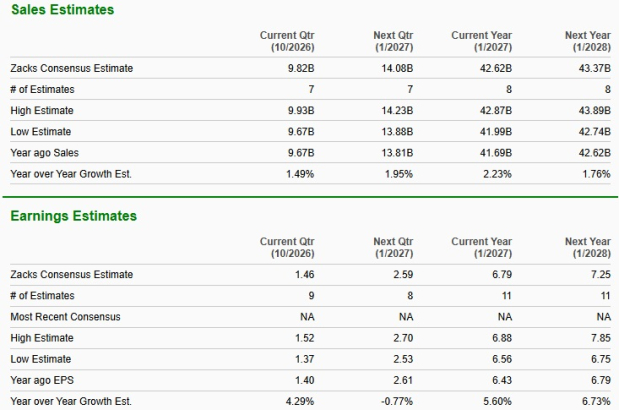
Best Buy raised fiscal 2027 revenue guidance to $42.3-$42.8 billion and adjusted earnings guidance to $6.70-$6.90 per share. Comparable sales are now expected to increase 1.9-3%, versus the prior outlook ranging from a 1% decline to 1% growth.
The higher outlook reflects first-half performance and momentum entering the second half. It also raises the execution bar because expectations for the fiscal year have improved.
Image Source: Zacks Investment Research
BBY's Valuation Now Sits Above Its Five-Year Median
BBY trades at 12.5X forward 12-month earnings, above its five-year median of 11.5X. The multiple remains within its five-year range of 7.0X to 15.5X, but the stock is no longer below its historical midpoint.
The PEG ratio stands at 2.10. Continued earnings and margin progress could support the multiple, but a setback would leave less valuation cushion.
Best Buy Still Faces Demand and Margin Risks
Industry-wide memory cost increases are lifting computing prices. In the second quarter, computing average selling prices rose in the mid-teens while unit volumes fell in the high single digits, showing sensitivity to higher price points.
Consumers remain value-focused and attracted to sales events, while appliance improvement still requires pricing and service investments. The annual adjusted SG&A rate is planned to increase about 20 basis points, which could limit margin upside.
Target Corporation TGT reported 3.8% second-quarter comparable sales growth and said it had lowered prices on more than 10,000 frequently purchased items over the past year. That emphasis on value reinforces the promotional backdrop across retail.
Walmart Inc. WMT reported 23% global e-commerce growth in its latest quarter and highlighted price, speed and convenience as customer priorities. Its continued price investments underscore the competitive standard for omnichannel retailers.
BBY's Cash Flow and Yield Add Defensive Support
Best Buy generated $1.30 billion of operating cash flow in the first half, up from $783 million a year earlier. Cash and cash equivalents reached $2.26 billion at quarter-end compared with $1.46 billion a year ago.
BBY's dividend yield is about 4.4%, while the company continues to expect approximately $300 million of fiscal 2027 share repurchases. That cash return profile adds support as the operating recovery develops.
BBY's Hold Signal Balances Strong Style Scores
The bottom line is that BBY's earnings outlook has improved, but the valuation no longer offers the same historical discount. Better estimates, higher guidance and cash flow support the shares, while memory inflation and a higher multiple argue for a measured entry stance.
The stock currently carries a Zacks Rank #3 (Hold). BBY also has a Value Score of A, a Growth Score of A, a Momentum Score of A and a VGM Score of A. Those favorable grades complement rather than override the Zacks Rank, supporting a balanced near-term view instead of an outright buy signal. You can see the complete list of today’s Zacks #1 (Strong Buy) Rank stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Best Buy Co., Inc. (BBY): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Walmart Inc. (WMT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).