

Shares of Huntington Bancshares Incorporated HBAN lost nearly 5.6% in yesterday’s trading session as the company trimmed its 2026 revenue outlook and lowered its 2027 earnings target, amid a changing interest-rate environment. Speaking at the Barclays 24th Annual Global Financial Services Conference, management indicated that the operating environment has become materially more challenging than anticipated at the start of 2026.
For 2026, Huntington now expects net interest income (NII) growth of roughly 35% from the 2025 baseline of $6.06 billion, down from its prior projection of 39-43%. Consequently, implied revenue growth is now expected to be approximately 34% compared with the earlier forecast of about 37%. Meanwhile, average loan growth is still projected at roughly 36% compared with the prior 36-37% range, while average deposit growth is expected at around 33% compared with the previous 33-34% outlook.
The downward revision to NII reflects changing market dynamics. Huntington noted that short-term interest rates have remained higher than initially anticipated, while competitive pricing for loans and deposits has intensified. These factors are elevating deposit costs and limiting net interest margin expansion. Management also cited lower-than-expected loan volumes, including higher paydowns in commercial real estate and residential portfolios and lower auto production as risk-adjusted returns became less attractive.
Despite the NII pressure, fee income remains a bright spot. Huntington now expects noninterest income to grow approximately 32% year over year, toward the upper end of its prior 31-33% range. The company has seen significant organic growth across these businesses, including strong capital-markets activity, expanding wealth assets and higher commercial payments revenues.
On expenses, Huntington continues to expect core expense growth of 32.5-33.5%. Net charge-offs are projected to be 25-35 basis points, while the effective tax rate has been revised to approximately 18% from the prior 19-20% range. Average shares outstanding are expected to be around 2 billion.
Weaker loan growth and a flatter NIM outlook have prompted Huntington to cut its 2027 adjusted EPS target to $1.75-$1.83 from $1.90-$1.93. The outlook assumes 6%-8% loan growth, NIM in the low-to-high 3.20% range, high-single-digit to low-double-digit fee-income growth and at least 300 bps of operating leverage, rising to 400-500 bps under the stronger growth scenario.
Overall, Huntington’s revised 2026 outlook points to continued strong operating growth but a more challenging spread-income environment. Resilient loan and deposit growth, accelerating fee income and acquisition synergies should provide support, while persistently high deposit costs, competitive loan pricing and slower loan production are likely to constrain NII growth and margin expansion through the remainder of the year.
Other Banks 2026 Outlook
KeyCorp KEY and Citizens Financial Group CFG also updated their 2026 outlooks at the same conference, providing further insight into the changing revenue, loan growth and margin environment for regional banks.
KeyCorp raised its 2026 revenue growth outlook to approximately 8% from the previous 7-8% range, supported by solid client activity, loan growth and momentum across fee-based businesses. The company now expects NII to increase 9-11%, while average loans are projected to grow 4-5%. KeyCorp also raised its noninterest income growth outlook to 4-5% from 3-4% and expects adjusted noninterest expenses to rise approximately 4%. Meanwhile, average commercial loans are expected to grow 8-10% in 2026.
Citizens Financial expects 2026 revenue growth to benefit from NII growth above its initial 10-12% target, while fee income and loan growth are tracking toward the upper ends of their respective 6-8% and 3-5% ranges. Investments in technology, digital capabilities and AI are aimed at improving customer retention, deepening product relationships and boosting efficiency. Citizens Financial expects expenses to rise approximately 4.5% in 2026, while maintaining a mid-50% efficiency ratio.
HBAN’s Price Performance & Zacks Rank
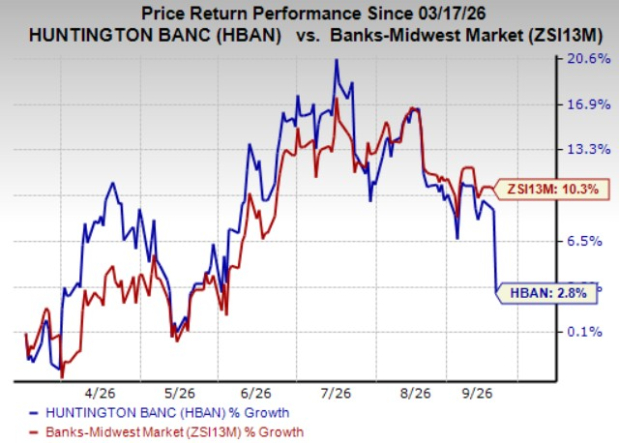
Shares of the company have gained 2.8% in the past six months compared with the industry’s rise of 10.3%.
Image Source: Zacks Investment Research
Huntington’s currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Huntington Bancshares Incorporated (HBAN): Free Stock Analysis Report
KeyCorp (KEY): Free Stock Analysis Report
Citizens Financial Group, Inc. (CFG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).