

Semiconductor equipment suppliers remain tied to chipmakers’ capital spending, production activity and technology transitions, while demand for testing, packaging and wafer-processing solutions continues to support activity across the industry. Against this backdrop, Trio-Tech International TRT and Amtech Systems, Inc. ASYS are two companies serving the semiconductor manufacturing market. TRT provides reliability test equipment and testing services, with operations spanning semiconductor back-end solutions and industrial electronics. Its offerings include burn-in and reliability test equipment as well as other test and process equipment. ASYS provides equipment, consumables and services used in semiconductor device packaging, wafer production and device fabrication, with operations covering thermal-processing and semiconductor-fabrication solutions.
While both companies operate within the broader semiconductor equipment space, Trio-Tech is more testing- and reliability-oriented, while Amtech is more focused on fabrication and processing solutions. These differences in business focus create distinct investment profiles, raising the question: which company is better positioned to create long-term shareholder value? Let’s take a closer look.
Stock Performance & Valuation: TRT vs. ASYS
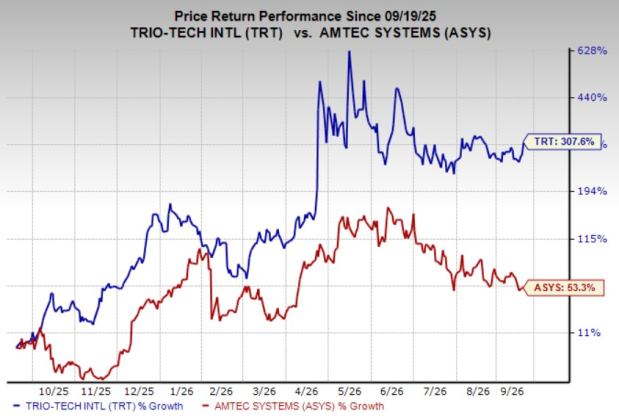
TRT (down 29.1%) has outperformed ASYS (down 37.1%) over the past three months. In the past year, Trio-Tech stock has surged 307.6% compared with Amtech stock’s rally of 53.3%.
Image Source: Zacks Investment Research
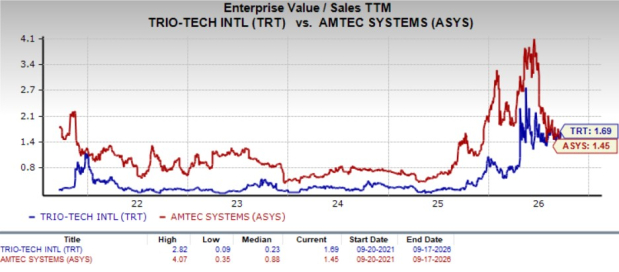
Meanwhile, TRT is trading at a trailing 12-month enterprise value-to-sales (EV/S) ratio of 1.7X, above its median of 0.2X over the past five years. ASYS’ trailing 12-month EV/S multiple sits at 1.5X, above its last five-year median of 0.9X. TRT and ASYS both appear to be cheap when compared with the Zacks Computer and Technology sector’s average of 8.5X.
Image Source: Zacks Investment Research
Factors Driving Trio-Tech Stock
Trio-Tech is benefiting from sustained demand for its burn-in and reliability solutions used in advanced AI computing applications. The company has received multiple follow-on orders for high-performance Burn-In Boards (BIBs) supporting a next-generation GPU platform, suggesting that customer engagement is extending beyond an initial award. This momentum has also translated into stronger testing volumes and improved operating performance, reinforcing the role of Semiconductor Back-End Solutions as a key growth engine.
TRT is broadening its exposure to automotive semiconductors through a new production burn-in contract with a global integrated device manufacturer supporting a major EV application. The award adds multiyear revenue visibility, expands the customer base and further validates the company’s technical capabilities in meeting demanding automotive reliability standards. The engagement also strengthens Trio-Tech’s position in a market where qualification, traceability and long-term performance remain critical.
Trio-Tech is expanding its Malaysia footprint to increase testing capacity and better serve North American and European semiconductor customers operating in Southeast Asia. At the same time, the recent equity financing strengthened liquidity, giving TRT greater flexibility to invest in capacity, technical capabilities and working capital as customer programs scale.
Factors Aiding Amtech Stock
Amtech is benefiting from sustained demand for equipment supporting AI semiconductor advanced packaging and server-board assembly. Strong bookings have continued to build backlog and improve revenue visibility, while differentiated capabilities such as TrueFlat technology and temperature uniformity are supporting customer adoption. ASYS is also broadening its participation into areas such as equipment used for semiconductor cooling components, expanding its exposure to the AI infrastructure build-out.
Amtech’s operational restructuring is translating into a more scalable business model. Product-line rationalization, the transition to semi-fabless manufacturing and greater emphasis on higher-margin offerings have lowered the company’s fixed-cost burden. Meanwhile, growth in parts and services adds a recurring element to ASYS’ revenue mix, helping strengthen margins, profitability and operating cash generation as sales expand.
Amtech has substantially strengthened its liquidity while maintaining a debt-free position. The stronger financial position provides flexibility to fund product development and other organic growth initiatives while also considering selective synergistic acquisitions. This gives management greater scope to expand capabilities without relying heavily on borrowing.
Choose ASYS Over TRT Now
Trio-Tech and Amtech both offer exposure to semiconductor spending tied to AI, but their growth profiles differ. TRT is benefiting from recurring AI-related BIB orders, expanding automotive semiconductor programs and additional testing capacity in Malaysia. ASYS, meanwhile, is seeing strong demand for advanced-packaging and server-board assembly equipment, with bookings building future revenue visibility. Its semi-fabless operating model and product rationalization are also translating growth into stronger margins and cash generation.
From a valuation standpoint, both stocks trade above their own historical levels despite remaining inexpensive relative to the broader sector. However, TRT’s current valuation stands further above its historical norm than ASYS’, indicating that market expectations for future growth are relatively higher. This suggests investors are already assigning significant value to its AI order momentum and emerging automotive opportunity, leaving the stock more dependent on continued execution. ASYS has also rerated, but its valuation implies comparatively less demanding expectations.
Trio-Tech’s growing AI and automotive exposure remains encouraging, but Amtech combines strong AI-driven demand with improving operating leverage, rising order visibility and considerable financial flexibility. Its stronger balance sheet also provides room to fund product development and selective expansion. Overall, ASYS appears to offer the more attractive risk-reward profile and looks like the better buy between the two at current levels.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amtech Systems, Inc. (ASYS): Free Stock Analysis Report
Trio-Tech International (TRT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).