

The Procter & Gamble Company’s PG Baby Care business in China is showing a notable recovery, supported by premium and super-premium innovation tailored to local consumer preferences. The company has focused on delivering stronger product performance around softness, comfort, dryness and skin protection, while also improving how those benefits are communicated to consumers. These efforts have helped strengthen the Pampers proposition in a market where consumers have become more selective about value and product efficacy. The improvement is especially important because China has been a difficult market for PG in recent years, making the latest Baby Care momentum a meaningful part of the company’s broader recovery in the region.
The progress is visible in the numbers. PG said its China Baby Care business has delivered double-digit organic sales growth in each of the past six quarters and gained nearly 5 points of value share over that period. The business has also returned to the No. 1 position in China Baby Care, while Greater China organic sales increased 4% in the latest quarter. A key contributor has been innovation in premium diapers, including products using silk materials designed to improve skin comfort and protection. The company also noted that Baby Care has become one of the strongest-performing categories within its China portfolio, helping support broader share gains in the market.
Looking ahead, sustaining this momentum will depend on PG’s ability to keep raising the innovation bar while maintaining a strong value proposition for increasingly discerning Chinese consumers. The company is emphasizing noticeable product performance, premiumization and stronger execution across both physical stores and digital channels. Procter & Gamble has already highlighted that its China recovery is becoming more broad-based from a channel perspective, with improving positions in offline retail, pure-play e-commerce and social-commerce platforms. If Baby Care continues to gain users through differentiated innovation and stronger consumer engagement, the category could remain an important driver of the company’s China growth momentum in fiscal 2027.
Church & Dwight Growth vs. Colgate’s Brand Strength
Church & Dwight’s CHD volume-led growth and Colgate-Palmolive’s CL pricing, innovation and category leadership highlight resilient momentum across the consumer staples space.
Church & Dwight is seeing stronger underlying momentum following its strategic portfolio actions, with volume-led organic growth and margin expansion supporting performance. In the second quarter of 2026, organic sales advanced 5.8%, including 5.1% growth in the Domestic business and 9.1% growth internationally. Adjusted gross margin expanded 40 basis points to 45.4%, while cash from operations increased 24.3%. Reflecting stronger-than-expected trends, CHD raised its 2026 organic sales growth outlook to 4%-5% from 3%-4% and now expects adjusted gross margin expansion of 100-120 basis points. Continued brand investment, productivity and international expansion remain important drivers of its growth trajectory.
Colgate continues to benefit from broad-based organic growth, strong pricing execution and improving volume trends, supported by its focus on premium, science-led innovation and higher brand investment. In the second quarter of 2026, organic sales increased 2.4%, while organic volume rose 0.8%. Growth remained particularly strong in Latin America and Asia Pacific, while North America stayed under pressure. Gross margin expanded 140 basis points to 61.5%, aided by productivity savings and pricing, while base business EPS increased 8%. CL also maintained its global leadership in toothpaste and manual toothbrushes, with year-to-date market shares of 41.3% and 32.7%, respectively.
PG’s Price Performance, Valuation & Estimates
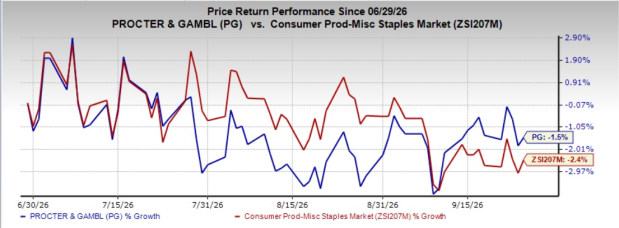
Procter & Gamble’s shares have lost 1.5% in the past three months compared with the industry’s 2.4% fall.
Image Source: Zacks Investment Research
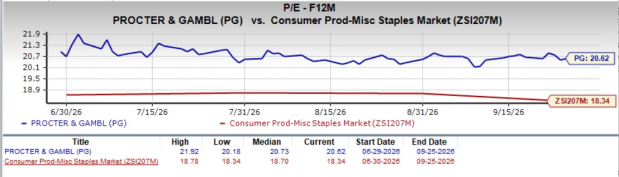
From a valuation standpoint, PG trades at a forward price-to-earnings ratio of 20.62X compared with the industry’s average of 18.34X.
Image Source: Zacks Investment Research
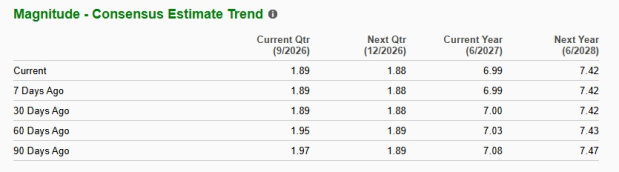
The Zacks Consensus Estimate for PG’s fiscal 2026 and 2027 EPS indicates year-over-year growth of 1.5% and 6.2%, respectively. The company’s EPS estimates for fiscal 2026 and 2027 have remained stable in the past seven days.
Image Source: Zacks Investment Research
Procter & Gamble currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Procter & Gamble Company (The) (PG): Free Stock Analysis Report
Colgate-Palmolive Company (CL): Free Stock Analysis Report
Church & Dwight Co., Inc. (CHD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).