

Equifax’s EFX growth is supported by proprietary data, artificial intelligence -enabled product innovation and expanding international operations, while improving margins provide additional earnings leverage. Strong expected free cash flow also provides flexibility for acquisitions, debt reduction and shareholder returns.
However, elevated mortgage rates may constrain transaction growth, while higher short-term borrowing increases reliance on sustained cash generation and funding-market access.
How Is EFX Faring?
Proprietary Data & AI Products Expand Growth Runway: Equifax’s Vitality Index reached 16% in the second quarter of 2026, above its 15% full-year target and 10% long-term framework. The company launched 54 AI-enabled products in the first half, supported by proprietary data sources that generate more than 90% of revenues across over 100 global data exchanges. Ignite AI Advisor and Equifax IQ are expanding across customer applications, with broader geographic rollout planned through 2026 and early 2027. Management expects EFX.AI and proprietary-data products, including The Work Number Indicator, to support adoption, share gains and revenue growth, extending Equifax’s organic growth runway.
Equifax, Inc. Revenue (TTM)
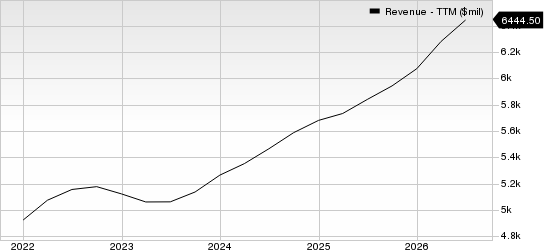
Equifax, Inc. revenue-ttm | Equifax, Inc. Quote
International Growth Broadens With Margin Expansion : EFX’s International revenues rose 8% on a reported basis and 4% in local currency to $383.1 million in the second quarter of 2026. Asia Pacific led growth, with revenues up 17% on a reported basis to $99.7 million and 7% in local currency, while Latin America increased 9% on a reported basis and 3% in local currency to $109 million. Canada and Europe grew 6% and 2%, respectively. International operating margin improved to 12.1% from 10.9%, while adjusted EBITDA margin expanded 120 basis points to 27.6%. Broader geographic growth and margin gains should support a more balanced earnings contribution from the segment.
Cash Flow Supports Flexible Capital Deployment: Equifax expects more than $1 billion of free cash flow and at least 100% cash conversion in 2026, after returning $366 million to shareholders in the second quarter. At the midpoint of its guidance, about $2.1 billion of adjusted EBITDA and cash generation provide roughly $1.5 billion of capacity for M&A and shareholder returns. Management expects leverage to remain below 3x EBITDA while completing the $750 million Círculo acquisition and continuing share repurchases at a slower pace in the second half of 2026. This cash profile should preserve flexibility for acquisitions, debt reduction and capital returns.
Elevated Mortgage Rates Constrain Transaction Growth : Meanwhile, Equifax’s U.S. mortgage revenues rose 25% in the second quarter of 2026, but industry transaction volumes fell short of management’s expectations as the 30-year fixed mortgage rate increased to about 6.6% from 6.3% at the time of the April guidance. New products and share gains partly offset weaker activity, while management now expects 2026 originations to decline by low single digits. Unless borrowing costs ease and revive purchase and refinancing demand, mortgage-related growth could remain constrained, limiting the segment’s near-term upside.
Short-Term Debt Increases Funding Dependence : EFX ended the second quarter of 2026 with $1.41 billion of short-term debt and current maturities, up from $1.04 billion at year-end 2025, as commercial paper increased to $1.40 billion from $762 million. Cash totaled $170 million, with $600 million available under its revolver. Management noted that commercial paper and operating cash funded current obligations. More than $1 billion of expected 2026 free cash flow provides support, but elevated short-term borrowing increases reliance on sustained cash generation and market access. Continued funding needs could limit balance-sheet flexibility and raise refinancing sensitivity.
Recent Financial Performance : EFX reported second-quarter 2026 results with adjusted earnings of $2.25 per share, beating the Zacks Consensus Estimate by 1.8% and increasing 12.5% from the year-ago quarter. Revenues of $1.7 billion marginally surpassed the consensus mark and rose 10.6% year over year.
EFX’s Zacks Rank & Stocks to Consider
Equifax currently carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Some better-ranked stocks in the broader Business Services sector are CBIZ, Inc. CBZ and EVERTEC, Inc. EVTC.
CBIZ carries a Zacks Rank #2 (Buy) at present. It has a long-term earnings growth expectation of 10%.
CBZ beat earnings estimates in three of the trailing four quarters and missed once, delivering an earnings surprise of 8.9%, on average.
EVERTEC currently carries a Zacks Rank of 2. It has a long-term earnings growth expectation of 10%.
EVTC beat earnings estimates in three of the trailing four quarters and missed once, with an average earnings surprise of 3.8%.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Equifax, Inc. (EFX): Free Stock Analysis Report
CBIZ, Inc. (CBZ): Free Stock Analysis Report
Evertec, Inc. (EVTC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).