

MasTec, Inc.’s MTZ latest outlook underscores a strong 2026 growth trajectory, with adjusted earnings per share (EPS) expected to jump 42% year over year to $9.30. The upgraded guidance follows a record second quarter, supported by broad-based demand and improving profitability.
In the second quarter of 2026, revenues increased 23.4% year over year to $4.37 billion, while adjusted EBITDA climbed nearly 40% to $384.2 million. Adjusted EPS surged 48.8% to $2.22, with the adjusted EBITDA margin expanding 100 basis points (bps) to 8.8%. Backlog provides further visibility. MasTec’s record 18-month backlog reached $21.4 billion, up 30% year over year and $1.1 billion sequentially. Clean Energy and Infrastructure led the backlog gains, rising 58% year over year. The segment’s revenues surged 43.4%, while EBITDA advanced 53.9%.
Power Delivery also remained a solid contributor, with revenues up 19.2% and EBITDA rising 23.7%. Pipeline Infrastructure was another standout, delivering 19.1% revenue growth and a 91% increase in EBITDA. Broad-based growth across communications, clean energy, power delivery and pipeline infrastructure markets is aiding the growth trajectory. Higher project activity, particularly in energy infrastructure, along with improved execution and productivity, adds to the tailwinds.
MTZ also closed the acquisition of The Superior Group, adding about 3,000 employees and strengthening its data-center infrastructure capabilities. The deal broadens its exposure to growing power and digital infrastructure demand. The combination of accelerating backlog, margin expansion, segment diversification and Superior’s capabilities makes the 42% EPS growth outlook a compelling marker of MasTec’s improving earnings power.
Competitive Landscape: MasTec vs. EMCOR & Quanta
AI-driven data-center expansion, grid modernization and digital infrastructure spending are creating a favorable demand backdrop for MasTec, alongside other renowned infrastructure peers including EMCOR Group, Inc. EME and Quanta Services, Inc. PWR.
EMCOR benefits from robust AI infrastructure and data-center demand, supported by $15.62 billion of remaining performance obligations and disciplined capital allocation spanning organic investment, acquisitions and shareholder returns. Quanta remains leveraged to grid modernization and power demand from data centers, while pursuing disciplined capital deployment.
However, labor shortages, tariffs, inflation, permitting delays, elevated rates and potential project-cost pressures remain near-term risks for MTZ as well as its peers, including EMCOR and Quanta. Yet, MasTec’s broader exposure to clean energy, pipelines, communications and mission-critical construction offers diversification against these peers.
MTZ Stock’s Price Performance & Valuation Trend
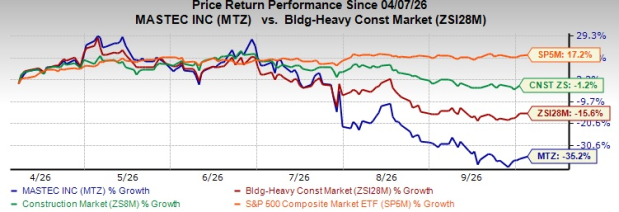
Shares of this Florida-based infrastructure construction company have plunged 35.2% over the past six months, underperforming the Zacks Building Products - Heavy Construction industry, the broader Zacks Construction sector and the S&P 500 index.
Image Source: Zacks Investment Research
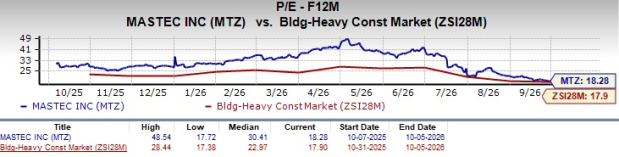
MTZ stock is currently trading at a premium compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 18.28, as shown in the chart below.
Image Source: Zacks Investment Research
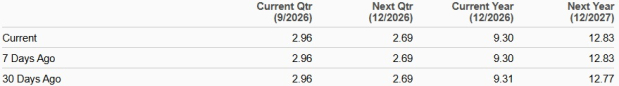
EPS Trend of MTZ
MTZ’s earnings estimates for 2026 have trended down over the past 30 days to $9.30 per share, while they grew over the same time frame to $12.83 per share for 2027. The estimated figures for 2026 and 2027 imply 42% and 37.9% year-over-year growth, respectively.
Image Source: Zacks Investment Research
MasTec stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MasTec, Inc. (MTZ): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).