

The Progressive Corporation PGR is expected to witness an improvement in its bottom line but a decline in its top line when it reports third-quarter 2026 results on Oct. 14, before the opening bell.
The Zacks Consensus Estimate for PGR’s third-quarter revenues is pegged at $23.4 billion, indicating 5.4% growth from the year-ago reported figure.
The consensus estimate for earnings is pegged at $4.43 per share. The Zacks Consensus Estimate for PGR’s third-quarter earnings has moved 2.5% north in the past seven days. The estimate indicates a year-over-year increase of 9.4%.
Decent Earnings Surprise History
Progressive’s earnings beat the Zacks Consensus Estimate in three of the trailing four quarters and missed in one.
What the Zacks Model Unveils for PGR
Our proven model does not conclusively predict an earnings beat for Progressive this time around. This is because a stock needs to have the right combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) that increases the chances of an earnings beat. That is not the case, as you can see here.
You can uncover the best stocks before they are reported with our Earnings ESP Filter.
Earnings ESP: PGR has an Earnings ESP of 0.00%. This is because both the Most Accurate Estimate and the Zacks Consensus Estimate are pegged at $4.43.
The Progressive Corporation Price and EPS Surprise
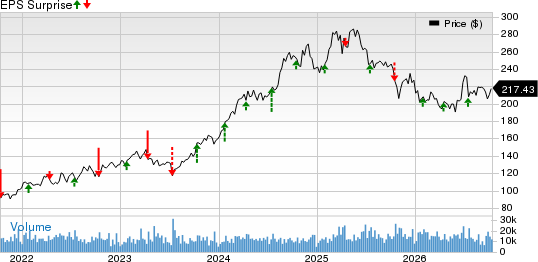
The Progressive Corporation price-eps-surprise | The Progressive Corporation Quote
Zacks Rank: PGR carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Shape Q3 Results
Growth in premiums, higher net investment income and increased fee and service revenues are likely to have aided Progressive’s third-quarter performance. Improving trends across its personal auto and commercial lines businesses are likely to have further supported the company’s results.
A diversified product portfolio, strong competitive position and solid contributions from its Vehicle and Property segments are expected to have supported premium growth. Healthy policy retention and an expanding base of policies in force are likely to have driven higher net premiums earned. The Zacks Consensus Estimate for net premiums earned is pegged at $21.9 billion, suggesting a 5.1% increase from the year-ago quarter.
The Personal Auto segment is expected to have gained from increased new business applications and policy renewals, supported by higher advertising expenditures, competitive pricing strategies and agency incentive initiatives. Continued expansion across both agency and direct distribution channels is likely to have contributed to growth in policies in force. The consensus estimate for personal auto policies in force stands at 39.4 million.
Net investment income is likely to have benefited from growth in the company’s invested asset base. The Zacks Consensus Estimate is pegged at approximately $1 billion, indicating an 11% improvement from the prior-year quarter. Progressive is also expected to have generated pretax net realized gains on securities, with the consensus estimate standing at $61 million.
However, elevated loss and loss-adjustment expenses, higher policy acquisition costs and increased other underwriting expenses are likely to have weighed on the company’s overall cost structure. The consensus estimate for the expense ratio stands at 20.47.
Disciplined underwriting practices and relatively modest catastrophe-related losses are expected to have supported underwriting margins. The Zacks Consensus Estimate for the combined ratio is pegged at 89.4, reflecting continued underwriting profitability and operational efficiency.
Stocks to Consider
Some P&C insurance stocks with the right combination of elements to deliver an earnings beat this time around are:
Arch Capital Group ACGL has an Earnings ESP of +9.62% and a Zacks Rank of 3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $1.96 per share, indicating a 29.2% year-over-year decrease.
ACGL’s earnings beat estimates in the last four reported quarters.
The Travelers Companies TRV has an Earnings ESP of +0.77% and a Zacks Rank of 3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $6.90 per share, indicating a year-over-year decrease of 15.2%.
TRV’s earnings beat estimates in each of the last four reported quarters.
Cincinnati Financial Corporation CINF has an Earnings ESP of +9.52% and a Zacks Rank of 2 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $1.91 per share, indicating a year-over-year decrease of 33%.
CINF’s earnings beat estimates in three of the last four reported quarters, while missing in one.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Progressive Corporation (PGR): Free Stock Analysis Report
The Travelers Companies, Inc. (TRV): Free Stock Analysis Report
Cincinnati Financial Corporation (CINF): Free Stock Analysis Report
Arch Capital Group Ltd. (ACGL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).