

QuidelOrtho Corporation QDEL is well-poised for growth in the coming quarters, courtesy of its strong product portfolio. The optimism, led by solid second-quarter 2026 results and progress in cost-saving initiatives, is expected to contribute further. However, risks due to overdependence on the respiratory business persist.
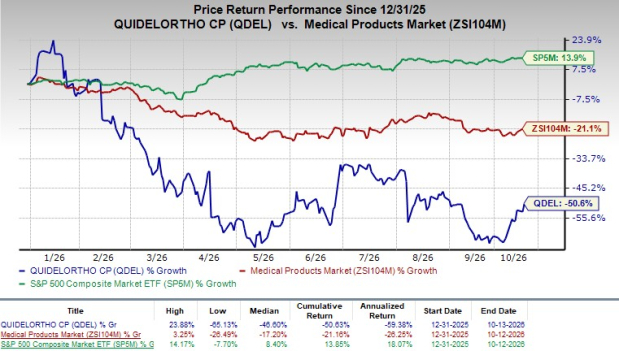
This Zacks Rank #2 (Buy) company has lost 50.6% in the year-to-date period compared with the 21.1% decline of the industry. The S&P 500 has witnessed 13.9% growth in the said time frame.
The renowned rapid diagnostic testing solutions provider has a market capitalization of $908.6 million. The company surpassed the Zacks Consensus Estimate in three of the trailing four quarters, missed once, with an average negative surprise of 94.5%.
Image Source: Zacks Investment Research
Factors Favoring QDEL’s Growth
Robust Product Portfolio: QuidelOrtho’s diversified portfolio across Labs, Immunohematology, Point of Care and Molecular Diagnostics helps cushion demand fluctuations across testing categories.
In second-quarter 2026, Labs revenues increased approximately 4% year over year to $382.9 million, Immunohematology revenues rose 1% to $134.2 million and Point of Care revenues increased 16% to $108.2 million. Excluding China, total revenues grew 6% at constant currency, with Labs revenues outside China up 9% and Immunohematology revenues outside China up 5%. Management expects the core Labs and Immunohematology businesses outside China to grow about 3% to 5% in aggregate during the second half of 2026. This recurring-revenue base provides some stability as respiratory demand and China purchasing remain uneven.
The 2026 plan assumes a typical flu season and stable testing protocols, with guidance based on a 50 to 55 million annual flu market and COVID revenue flat versus 2025. In Labs, the U.S. launch of the high-sensitivity troponin assay expands the cardiac menu, and management said that shipments have reached more than 300 U.S. customers. Internationally, the VITROS 450 rollout is targeted to lower-volume labs, and management expects placements to support mid-single-digit Labs growth over time.
Progress on Cost-Saving Initiatives:QuidelOrtho continues to focus on restructuring and productivity initiatives to strengthen its cost structure and support investments in higher-return opportunities. In the second quarter of 2026, adjusted EBITDA increased 21% year over year to $129 million, while adjusted EBITDA margin expanded to 20.5%, despite a 130-basis-point decline in adjusted gross margin to 44.4%. Adjusted operating expenses rose 2% to $219 million, but operating expenses as a percentage of revenues improved 40 basis points, reflecting ongoing cost-control efforts. The company now expects its full-year 2026 adjusted EBITDA margin to range from 21% to 22%.
Under its Optimization Plan, QuidelOrtho continues to pursue facility consolidation, procurement savings and distribution rationalization, targeting approximately $50 million in net cost savings through 2027. The company expects cumulative pre-tax restructuring charges of about $100 million through 2027, of which $28.1 million had been incurred to date. The company substantially completed the wind-down of its U.S. donor screening business by June 28, 2026. Additionally, management is evaluating working-capital efficiency, returns on instrument investments and capital spending to improve cash conversion and reduce leverage.
Solid Q2 Results: QuidelOrtho ended the second quarter of 2026 on a strong note, with both earnings and revenues surpassing the Zacks Consensus Estimate. The company benefited from solid growth in its Labs and Point of Care businesses, while strength across North America, JPAC and Latin America was encouraging. Adjusted EBITDA rose year over year, and the corresponding margin expanded, reflecting productivity initiatives and disciplined expense management.
Factors That May Offset QDEL’s Gains
Overdependence on Respiratory Segment: QuidelOrtho continues to face headwinds from subdued respiratory testing demand, with respiratory products accounting for 9% of total revenues in the first six months of 2026, down from 13% in the prior-year period, amid weaker flu and COVID-19 demand. Although second-quarter 2026 Point of Care revenues increased 16% year over year, management noted that respiratory positivity rates remained markedly below 2025 levels.
The company has also adopted a more cautious outlook for the 2026-2027 respiratory season, citing significantly lower U.S. positivity rates than the previous year and Southern Hemisphere trends that suggest a potentially later or milder season. Accordingly, QuidelOrtho now assumes that second-half respiratory demand will remain closer to the lower end of historical seasonal levels rather than its previous average-season planning baseline. While this conservative approach reduces forecasting risk, it also tempers expectations for an earnings recovery from a seasonal rebound, leaving near-term performance vulnerable to fluctuations in flu activity and associated testing volumes.
Estimate Trend
QuidelOrtho is witnessing a stable estimate revision trend for 2026. In the past 30 days, the Zacks Consensus Estimate for earnings has remained stable at 75 cents per share.
The Zacks Consensus Estimate for the company’s third-quarter 2026 revenues is pegged at $616 million, indicating an 11.9% decline from the year-ago quarter’s reported number.
Other Key Picks
Some other top-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2, reported a second-quarter 2026 adjusted earnings per share (EPS) of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. MMSI’s earnings surpassed estimates in the trailing four quarters, with the average surprise being 14.1%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QuidelOrtho Corporation (QDEL): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).