

Intuitive Surgical, Inc. ISRG reported third-quarter 2026 adjusted earnings per share (EPS) of $3.00, which beat estimates by 13.6%. The bottom line increased 25% from $2.40 in the year-ago quarter. GAAP EPS declined to $1.49 from $1.95, reflecting a significant litigation charge.
Revenues increased 21.7% year over year to $3.05 billion, surpassing expectations by approximately 4.9%. Growth was driven by higher procedure volumes, increased system placements and an expanding installed base. Worldwide da Vinci and Ion procedures collectively grew approximately 15%.
Image Source: Zacks Investment Research
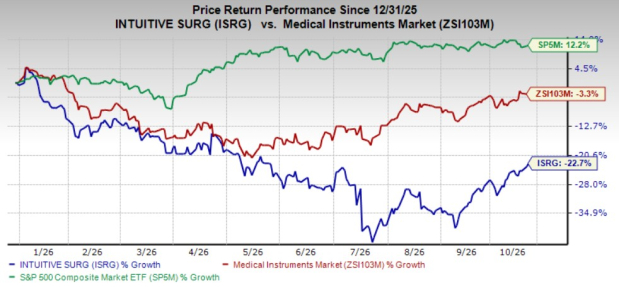
ISRG's Instruments Revenues Up 18%
Instruments and accessories revenues increased 18.3% year over year to $1.80 billion from $1.52 billion. This growth reflected a 14% increase in da Vinci procedures and 31% growth in Ion procedures.
U.S. da Vinci procedures increased 10%, while international procedures advanced 20%. Europe grew 20%, Asia increased 19% and Rest of World markets expanded 22%. India recorded 42% procedure growth, while Japan benefited from improving reimbursement conditions.
Single-port procedures climbed 55%, supported by expanding adoption in the United States and Korea. Da Vinci instruments and accessories revenue per procedure increased to approximately $1,860 from $1,800, benefiting from favorable product mix and greater adoption of newer instruments.
Intuitive's System Placements Surge 28%
Systems revenues jumped 30.3% year over year to $769.1 million from $590.4 million, reflecting stronger placements and higher operating lease revenues.
Intuitive placed 546 da Vinci systems compared with 427 a year earlier. Placements included 315 da Vinci 5 systems, 87 Xi, 65 XiR, 42 SP and 37 X systems. The company also placed 56 Ion systems versus 50 last year.
U.S. placements increased 27% to 335 systems, while international placements rose 29% to 211. Europe recorded 115 placements, up from 63 a year ago. The worldwide da Vinci installed base expanded 12% to 12,094 systems, while Ion's installed base increased 21% to 1,152.
ISRG's Services Business Benefits From Installed Base
Service revenues increased 21.8% year over year to $482.2 million from $395.9 million. Growth reflected expansion of the da Vinci and Ion installed bases and a higher proportion of da Vinci 5 systems.
Recurring revenues represented approximately 84% of total quarterly revenues, underscoring the contribution of instruments, accessories, leasing and services to Intuitive's business model.
ISRG's Margins Improve Despite Higher Costs
Adjusted gross profit increased 25% to $2.13 billion from $1.70 billion. The adjusted gross margin expanded to 69.9% from 68% a year earlier, benefiting from product cost reductions, manufacturing efficiencies and tariff refunds.
The quarter included a $28 million pretax tariff refund benefit. Excluding this item, adjusted gross margin was 68.9%, representing a 90-basis-point year-over-year improvement.
Adjusted operating income rose 30.1% to $1.27 billion. Adjusted operating expenses increased 18%, reflecting higher compensation, headcount and prototype development spending.
ISRG's Cash Position Declines Amid Share Buybacks
Intuitive ended September with $6.80 billion in cash, cash equivalents and investments, down $1.83 billion sequentially. The decline primarily reflected significant shareholder returns and capital investments.
The company repurchased 7.8 million shares for $2.94 billion during the quarter. Capital expenditures totaled $113 million. GAAP net income declined to $523 million from $704 million, including a $450 million pretax charge related to an antitrust litigation settlement.
ISRG Narrows Its 2026 Procedure Growth Outlook
Intuitive narrowed its full-year worldwide da Vinci procedure growth forecast to 14-15% from the previous 13.5-15.5% guidance. Management expects growth closer to the midpoint.
The company raised its adjusted gross margin outlook to 68.7-69.3% from 68-69%, incorporating an estimated 90-basis-point tariff impact. Adjusted operating expense growth guidance remains at 11-13%.
Management also outlined instrument pricing reductions beginning in 2027 and policy-driven reductions in China starting in November 2026. Together, these measures are expected to reduce da Vinci instruments and accessories revenue per procedure by 3-5% on a constant-mix basis, once fully implemented.
The pricing initiatives target high-volume benign procedures where affordability limits robotic surgery adoption. Although they could pressure revenue per procedure, management expects lower customer costs, expanded access and continued innovation to support procedure growth over time.
Intuitive Surgical, Inc. Price, Consensus and EPS Surprise
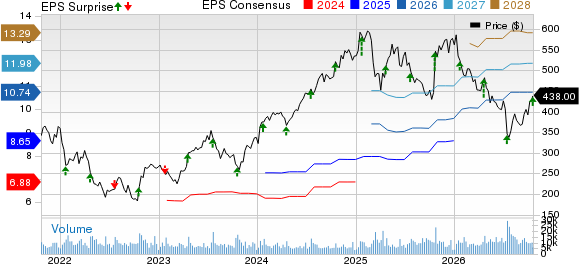
Intuitive Surgical, Inc. price-consensus-eps-surprise-chart | Intuitive Surgical, Inc. Quote
Zacks Rank & Other Key Picks
Intuitive Surgical currently carries a Zacks Rank #2 (Buy).
Some other top-ranked stocks from the broader medical space are Glaukos GKOS, Edward Lifesciences EW and Globus Medical GMED, each carrying a Zacks Rank of 2 at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Glaukos reported second-quarter 2026 earnings per share of 14 cents, which beat the Zacks Consensus Estimate by 50.00%. Revenues of $186 million surpassed the Zacks Consensus Estimate by 24.1%.
Glaukos has an estimated earnings growth rate of 268.8% for 2027. GKOS’ earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 25.87%.
Edward Lifesciences reported second-quarter 2026 adjusted EPS of 78 cents, which beat the Zacks Consensus Estimate by 6.85%. Revenues of $1.74 billion surpassed the Zacks Consensus Estimate by 2.45%.
Edward Lifesciences has an estimated long-term earnings growth rate of 12.7%. EW’s earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 4.49%.
Globus Medical reported a second-quarter fiscal 2026 adjusted EPS of $1.34, which beat the Zacks Consensus Estimate by 19.6%. Revenues of $790 million missed the Zacks Consensus Estimate by 0.35%.
Globus Medical has an estimated long-term earnings growth rate of 12.4%. GMED’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 27.88%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Intuitive Surgical, Inc. (ISRG): Free Stock Analysis Report
Edwards Lifesciences Corporation (EW): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Glaukos Corporation (GKOS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).