

Hospital operator Universal Health Services, Inc. UHS is set to report third-quarter 2026 results on Oct. 27, 2026, after the closing bell. The Zacks Consensus Estimate for earnings is currently pegged at $5.33 per share on revenues of $4.73 billion.
The third-quarter earnings estimate has witnessed three downward revisions and no upward revision over the past 60 days. The bottom-line projection indicates a year-over-year decrease of 6.3%. The Zacks Consensus Estimate for quarterly revenues suggests year-over-year growth of 5.1%.
Image Source: Zacks Investment Research
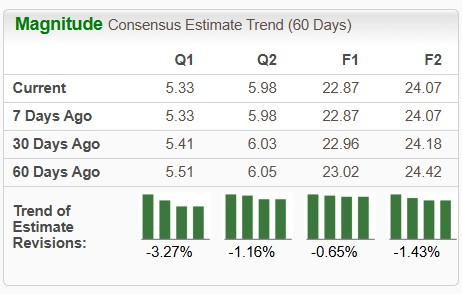
For full-year 2026, the Zacks Consensus Estimate for Universal Health’s revenues is pegged at $18.63 billion, implying a rise of 7.3% year over year. The consensus mark for full-year EPS is pegged at $22.87, implying growth of 5.2% on a year-over-year basis.
Universal Health beat on earnings in three of the last four quarters and missed once, with the average surprise being 8.3%. This is depicted in the figure below.
Universal Health Services, Inc. Price and EPS Surprise
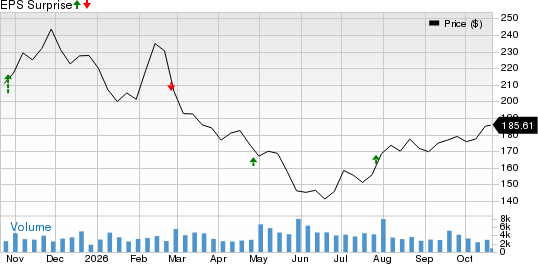
Universal Health Services, Inc. price-eps-surprise | Universal Health Services, Inc. Quote
Q3 Earnings Whispers for UHS
Our proven model does not conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. That’s not the case here.
UHS currently has an Earnings ESP of -0.60% and a Zacks Rank #4 (Sell). You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
What’s Shaping UHS’ Q3 Results?
Universal Health's performance likely benefited from higher patient days and admissions in both its Acute Care Hospital Services and Behavioral Health Care Services segments.
The Zacks Consensus Estimate for net revenues in the Acute Care Hospital Services segment is pegged at almost $2.75 billion, indicating 4.6% year-over-year growth. The consensus mark for the unit’s same-facility adjusted admissions indicates 3.4% growth from the prior-year quarter’s level.
The Zacks Consensus Estimate for net revenues in the Behavioral Health Care Services segment is pegged at $1.95 billion, indicating a 4.9% increase from the prior-year quarter’s figure. The consensus estimate for the unit’s admissions indicates a year-over-year increase of 2.6%.
The Zacks Consensus Estimate for operating income from Acute Care Hospital Services indicates a 9.6% year-over-year decline, while the same from Behavioral Health Care Services suggests a 1.1% increase.
The positives are likely to have been partially offset by rising total operating expenses by nearly 6%, due to higher salaries, wages and benefits, as well as increased costs for supplies in the third quarter, making an earnings beat uncertain. We anticipate salaries, wages and benefits to increase nearly 4.3% year over year, while other operating costs are expected to escalate 7.7%.
Stocks That Warrant a Look
While an earnings beat looks uncertain for Universal Health, here are some companies from the broader Medical space that you may want to consider, as our model shows that these have the right combination of elements to post an earnings beat this time around:
Phibro Animal Health Corporation PAHC has an Earnings ESP of +2.10% and a Zacks Rank #1. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Phibro’s bottom line for the third quarter suggests 8.2% year-over-year growth. Its earnings beat estimates in each of the past four quarters, with an average surprise of 18.4%. PAHC’s revenues for the to-be-reported quarter are pegged at $ 378.5 million, suggesting a 4% increase from the year-ago period.
ProMIS Neurosciences, Inc. PMN has an Earnings ESP of +22.43% and a Zacks Rank #2 at present.
The Zacks Consensus Estimate for ProMIS’ bottom line for the third quarter indicates a loss of $1.26 per share, reflecting a 79% year-over-year improvement. PMN has witnessed one upward revision and no downward revisions over the past 60 days.
Illumina, Inc. ILMN has an Earnings ESP of +9.16% and a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Illumina’s third-quarter bottom line suggests 3% year-over-year growth. Its earnings beat estimates in each of the past four quarters, with an average surprise of 9.7%. ILMN’s revenues for the to-be-reported quarter are pegged at $1.14 billion, indicating a 5% increase from the year-ago period’s level.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Universal Health Services, Inc. (UHS): Free Stock Analysis Report
Illumina, Inc. (ILMN): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
Promis Neurosciences (PMN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).