

Everest Group, Ltd. EG is expected to register a decline in top line but an increase in bottom line when it reports third-quarter 2026 results on Oct. 28, after the closing bell.
The Zacks Consensus Estimate for EG’s third-quarter revenues is pegged at $3.84 billion, down 11.1% from the year-ago reported figure.
The consensus estimate for earnings is pegged at $9.32 per share. The Zacks Consensus Estimate for EG’s second-quarter earnings has increased 9.8% over the past 30 days. The estimate suggests a 23.6% year-over-year increase.
What the Zacks Model Unveils for EG
Our proven model predicts an earnings beat for Everest Group this time around. This is because the stock has the right combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold), which increases the chances of an earnings beat.
Earnings ESP: Everest Group has an Earnings ESP of +3.01%. This is because the Most Accurate Estimate of $9.60 is pegged higher than the Zacks Consensus Estimate of $9.32. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Everest Group, Ltd. Price and EPS Surprise
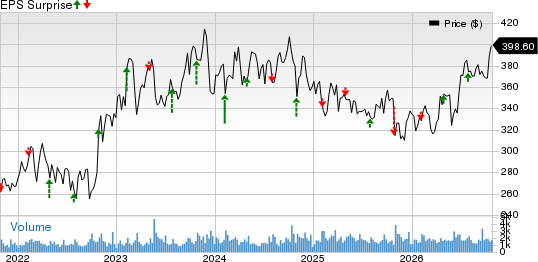
Everest Group, Ltd. price-eps-surprise | Everest Group, Ltd. Quote
Zacks Rank: EG carries a Zacks Rank #3 at present. You can see the complete list of today’s Zacks #1 (Strong Buy) Rank stocks here.
Factors Likely to Shape EG’s Q3 Results
Premium growth is likely to have been pressured by the completed exit from the Commercial Retail Insurance business and the ongoing runoff of legacy casualty exposures. We expect net written premiums to have declined 18.1% year over year to $3.1 billion in the third quarter.
The Reinsurance Treaty segment is likely to have been affected by lower premiums in casualty pro-rata and casualty excess-of-loss businesses. Softer property catastrophe reinsurance pricing during the July 2026 renewals could have further pressured premium growth, while firm casualty pricing and disciplined underwriting are expected to have partly offset the weakness. We estimate premiums earned of $2.2 billion in the to-be-reported quarter.
The Global Wholesale & Specialty segment is likely to have benefited from product and geographic diversification and growth in niche specialty lines. However, deliberate reductions in U.S. property and casualty business could have limited premium growth. We estimate premiums earned of $750 million in the to-be-reported quarter.
Net investment income is likely to have benefited from an increase in fixed maturities, a rise in income from limited partnerships, and an increase in income from other alternative investments. We expect net investment income to have been $561.5 million. The Zacks Consensus Estimate is pegged at $546.6 million.
Catastrophe losses, elevated weather-related claims and pressure on casualty underwriting margins are likely to have weighed on underwriting profitability. However, Everest’s disciplined risk selection could have partly offset these headwinds. We expect the combined ratio to be 102% in the to-be-reported quarter. The Zacks Consensus Estimate for the metric is pegged at 101.8%.
Total claims & expenses are likely to have decreased largely owing to lower incurred losses and loss adjustment expenses, commission, brokerage, taxes and fees, and other underwriting expenses. We expect the metric to be $3.5 billion.
Share buybacks in the to-be-reported quarter are anticipated to have provided a boost to the bottom line.
Other Stocks to Consider
Here are some other insurance stocks you may want to consider, as our model shows that these, too, have the right combination of elements to post an earnings beat:
The Allstate Corporation ALL has an Earnings ESP of +5.25% and a Zacks Rank #3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $7.03 per share, indicating a year-over-year decrease of 37.1%.
ALL’s earnings beat estimates in each of the last four reported quarters.
Arch Capital Group Ltd. ACGL has an Earnings ESP of +11.70% and a Zacks Rank #3 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $2.05 per share, indicating a year-over-year decrease of 26%.
ACGL’s earnings beat estimates in each of the last four reported quarters.
The Hanover Insurance THG has an Earnings ESP of +6.83% and a Zacks Rank of 2 at present. The Zacks Consensus Estimate for third-quarter 2026 earnings is pegged at $4.47 per share, indicating a 12.2% year-over-year decrease.
THG’s earnings beat estimates in each of the last four reported quarters.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Everest Group, Ltd. (EG): Free Stock Analysis Report
The Allstate Corporation (ALL): Free Stock Analysis Report
The Hanover Insurance Group, Inc. (THG): Free Stock Analysis Report
Arch Capital Group Ltd. (ACGL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).