

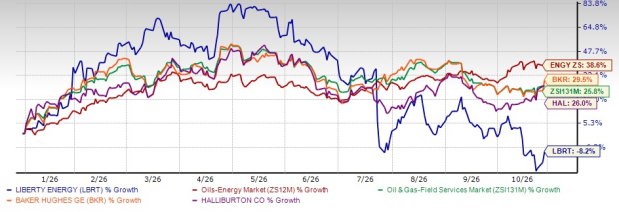
Shares of Liberty Energy Inc. LBRT have lost 8.2% year to date (YTD), lagging behind both the sector and the sub-industry’s gains of 38.6% and 25.8%, respectively. Peer comparison further highlights the weakness, as LBRT underperformed its peers Baker Hughes Company BKR andHalliburton Company HAL. Both BKR and HAL rose 29.5% and 26%, respectively, during the same time period.
LBRT Underperforms Industry, Sector & Peer Companies (BKR and HAL)
Image Source: Zacks Investment Research
Liberty Energy is a leading North American oilfield services provider, delivering integrated solutions across hydraulic fracturing, wireline, proppant delivery, sand mining and natural gas systems for upstream and midstream energy companies. The company also emphasizes innovation through next-generation digiFleets, dual-fuel technologies and Liberty Power Innovations, which expands its presence into distributed power generation for data centers and industrial customers, strengthening its position as a technology-driven energy services leader.
Liberty Energy has recently drawn investor attention following the release of its third-quarter results. The company reported year-over-year earnings growth but fell short of estimates, as strong operational execution and modest pricing gains were partly offset by drilling-related delays and cost inflation. Meanwhile, peers Halliburton and Baker Hughes also reported their third-quarter 2026 results, with both companies surpassing earnings estimates and improving performance compared with the year-ago quarter. Against this backdrop, investors should assess Liberty Energy’s latest performance and growth prospects to determine whether to buy the stock, hold existing positions or book profits.
Factors Favoring LBRT Stock’s Growth
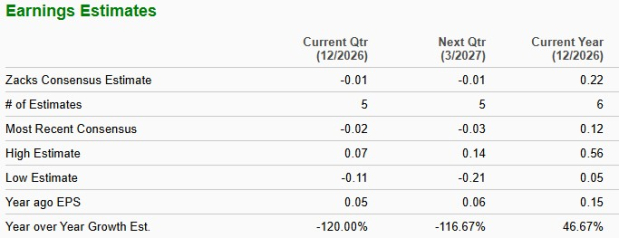
LBRT’s 2026 Earnings Estimates Are Going Up: The Zacks Consensus Estimate for LBRT’s 2026 earnings is pegged at 22 cents per share, indicating a 46.7% year-over-year rise. However, the Zacks Consensus Estimate for Baker Hughes and Halliburton indicates year-over-year earnings declines of 0.4% and 3.7%, respectively, for 2026.
LBRT’s Earnings Estimate
Image Source: Zacks Investment Research
Strong Revenue Growth and Improving Completions Activity: Liberty Energy's third-quarter 2026 results demonstrate a meaningful improvement in revenues compared with the previous year. Revenues increased 26% year over year to approximately $1.2 billion from $947.4 million, reflecting strong fleet utilization, modest pricing improvements and better operating execution. Management stated that the company's completions business had improved meaningfully from its early-year cyclical lows. If customer activity continues to strengthen and pricing improves further, LBRT could benefit from better equipment utilization and improved earnings potential.
Significant Growth Opportunity in AI Data Center Power: Liberty Energy is expanding beyond traditional oilfield services through its distributed power business. In October 2026, the company entered into a strategic development agreement with a leading AI laboratory and a dedicated infrastructure platform to provide 1.2 gigawatts of power services for data center campuses. The agreement targets an initial energy service agreement covering approximately 500 megawatts by December 2026, with phased energization scheduled from the fourth quarter of 2027 through the first quarter of 2029. Management also indicated that the arrangement includes a substantial capacity-fee prepayment. This opportunity could help LBRT access growing demand for reliable power from AI infrastructure.
Dividend Increase Signals Management's Confidence: Liberty Energy increased its quarterly cash dividend by 11%, from 9 cents to 10 cents per share, beginning in the fourth quarter of 2026. The company distributed approximately $15 million in cash dividends during the third quarter, demonstrating its continued commitment to returning capital to shareholders while pursuing business expansion. The dividend increase may appeal to investors looking for income alongside potential capital appreciation. It also reflects management's confidence in LBRT's business strategy and future opportunities.
Challenges for LBRT Stock
Return to Quarterly Net Loss Raises Profitability Concerns: Despite reporting 26% year-over-year revenue growth in the third quarter of 2026, Liberty Energy recorded a net loss of $39.1 million, compared with net income of $43.1 million in the same period of 2025. Adjusted net income was only $10 million, down from $14 million in the second quarter, while adjusted earnings per share declined from 9 cents to 6 cents. These results indicate that higher revenues have not yet translated into stronger bottom-line performance. If operating costs remain elevated or pricing gains prove insufficient, LBRT could struggle to convert business growth into sustainable earnings, creating uncertainty for shareholders.
Rising Debt Increases Financial Risk: Liberty Energy's expansion strategy has increased its reliance on debt financing. As of Sept. 30, 2026, the company reported approximately $1.3 billion in total debt, primarily consisting of senior convertible notes issued earlier in the year, while cash on hand stood at $119 million. Although total liquidity was approximately $669 million and its revolving credit facility remained largely undrawn, substantial borrowing can limit financial flexibility. Convertible notes may also create potential shareholder dilution if converted into equity. If operating performance weakens or new projects require additional capital, servicing obligations and funding expansion could become more challenging.
Heavy Capital Spending Could Pressure Cash Flow: Liberty Energy is investing substantial amounts in distributed power infrastructure, equipment and technology, creating a risk that near-term cash requirements could outpace internally generated funds. During the third quarter of 2026, cash uses for capital expenditures, dividends and long-term deposits totaled approximately $622 million, including around $450 million in power generation deposits and related investments. This spending supports future growth but ties up capital before many projects begin generating revenues. The company is also pursuing project-level financing, which management expects to launch in early 2027 as projects advance. If financing is delayed, construction costs rise, or projects take longer to become operational, LBRT could face additional funding pressure.
Cost Inflation and Drilling Delays Could Weigh on Margins: Liberty Energy's third-quarter results were affected by drilling-related delays and cost inflation, which partially offset stronger utilization and modest pricing increases. Revenues were nearly flat sequentially, rising only around 1% from the second quarter. Management also expects fourth-quarter weather and holiday-season effects to affect activity, although deferred work and continued demand could partly offset them. These factors highlight the sensitivity of LBRT's earnings to customer drilling schedules, operating expenses and seasonal disruptions. If producers postpone activity or service-price increases fail to keep pace with inflation, margins could remain under pressure.
Final Verdict on LBRT Stock
The Zacks Rank #3 (Hold) company’s revenue growth, improving completions activity and rising 2026 earnings estimates offer some support for its long-term prospects. Liberty Energy’s expansion into distributed power generation for AI data centers, including a planned 1.2-gigawatt power services arrangement, creates an additional growth opportunity. Its 11% dividend increase also signals management’s confidence.
However, profitability remains a concern, as LBRT reported a third-quarter net loss despite higher revenues, while cost inflation and drilling delays continue to pressure margins. Rising debt, limited cash reserves and substantial capital spending could constrain financial flexibility. Moreover, the stock’s significant year-to-date underperformance against peers — Halliburton and Baker Hughes — highlights weak investor sentiment. Given the promising growth opportunities but significant execution, profitability and financing risks, retaining LBRT stock appears prudent for investors until the company demonstrates more consistent earnings and cash flow generation.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Liberty Energy Inc. (LBRT): Free Stock Analysis Report
Halliburton Company (HAL): Free Stock Analysis Report
Baker Hughes Company (BKR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).