

Zebra Technologies Corporation ZBRA is slated to report third-quarter 2026 results before the opening bell on Nov. 3.
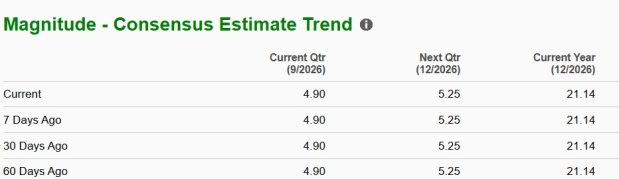
The Zacks Consensus Estimate for third-quarter earnings has been stable over the past 60 days. The consensus estimate for earnings is pegged at $4.90, suggesting a 26.3% rise from the prior-year reported number. The Zacks Consensus Estimate for revenues is $1.56 billion, indicating an 18.5% increase on a year-over-year basis.
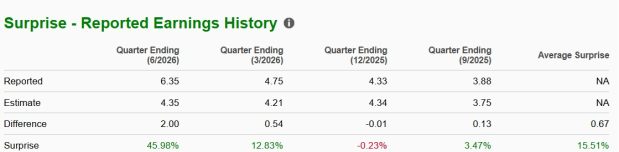
ZBRA beat the Zacks Consensus Estimate for earnings in three of the trailing four quarters and missed once. The company has a trailing four-quarter earnings surprise of roughly 15.5%, on average.
Q3 Earnings Whispers for ZBRA
Our proven model does not conclusively predict an earnings beat for ZBRA this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. But that’s not the case here. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
ZBRA has an Earnings ESP of 0.00% and a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping ZBRA’s Q3 Results
Zebra Technologies is benefiting from broad demand across retail, manufacturing and healthcare, with mobile computing, printing, machine vision and RFID (radio frequency identification), which is likely to have supported growth across its segments in the third quarter.
Higher sales of mobile computing solutions are expected to have driven the company’s Connected Frontline segment. Solid demand for printing solutions, machine vision, data capture and RFID products is likely to have aided the Asset Visibility & Automation segment’s performance.
ZBRA has also been advancing digital capabilities, optimizing the supply chain, expanding its data analytics capability and focusing on marketing activities to better engage with customers. The benefits of these initiatives are expected to reflect on its third-quarter performance.
For the third quarter, the Zacks Consensus Estimate for the Connected Frontline segment’s sales is pegged at $881 million. The consensus mark for the Asset Visibility & Automation segment’s sales is pegged at $689 million.
ZBRA Stock’s Price Performance and Valuation
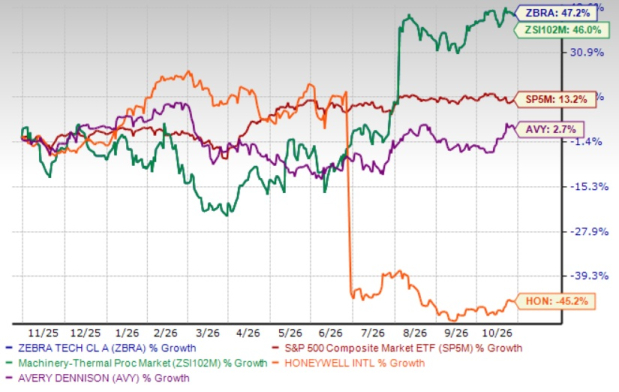
ZBRA’s shares have popped 47.2% in the past year, outperforming the Zacks Manufacturing - Thermal Products industry’s rise of 46% and the S&P 500’s increase of 13.2%. With respect to its peers, Honeywell International Inc. HON and Avery Dennison Corporation AVY shares have declined 45.2% and increased 2.7%, respectively, over the same time frame.
ZBRA’s One-year Price Performance
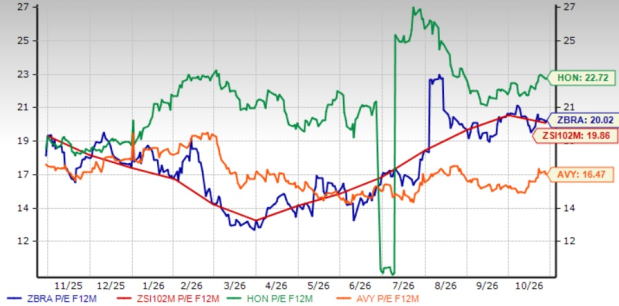
From a valuation standpoint, ZBRA has a forward 12-month price-to-earnings ratio of 20.02, modestly above the industry average of 19.86. It is trading at a discount to Honeywell and at a premium to Avery Dennison. Zebra Technologies and Avery Dennison both have a Value Score of C, while Honeywell has a Value Score of B.
ZBRA’s P/E F12M Vs. Industry, HON and AVY
Investment Thesis for ZBRA Stock
ZBRA is witnessing growth across the healthcare, manufacturing and retail & e-commerce end markets. Its integrated hardware, software and services portfolio is deepening customer adoption of automation and artificial intelligence (AI)-enabled workflows.
Healthy cash generation continues to support share repurchases and investment, while device upgrade cycles and growing software adoption strengthen the longer-term outlook. The company has also steadily strengthened its business through acquisitions including Elo Touch Solutions, Inc.
How Should Investors Play ZBRA Stock?
Zebra Technologies remains well-positioned for growth, supported by broad demand for mobile computing, printing, machine vision and RFID across key end markets. Acquisitions such as Elo Touch and Photoneo are expanding its addressable market and strengthening automation and AI capabilities. Strong free cash flow enables investments and substantial share repurchases, while healthy earnings growth expectations reinforce the outlook. Backed by a positive earnings outlook, ZBRA is a prudent pick ahead of the earnings release for investors seeking continued growth and long-term upside.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Zebra Technologies Corporation (ZBRA): Free Stock Analysis Report
Honeywell International Inc. (HON): Free Stock Analysis Report
Avery Dennison Corporation (AVY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).