

HP Inc. HPQ and Apple Inc. AAPL are two prominent players in the computer hardware industry, serving overlapping but distinct segments of the technology market. HP focuses on personal computing, workstations, printing and related services, while Apple operates an integrated ecosystem spanning iPhones, Mac computers, iPads, wearables and digital services.
With artificial intelligence (AI) creating new opportunities across personal computing and consumer electronics, both companies are investing in AI-enabled products to strengthen customer engagement and support growth. So, which stock offers greater investment potential? Let's examine their growth prospects, competitive advantages, risks and valuations to determine which presents the more compelling investment case.
The Case for HPQ Stock
HPQ is positioned to benefit from the growing adoption of AI-capable personal computers, demand for premium commercial devices and the expansion of industrial printing. Its strategy emphasizes higher-value products, recurring printing relationships and cost controls to protect profitability amid rising component costs.
AI PCs represent an increasingly important growth opportunity for HPQ. In the third quarter of fiscal 2026, AI PCs accounted for 46% of Personal Systems shipments, up from 44% in the preceding quarter. Management expects the mix to reach approximately 50% by fiscal year-end, increase to 60-70% in fiscal 2027 and exceed 70% in fiscal 2028. HPQ is also working with more than 150 software partners to expand AI use cases.
HPQ's premium and commercial PC strategy is already delivering revenue growth despite declining unit volumes. In the third quarter of fiscal 2026, Personal Systems revenues increased 18.5% year over year to $11.77 billion, while PC units declined 15.8%. Average selling prices rose 40.8%, reflecting pricing and a richer product mix. Commercial Personal Systems revenues increased 21.9%, while Consumer revenues grew 10.1%.
HPQ also gained 2.6 percentage points of sequential share in premium PCs and 1.8 points in workstations. These developments highlight its ability to prioritize higher-value categories even as the broader PC market faces pressure. Cost management and operational efficiency remain important to HP's earnings outlook. Rising memory and storage costs have pressured Personal Systems margins, which
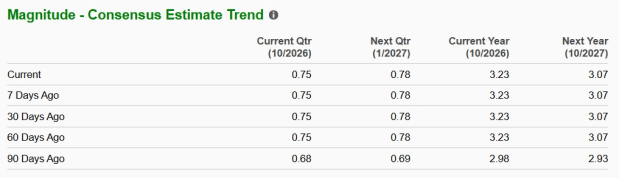
The Zacks Consensus Estimate for HPQ's fiscal 2027 revenues is pegged at $60 billion, indicating year-over-year growth of 8.5%. The Zacks Consensus Estimate for HPQ’s fiscal 2027 earnings is pegged at $3.23, indicating year-over-year growth of 3.5%. The estimates have remained unchanged for the past 60 days.
Image Source: Zacks Investment Research
The Case for AAPL Stock
Apple is positioned to capitalize on its integrated hardware and software ecosystem, growing Services business and expanding AI capabilities. Its strategy combines premium devices, proprietary silicon, privacy-focused AI features and recurring digital services to strengthen customer loyalty and encourage product upgrades. Apple's expanding AI capabilities provide an important growth opportunity. In September 2026, the company introduced the iPhone 18 Pro, featuring its A20 Pro chip and enhanced Siri AI capabilities.
Apple’s updated assistant is designed to use personal context and perform actions across applications, while Apple's Private Cloud Compute architecture supports its privacy-focused approach to AI. The A20 Pro chip incorporates a second Neural Engine and uses 2-nanometer technology, strengthening Apple's ability to run advanced AI workloads on its devices. These developments could encourage upgrades and reinforce differentiation in the premium smartphone market.
Apple's installed base and Services business provide a substantial foundation for recurring revenues. In the third quarter of fiscal 2026, Services revenues increased 12.1% year over year to $30.74 billion, accounting for 28.1% of total sales. The company recorded revenue highs across all Services categories, while paid subscriptions exceeded 1.5 billion. Apple is growing across cloud services, payments, the App Store, AppleCare, Music and video.
The Mac business is another potential growth driver. Third-quarter fiscal 2026 Mac revenues increased 28.7% year over year to $10.35 billion, supported by demand for MacBook Neo and MacBook Pro. Apple reported records for both customers new to Mac and existing users upgrading their devices. Nevertheless, Apple faces several risks. Supply constraints are expected to intensify across iPhone, Mac and iPad, while rising memory costs could pressure profitability.
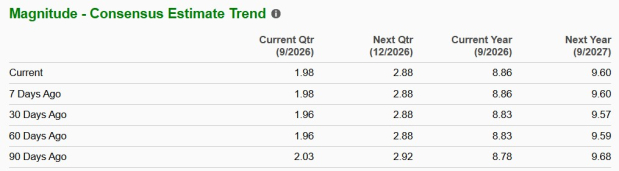
Management expects fourth-quarter fiscal 2026 revenue growth of 9-11%, slower than the 16.4% reported in the June quarter. The Zacks Consensus Estimate of Apple’s fiscal 2026 revenues is pegged at $477 billion, indicating year-over-year growth of 14.7%. The Zacks Consensus Estimate for AAPL’s fiscal 2027 earnings is pegged at $8.86, indicating year-over-year growth of 18%. The estimates have been revised upward in the past 30 days.
Image Source: Zacks Investment Research
Stock Price Performance and Valuation of HPQ & AAPL
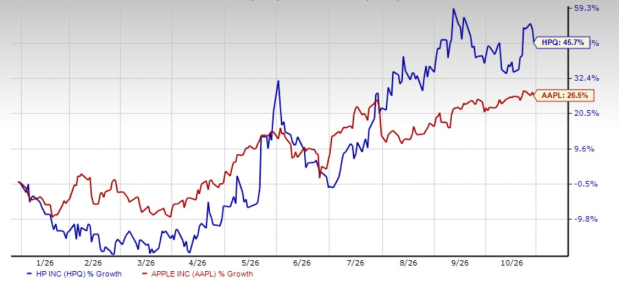
Shares of HPQ and AAPL have surged 45.7% and 26.5%, respectively, in the year-to-date period.
YTD Performance Chart
Image Source: Zacks Investment Research
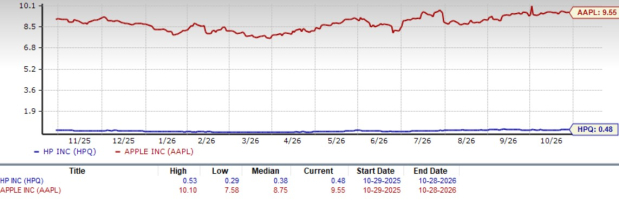
HPQ is trading at a forward 12-month Price-to-Sales ratio of 0.48X, much lower than AAPL’s P/S multiple of 9.55X.
Forward 12-Month (P/S) Valuation Chart
Image Source: Zacks Investment Research
Conclusion: HPQ vs. AAPL
HPQ offers compelling business opportunities through its expanding AI PC portfolio, growing premium commercial PC segment and industrial printing operations. AI PCs accounted for 46% of Personal Systems shipments in the third quarter of fiscal 2026, with further growth expected. HP is also strengthening recurring printing revenues through subscription offerings while expanding tank and 3D printing. Additionally, restructuring initiatives, product redesign and cost optimization could improve operational efficiency and support profitability as component costs stabilize. Apple’s growing Services business, large installed base, AI-enabled product ecosystem and substantial cash generation support its long-term growth outlook. However, from the valuation perspective, HPQ seems to be a better choice right now. HPQ and AAPL carry a Zacks Rank #3 (Hold) each at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Apple Inc. (AAPL): Free Stock Analysis Report
HP Inc. (HPQ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).