

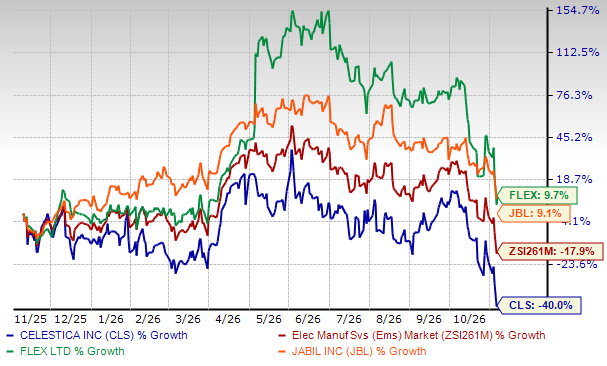
Celestica Inc. CLS has plummeted 40% over the past year compared with the industry’s decline of 17.9%. It has also lagged peers like Flex Ltd. FLEX and Jabil Inc. JBL. Flex has gained 9.7%, and Jabil is up 9.1% over this period.
Despite the blip, Celestica remains an attractive investment option, supported by its growing exposure to artificial intelligence (AI) infrastructure, improving profitability and robust long-term growth prospects. Let us delve a little deeper into the tailwinds of the company.
One-Year CLS Stock Price Performance
Image Source: Zacks Investment Research
Portfolio Strength, R&D Focus Propel CLS
Celestia has been benefiting from the ongoing generative AI boom, driven by solid demand trends for AI/ML compute and networking products from hyperscale customers. AI investments are driving demand for its enterprise-level data communications and information processing infrastructure products, such as routers, switches, data center interconnects, edge solutions and servers, and storage-related products.
Celestica’s focus on product diversification and increasing its presence in high-value markets is positive. Its strong research and development foundations allow it to produce high-volume electronic products and highly complex technology infrastructure products for a wide range of industries. The company continuously enhances its manufacturing, engineering, design, quality and supply-chain capabilities while developing trusted relationships with leading customers. This strategy has augmented its market penetration in each of the markets it serves.
Its customer base includes several leading manufacturers from multiple industries, including communication, healthcare, aerospace and defense, energy, semiconductor and various cloud-based and other service providers. Such a diverse customer base enhances business resilience by reducing dependence on a single industry and minimizing the effects on financial results from an economic downturn in one specific sector.
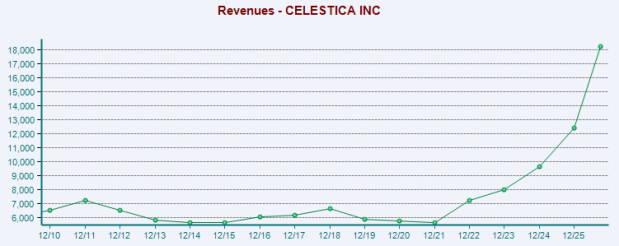
Solid Revenue Buildup Aids CLS
Celestica’s Hardware Platform Solutions (HPS) portfolio, comprising advanced networking switches and data center infrastructure products, is witnessing robust demand as hyperscalers upgrade their networks to support increasingly complex AI workloads. The ongoing transition to 800G networking solutions and the ramp-up of next-generation 1.6T programs are strengthening Celestica’s competitive position.
The company recently introduced its DS6005 data center switch featuring co-packaged optics, expanding its portfolio of power-efficient networking solutions for AI fabrics. Celestica has launched its latest storage platform, the SD6300 ultra-dense storage expansion system, to cater to the exponential AI data growth across traditional enterprise and hyperscale data centers. With a compact footprint of only 1125 mm (including cable management assembly), the SD6300 maximizes utilization of existing data center floor space as it can be accommodated within standard 1200 mm racks.
The company also introduced two new 1.6TbE data center switches, the DS6000 and DS6001, to support high-bandwidth, AI/ML data center applications. While the DS6000 is a 3RU, 64-port x 1.6TbE data center switch for traditional air-cooled data center installations, the DS6001 is a 2OU, 64-port x 1.6TbE switch offering a hybrid-cooled solution based on the 21-inch OCP ORv3 rack. Together, the switches double the switching capacity of Celestica’s current offerings.
Image Source: Zacks Investment Research
Estimate Revision Trend
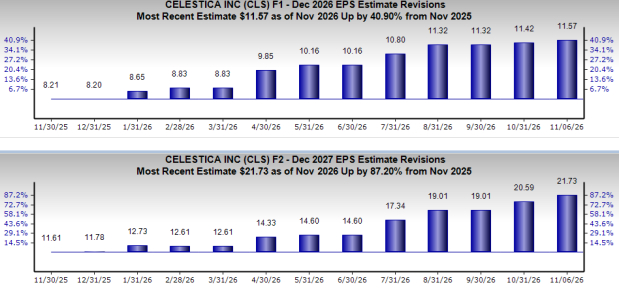
Earnings estimates for Celestica for 2026 have moved up 40.9% to $11.57 over the past year, while the same for 2027 has improved 87.2% to $21.3. The positive estimate revision depicts optimism about the stock’s growth potential.
Image Source: Zacks Investment Research
End Note
As the company scales up production volumes and costs go down, the adoption of Celestica’s products is likely to soar across several industries, including automotive, data center and high-performance computing, telecommunications, medical, aerospace and defense. The positive estimate revision depicts bullish sentiment for the stock.
The firm delivered a trailing four-quarter average earnings surprise of 8.2%. It has a long-term earnings growth expectation of 13% and a VGM Score of B. Celestia currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Riding on a healthy earnings surprise history and favorable Zacks Rank, it appears primed for price appreciation in the future. Consequently, investors are likely to profit if they bet on this stock now for the long run.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Celestica, Inc. (CLS): Free Stock Analysis Report
Jabil, Inc. (JBL): Free Stock Analysis Report
Flex Ltd. (FLEX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).