

Shares of Arch Capital Group Ltd. ACGL have gained 19.5% over the past year, outperforming its industry’s 10.2% growth.
Consistent underwriting profitability, higher investment income, and strong capital returns drove the performance. Its diversified business operations, resilient mortgage insurance portfolio and disciplined capital allocation continue to support earnings and book value growth. However, increasing competition in property reinsurance and moderating premium growth in certain markets remain concerns.
Image Source: Zacks Investment Research
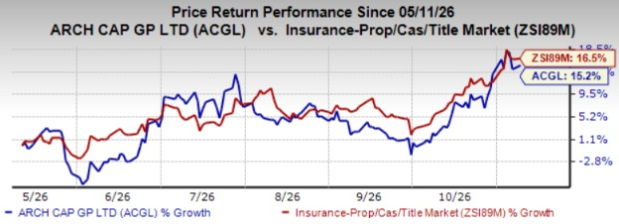
Shares of some other players like The Progressive Corporation PGR, W.R. Berkley Corporation WRB and NMI Holdings Inc. NMIH have lost 9.9% and 5.6%, respectively, in the past year.
ACGL's Average Target Price Suggests Upside
Based on short-term price targets offered by 20 analysts, the Zacks average price target is $112.35 per share. The average suggests a potential 4.7% upside from the last closing price.
ACGL’s Valuation
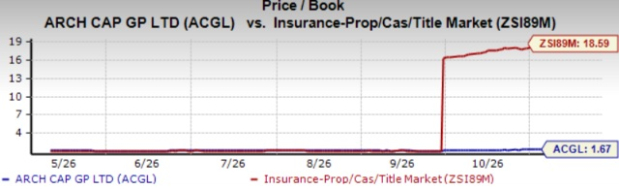
Based on the trailing 12-month price-to-book ratio, Arch Capital is currently trading at 1.65X, below its industry average of 18.55X. The insurer has a Value Score of B.
Image Source: Zacks Investment Research
Return on Equity of ACGL
Arch Capital’s trailing 12-month return on equity is 19.7%, ahead of the industry average of 7.5%, reflecting how effectively the company is utilizes its shareholders’ equity.
ACGL Growth Projection
The Zacks Consensus Estimate for Arch Capital’s 2026 earnings per share (EPS) indicates a year-over-year increase of 3.5%. The consensus estimate forrevenues is pegged at $17.69 billion, implying a year-over-year decrease of 5.8%. The Zacks Consensus Estimate for Arch Capital’s 2027 EPS and revenues indicates a year-over-year decrease of 0.8% and 1.4%, respectively, from the corresponding 2026 estimates.
ACGL’s earnings grew 30% over the last five years, better than the industry average of 22.7 %. The expected long-term earnings growth is pegged at 3%.
Optimistic Analyst Sentiment for ACGL
The company has witnessed nine upward revisions for 2026 earnings estimates over the past 30 days, while six revisions for 2027 earnings, with no downward revisions. The Zacks Consensus Estimate for 2026 and 2027 earnings estimates moved up 5.7% and 2.1%, respectively, over the past 30 days.
Key Points to Note for ACGL Stock
Arch Capital continues to benefit from disciplined underwriting and effective risk selection across its Insurance, Reinsurance and Mortgage segments. In the third quarter of 2026, its overall current accident-year combined ratio, excluding catastrophe losses, was 81.2%, reflecting strong underlying underwriting profitability. The Reinsurance segment reported a combined ratio of 78.3%, while the Insurance segment's combined ratio was 94.4%. Management remains constructive on casualty insurance opportunities, particularly excess and surplus casualty, construction and national accounts, where pricing conditions continue to support profitable growth.
ACGL's investment income remains an important earnings driver, supported by a growing investment portfolio and higher reinvestment yields. As of Sept. 30, 2026, investable assets reached $49.2 billion, while pretax net investment income increased to $451 million from $408 million in the prior-year quarter. Continued cash generation and reinvestment should support investment income, earnings and book value growth.
Arch Capital continues to leverage third-party capital to manage risk and improve capital efficiency. Its Reinsurance segment generated $393 million in underwriting income in the third quarter, with a combined ratio of 78.3%. Its underwriting expertise and ability to structure risks make it well-positioned to attract alternative capital and expand its reinsurance platform.
Arch Capital continues to strengthen its competitive position through strategic acquisitions and targeted investments. The MidCorp and Entertainment acquisitions expand its U.S. middle-market presence, while investments in local teams support growth opportunities. Its European expansion through Arch Insurance Company (Europe) Limited further enhances diversification and market reach.
Arch Capital's strong capital position and cash generation support shareholder distributions and business investments. The company generated $1.8 billion in operating cash flow in the third quarter of 2026 and repurchased 14.8 million shares for approximately $1.4 billion. Continued capital generation provides flexibility to pursue attractive underwriting opportunities and return excess capital through share repurchases.
End Notes
Arch Capital benefits from strong underwriting, higher investment income, growing third-party capital, strategic acquisitions and solid capital. Price appreciation, cheap valuation, diversified earnings, optimistic analyst sentiment and favorable return on equity make this Zacks Rank #2 (Buy) stock adding to one's portfolio. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Arch Capital Group Ltd. (ACGL): Free Stock Analysis Report
W.R. Berkley Corporation (WRB): Free Stock Analysis Report
The Progressive Corporation (PGR): Free Stock Analysis Report
NMI Holdings Inc (NMIH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).